
The Housing Bill's 350-Home Threshold: Who It Captures and What Comes Next
Mar 11, 2026 · 11 min read
The 21st Century ROAD to Housing Act targets investors with 350+ homes. We mapped every entity it captures, what they own, and where they concentrate.
Executive Summary
The 21st Century ROAD to Housing Act defines "institutional investor" as any entity controlling 350 or more single-family homes, a threshold that doesn't map to traditional industry datasets. Parcl Labs' true owner technology identified who meets that threshold within hours of the bill's introduction.
The 350+ universe is smaller than most people assume. ~140 entities meet the 350+ threshold. These companies control ~530,000 single-family homes, just 0.59% of total U.S. single-family housing stock.
The national number understates the local impact. These portfolios are concentrated in a handful of Sun Belt and Midwest metros. In five metros, 350+ investors own more than 3% of all single-family homes. Atlanta stands alone at 71,625 units and 4.16% concentration, more than double the next-largest metro.
In Atlanta's most concentrated zip codes, 350+ investors own more than 1 in 10 homes and account for 25%+ of active for-sale listings. The bill's impact, if passed, would be felt block by block.
The bill aims to keep large investors from competing with homebuyers for available housing. But the largest investors are already net sellers, and the homes they're offloading aren't reaching owner-occupants. Investor-to-investor sales have risen sharply since 2019, climbing from ~27% to ~37-39% of all transactions. Investor selling may simply redistribute properties among investor tiers rather than create new homeowners.
The policy situation is evolving fast. No matter where you stand on this issue, teams with real-time data have an advantage in positioning for what comes next. Parcl Labs is the only way to track it live. The Data Vault provides direct access to the data behind this analysis, and Portfolio Hunter lets you track any investor portfolio in the country.
Background: The 350-Unit Line Nobody Was Tracking
The 21st Century ROAD to Housing Act is currently working through Congress. The bill targets institutional single-family rental investors with a threshold that caught much of the industry flat-footed: entities controlling 350 or more single-family homes would be banned from future acquisitions, with limited exceptions.
The 350+ number matters because it does not map to traditional portfolio segmentation research, which typically cuts at 100+ homes or 1,000+ homes. Most firms could not immediately answer a basic question: who does this actually capture?
We have the data. We ran the analysis across every single-family portfolio in our system:
True owner mapping. Our entity resolution technology maps individual LLCs and subsidiaries back to their true parent owner. An operator with 150 homes in one subsidiary and 201 in another is rolled up as a single 351-home portfolio.
Business model classification. We observe actual property-level activity, including rental listings, holding periods, new construction, and acquisition patterns, to classify each owner's operating model and isolate the ones doing what the bill targets: institutional single-family rentals. Government entities, homebuilders, nonprofits, and other holders that would inflate the count are removed.
Through this approach, we identified impacted entities and the full inventory of properties they control.
This analysis builds on our recent research into investor selling behavior. In Are Investors Already Heading for the Exits?, we found that investors are listing homes for sale at rates far exceeding their share of the housing stock, and flagged that if a market shock pushed concentrated operators to exit, it could move local housing prices for everyone.
The ROAD Act could introduce that kind of external pressure.
350+ Investors Own Less Than 1% of U.S. Single-Family Homes
~140 entities meet the bill's 350+ threshold, controlling approximately 530,000 single-family homes. That is 0.59% of total U.S. single-family housing stock.
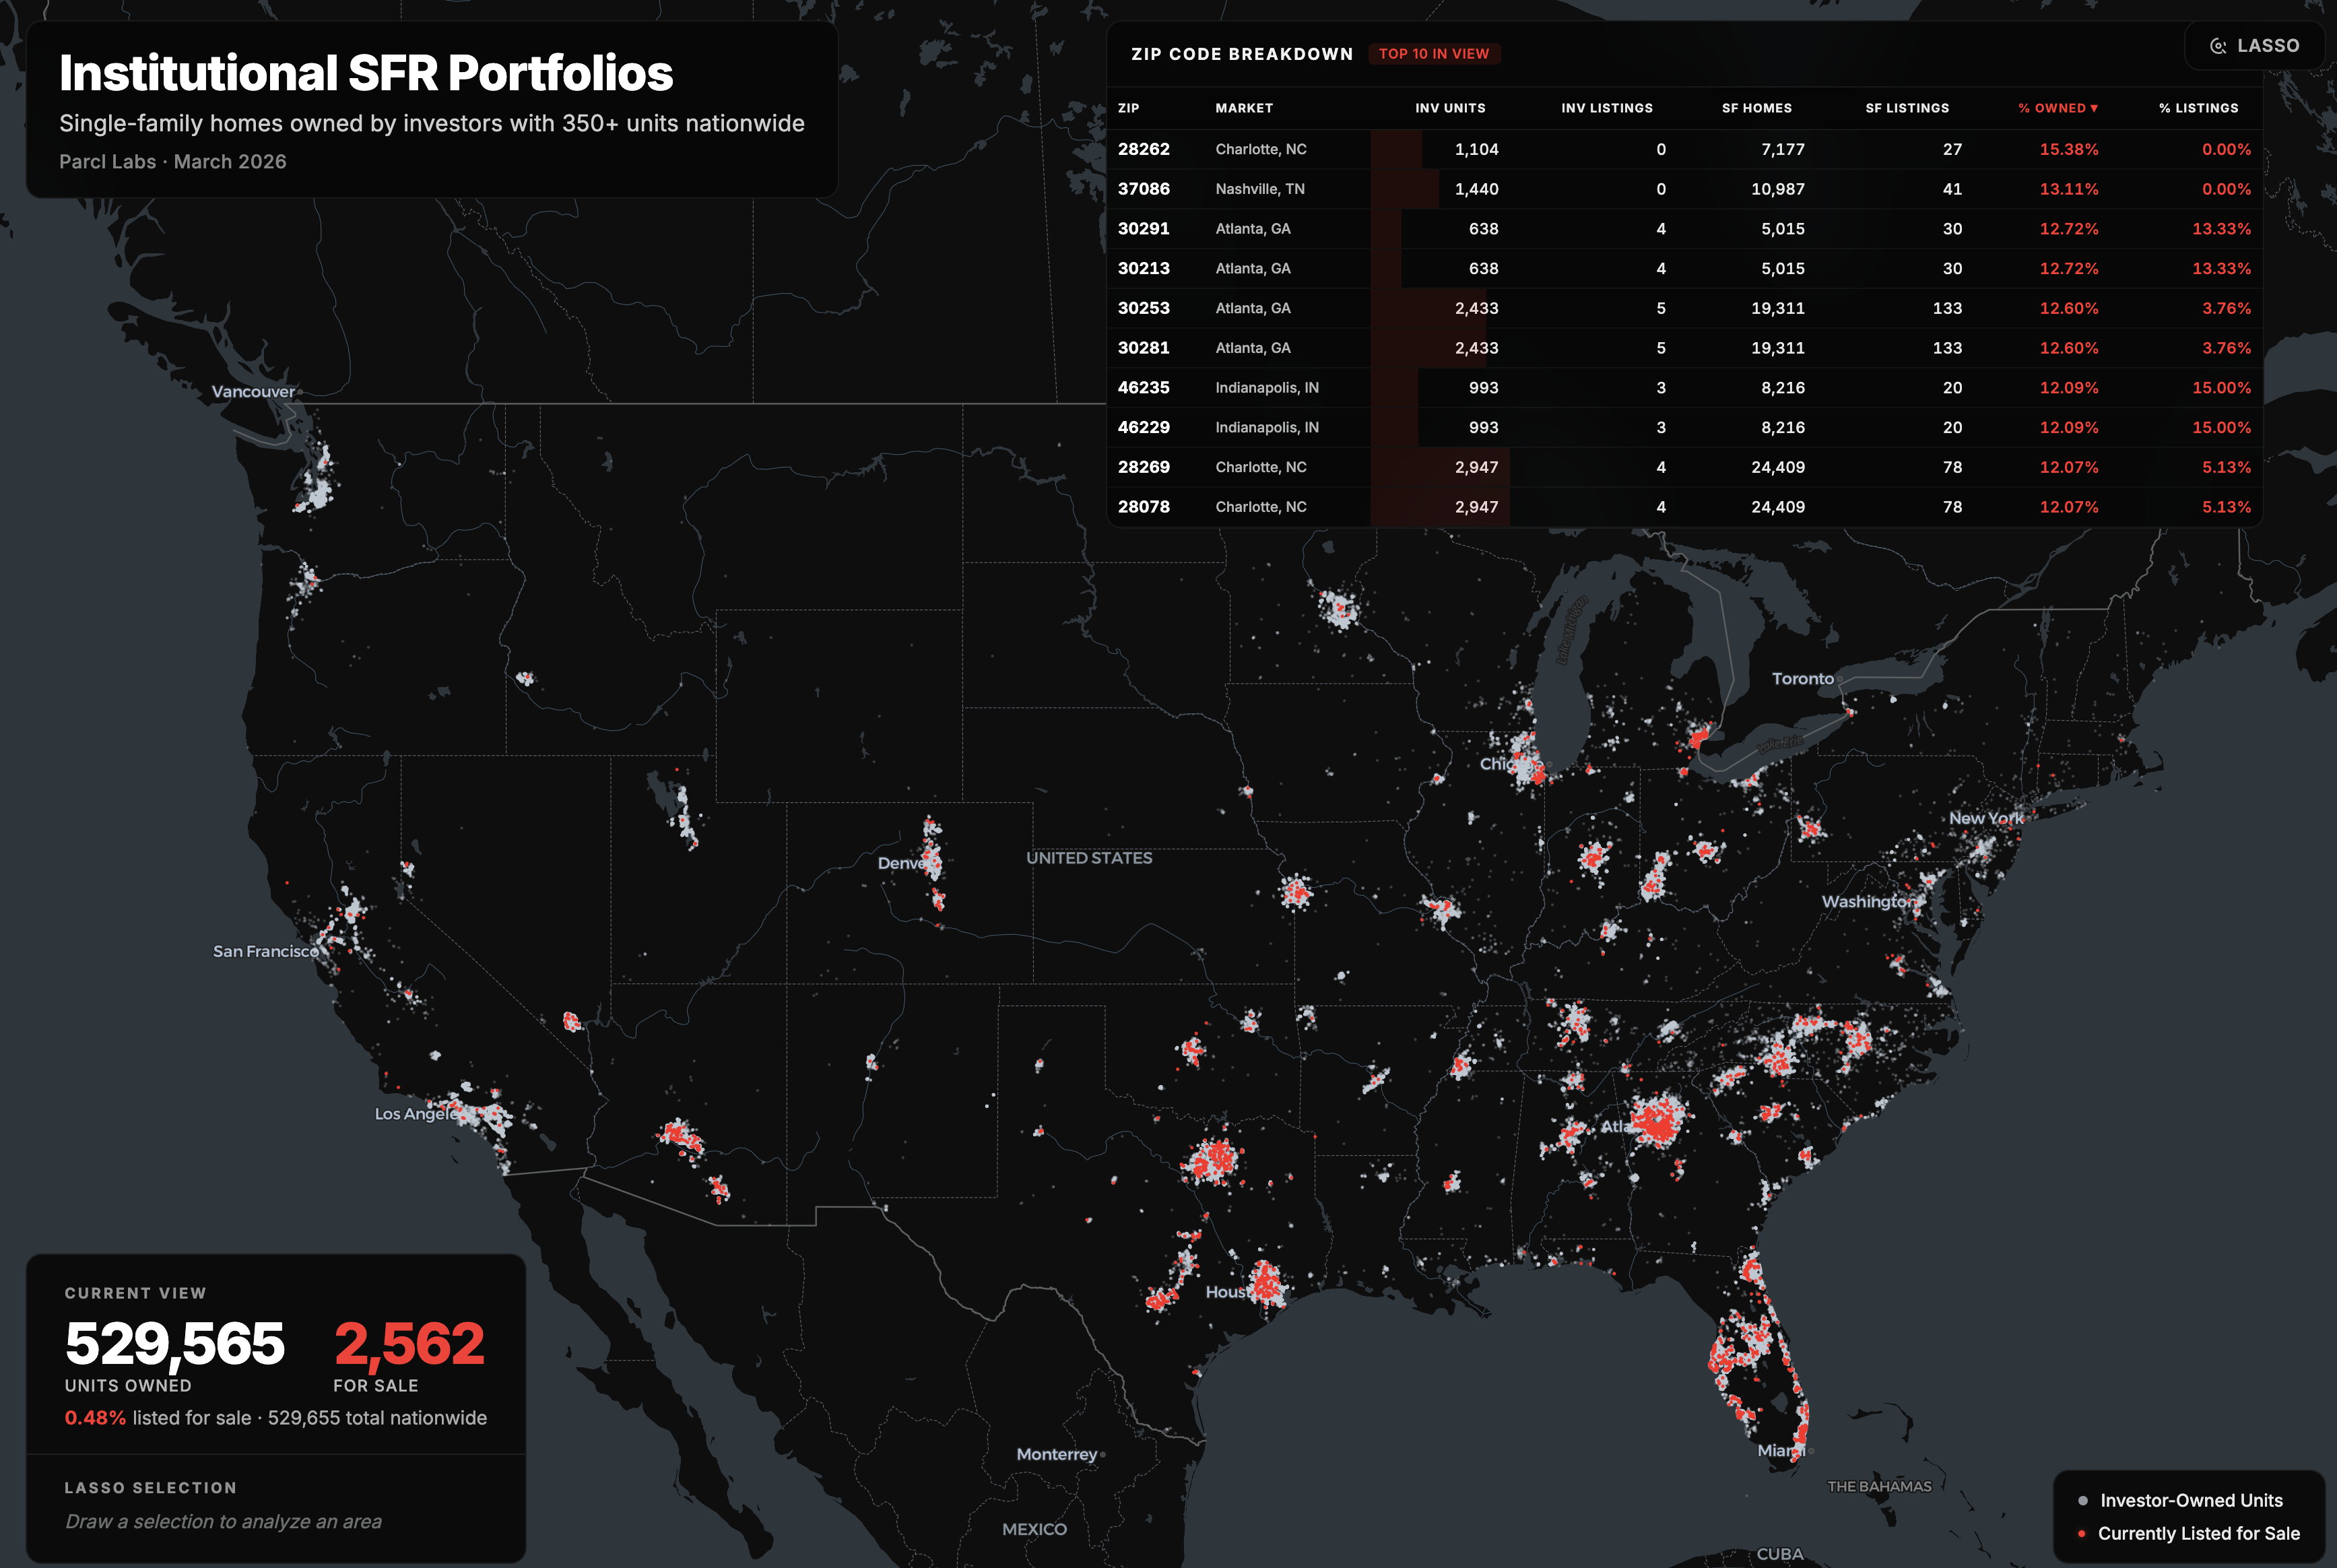
The map plots all 530,000 properties. Grey dots are 350+ investor-owned homes. Red dots are their homes currently listed for sale, 2,562 as of early March 2026. The table in the upper right breaks out the top 10 zip codes by ownership concentration.
At the national level, less than 1 in 170 single-family homes falls under the bill's scope. But these operators did not spread their portfolios evenly. They concentrate in specific markets, and the concentration is where the bill's potential impact becomes real.
350+ Investors Concentrate in the Sun Belt
We ranked the top 100 metros by the number of homes owned by 350+ investors, then computed each market's concentration: the share of local single-family housing stock those 350+ investors control. The top 30 metros by unit count hold 433,020 properties, 82% of all 350+ institutional homes nationwide.
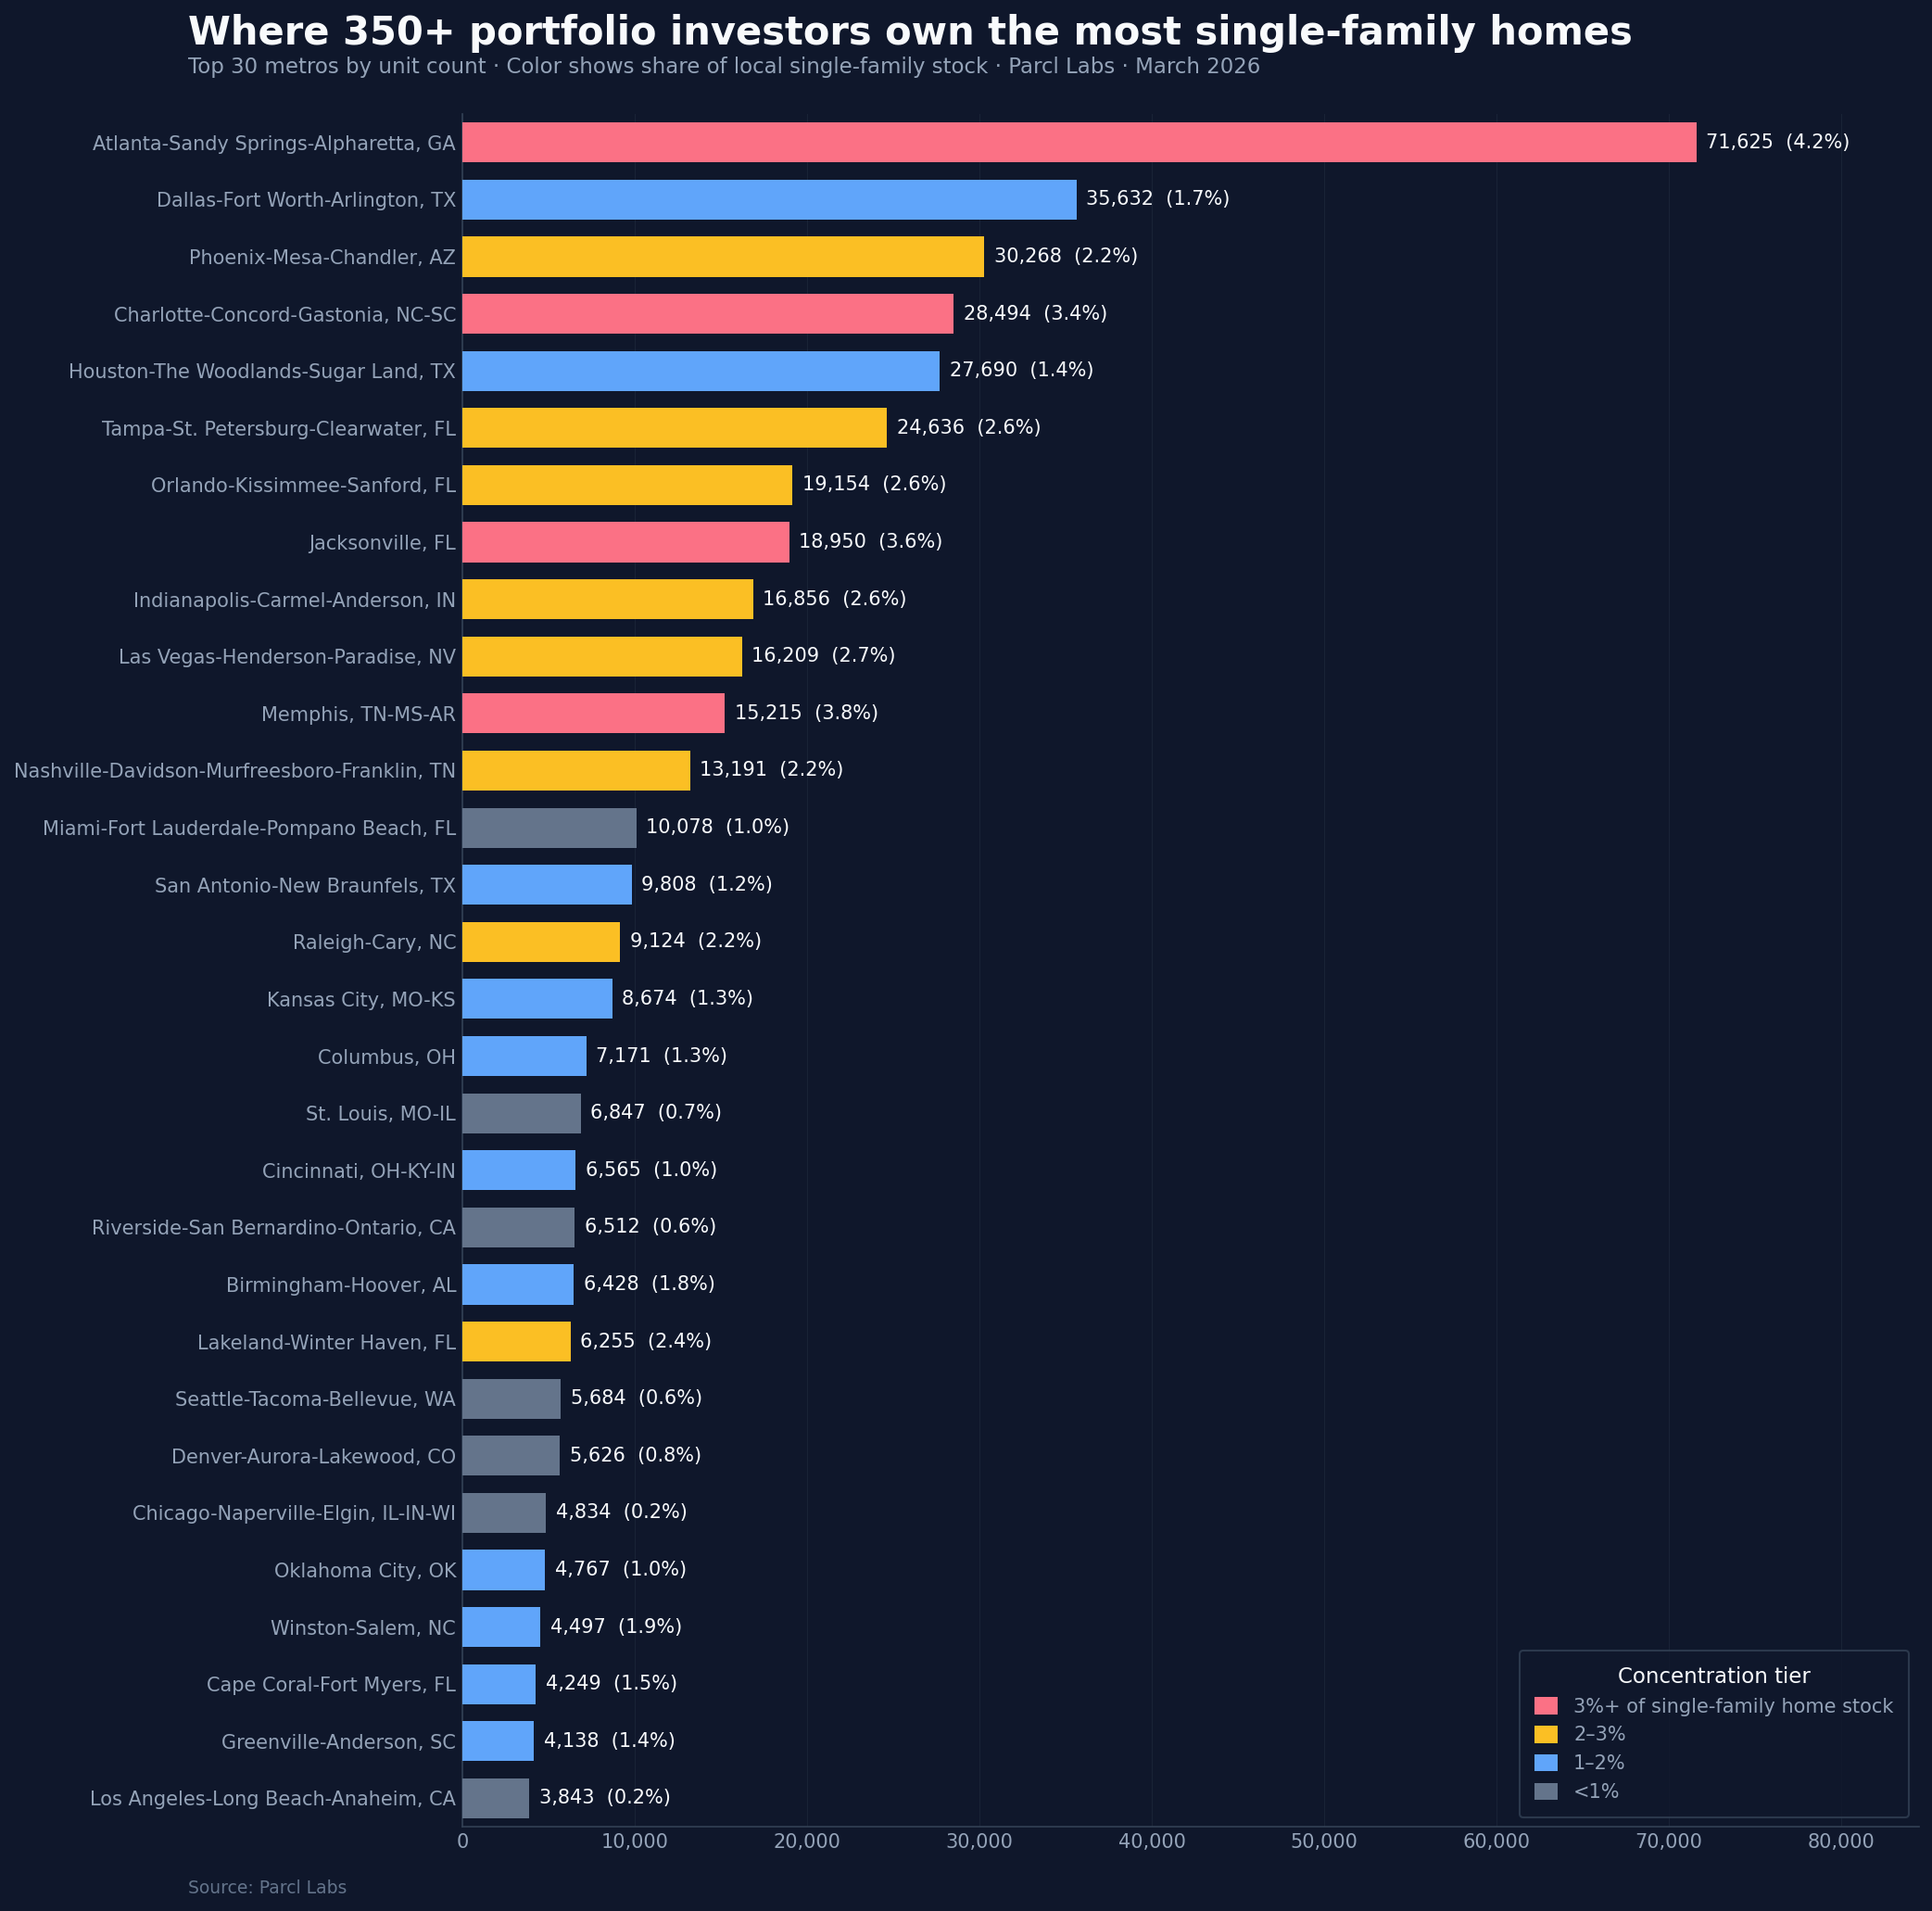
The regional divergence is sharp. The coasts and the Northeast are nearly absent from the rankings. Only three West Coast metros make the top 30 by count - Riverside, Seattle, and Los Angeles - all below 1% concentration. The Northeast does not appear at all. High home prices and large housing stock insulate these regions from meaningful institutional SFR penetration and therefore the impact of this bill.
The Sun Belt tells a different story. Twenty of the top 30 metros are Sun Belt, with Florida carrying the heaviest state-level exposure across six metros led by Jacksonville at 3.60%. A Southeast corridor extends from Atlanta through Charlotte, Raleigh, Nashville, Memphis, and Birmingham. A secondary Midwest cluster runs through Indianapolis, Kansas City, Columbus, Cincinnati, and St. Louis.
One market separates from the rest. Atlanta leads on both unit count and concentration, and by wide margins. It is also where the consequences of that concentration are already playing out on the ground.
Atlanta: The Epicenter of 350+ Concentration
Parcl Labs has been tracking Atlanta's investor dynamics for three years, beginning with our original Atlanta Alarm research. Each subsequent analysis has reinforced the same finding: Atlanta is where institutional SFR ownership is most concentrated, and where the consequences of that concentration surface first.
Our recent investor selling analysis put Atlanta firmly on the radar. Atlanta has the sharpest purchase-to-sale decline among major metros, a 0.58 ratio, meaning investors there sell nearly two homes for every one they acquire.
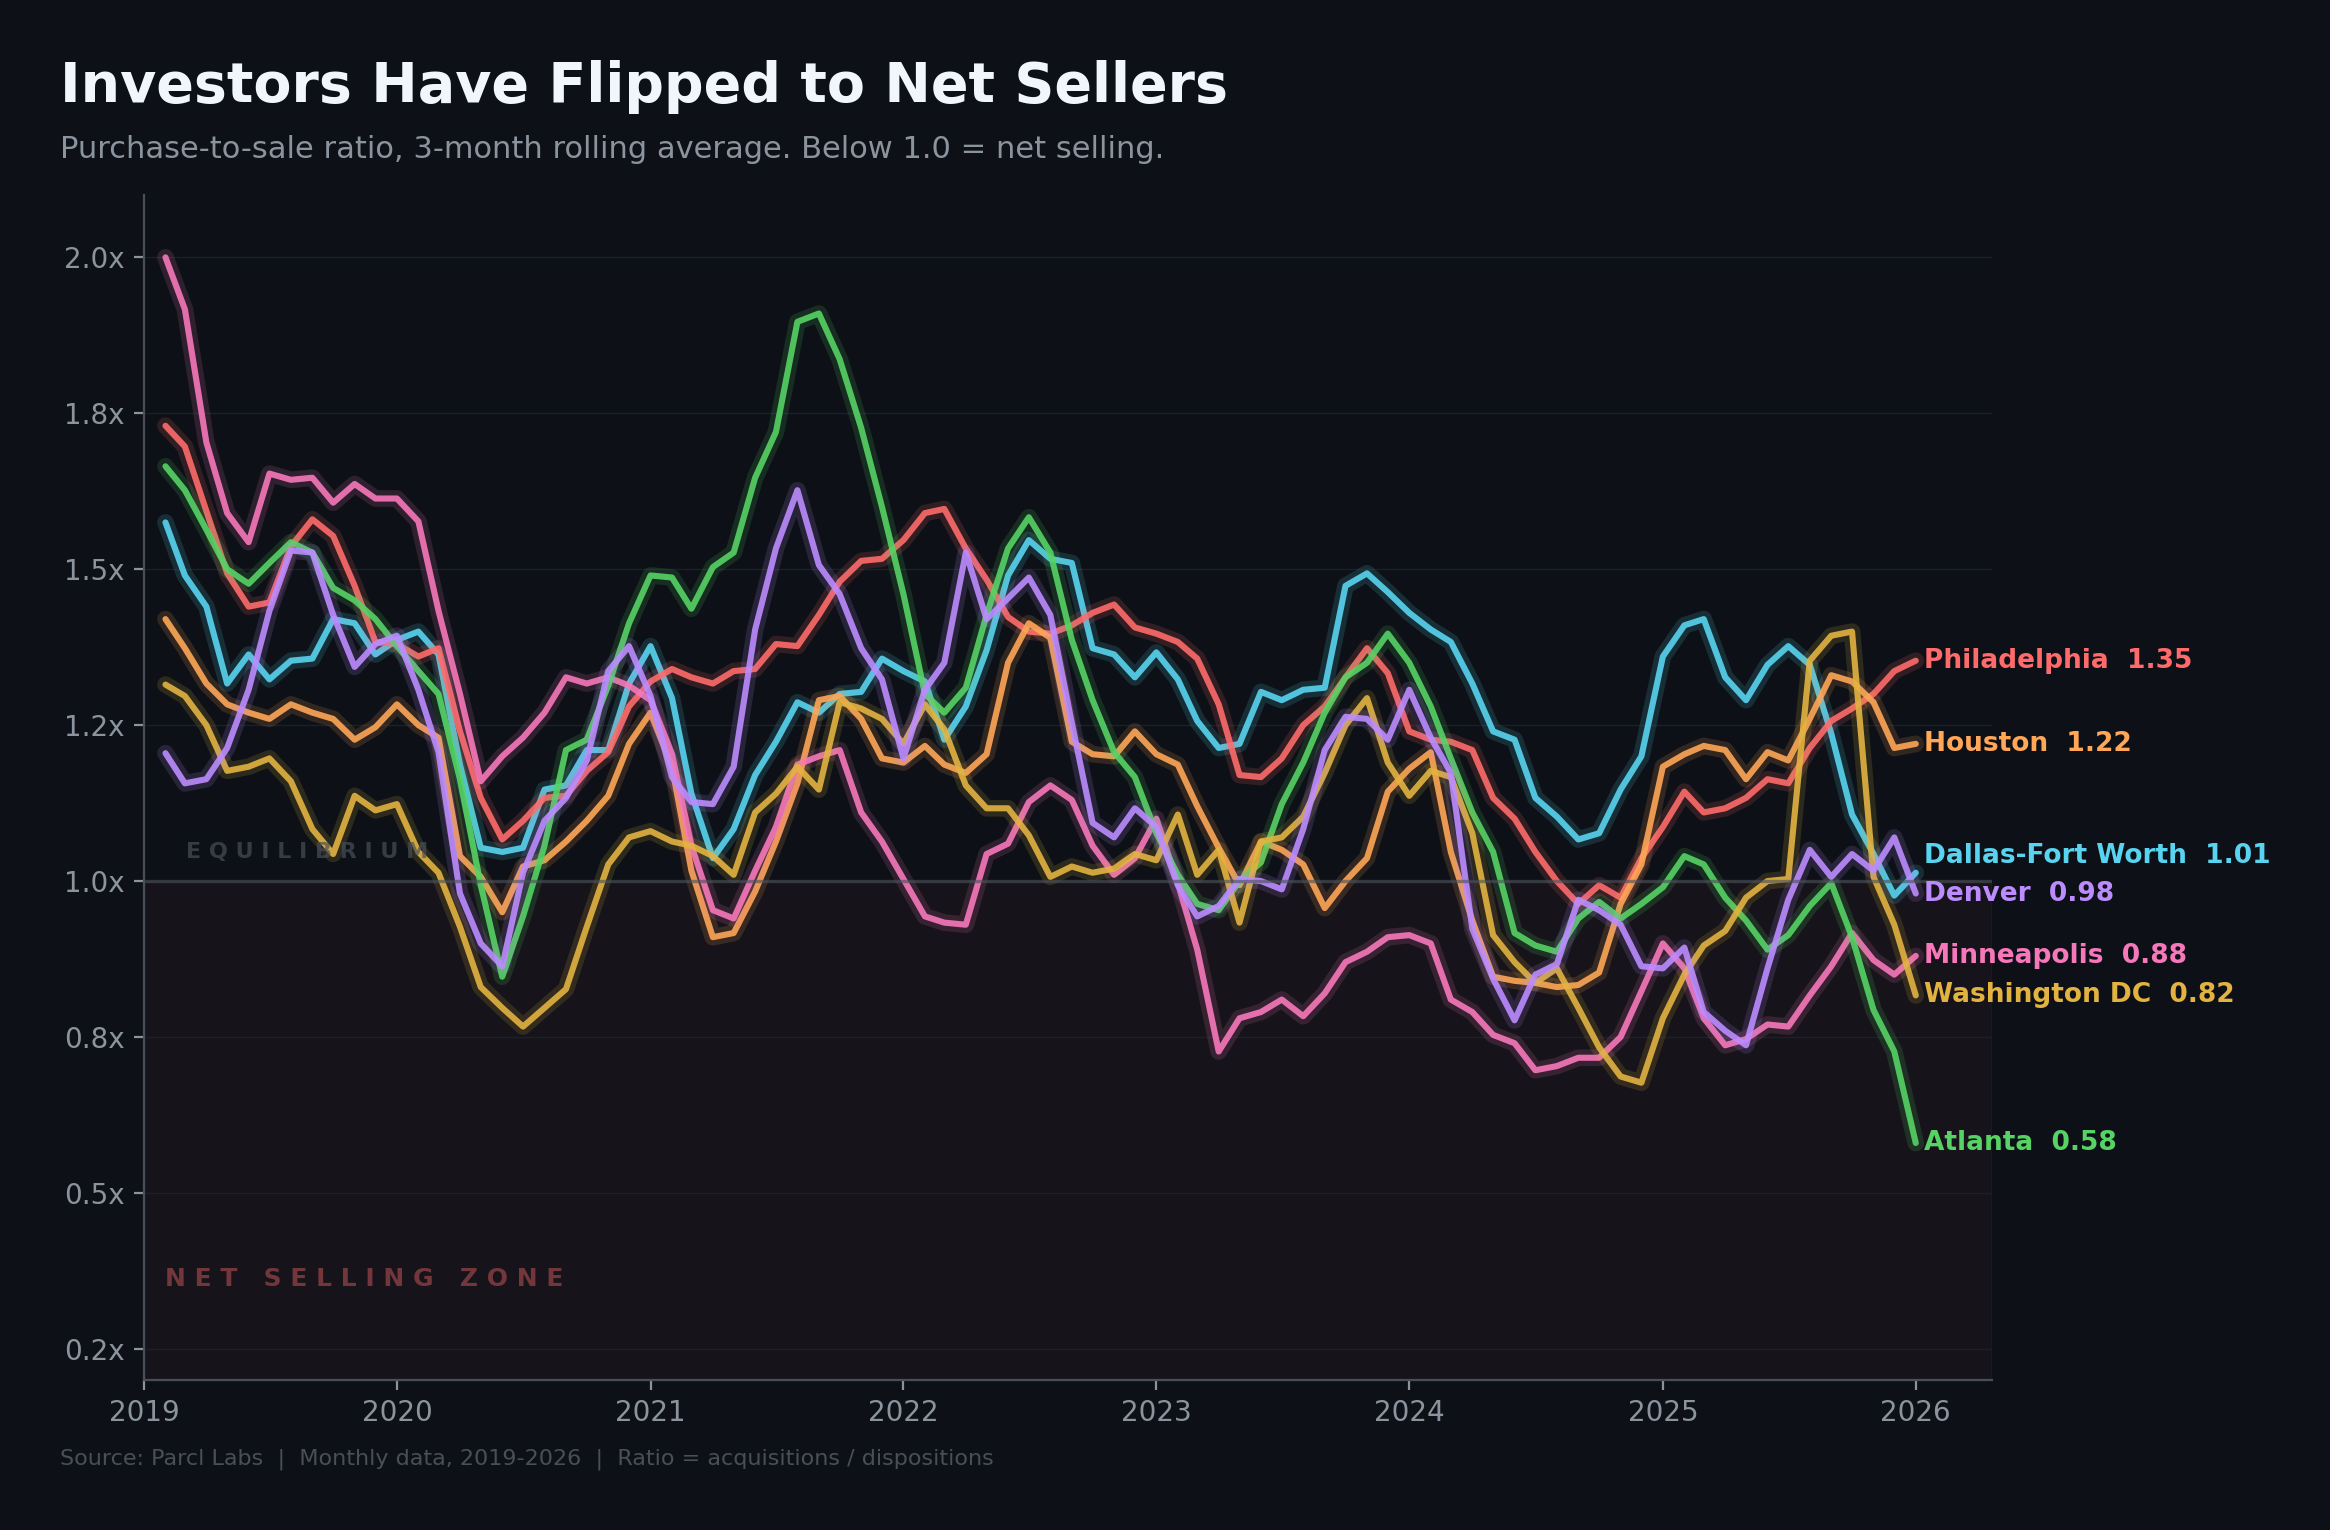
That research examined investors as a broad cohort. The 350+ analysis narrows the lens to the specific group the bill targets, and Atlanta is their epicenter.
Four of the Top 10 National Zips Are in Atlanta
Four of the top 10 zip codes nationally for 350+ ownership are in metro Atlanta. In these zips, 350+ investors own 12% or more of total single-family housing stock.
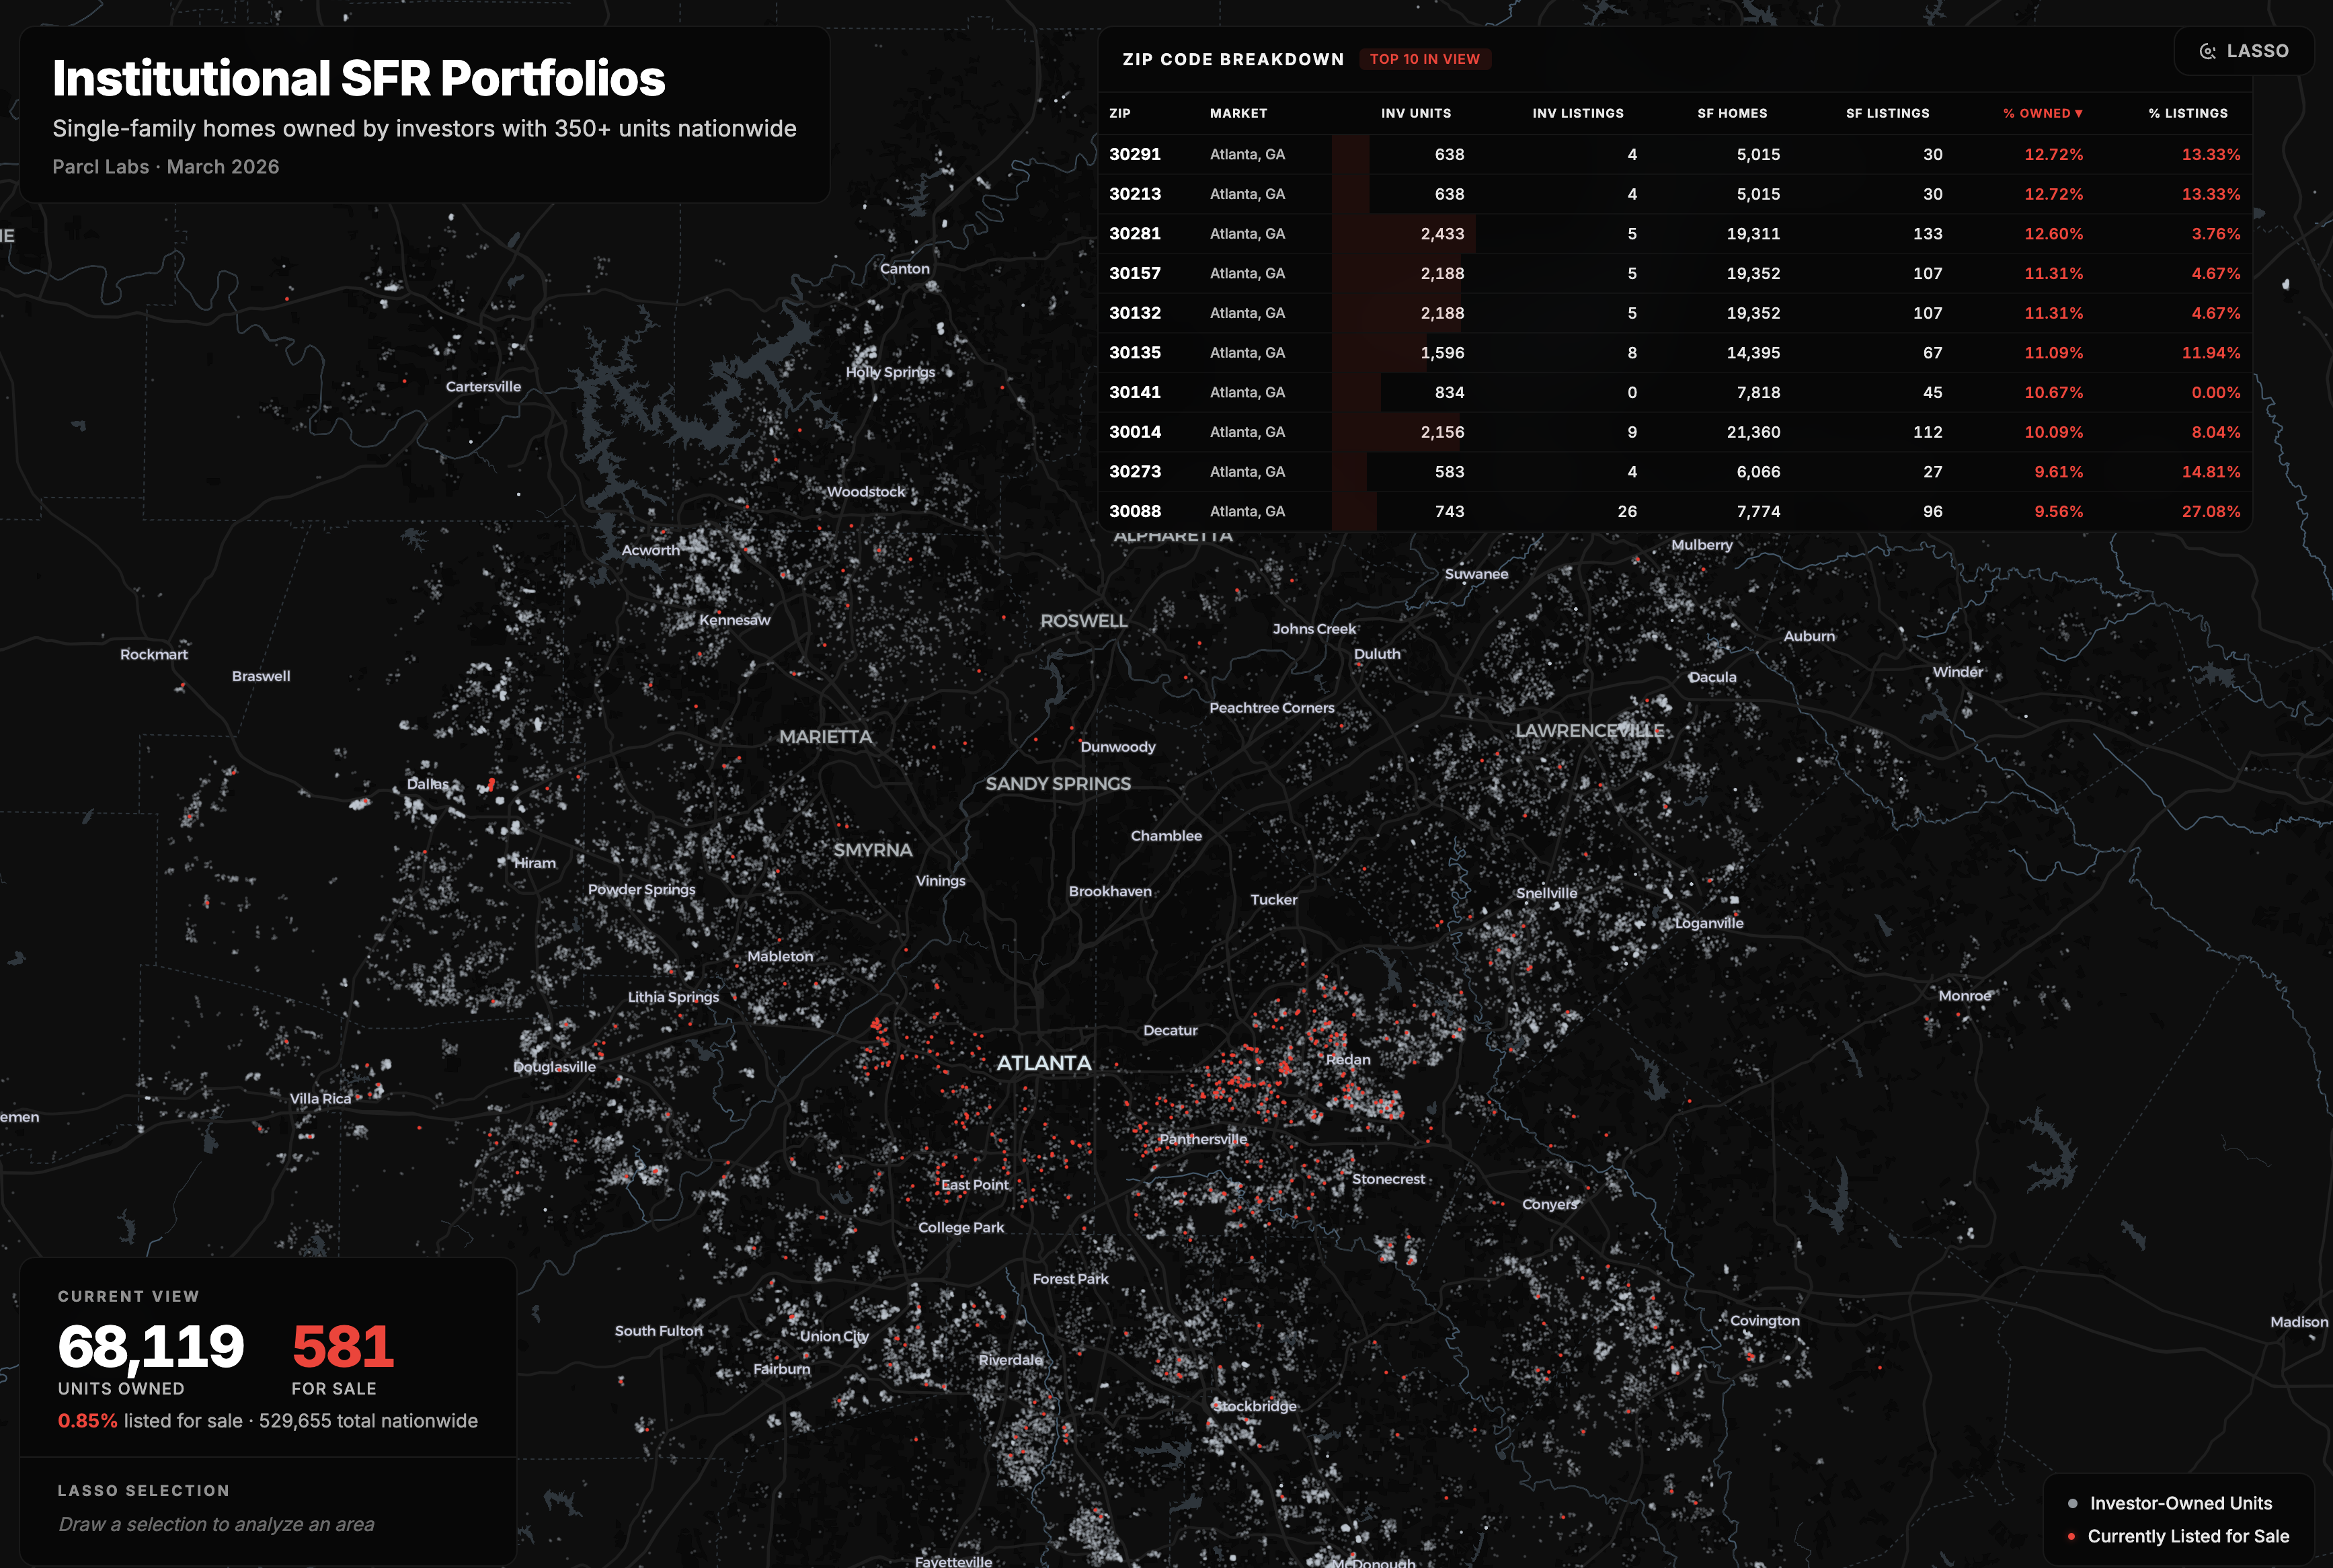
Zooming into the Atlanta metro, the map above shows a subset of 68,119 investor-owned units in the visible area, with 581 currently listed for sale. The table breaks out the top 10 Atlanta zips where these investors hold between 8% and 13% of all single-family homes. Eight Atlanta zip codes have 350+ investors owning more than 1 in 10 homes.
1 in 4 Homes for Sale in South Atlanta's Concentrated Zips
The for-sale activity from 350+ investors is heaviest in the same areas where ownership concentration is highest: the south and southeast suburbs.
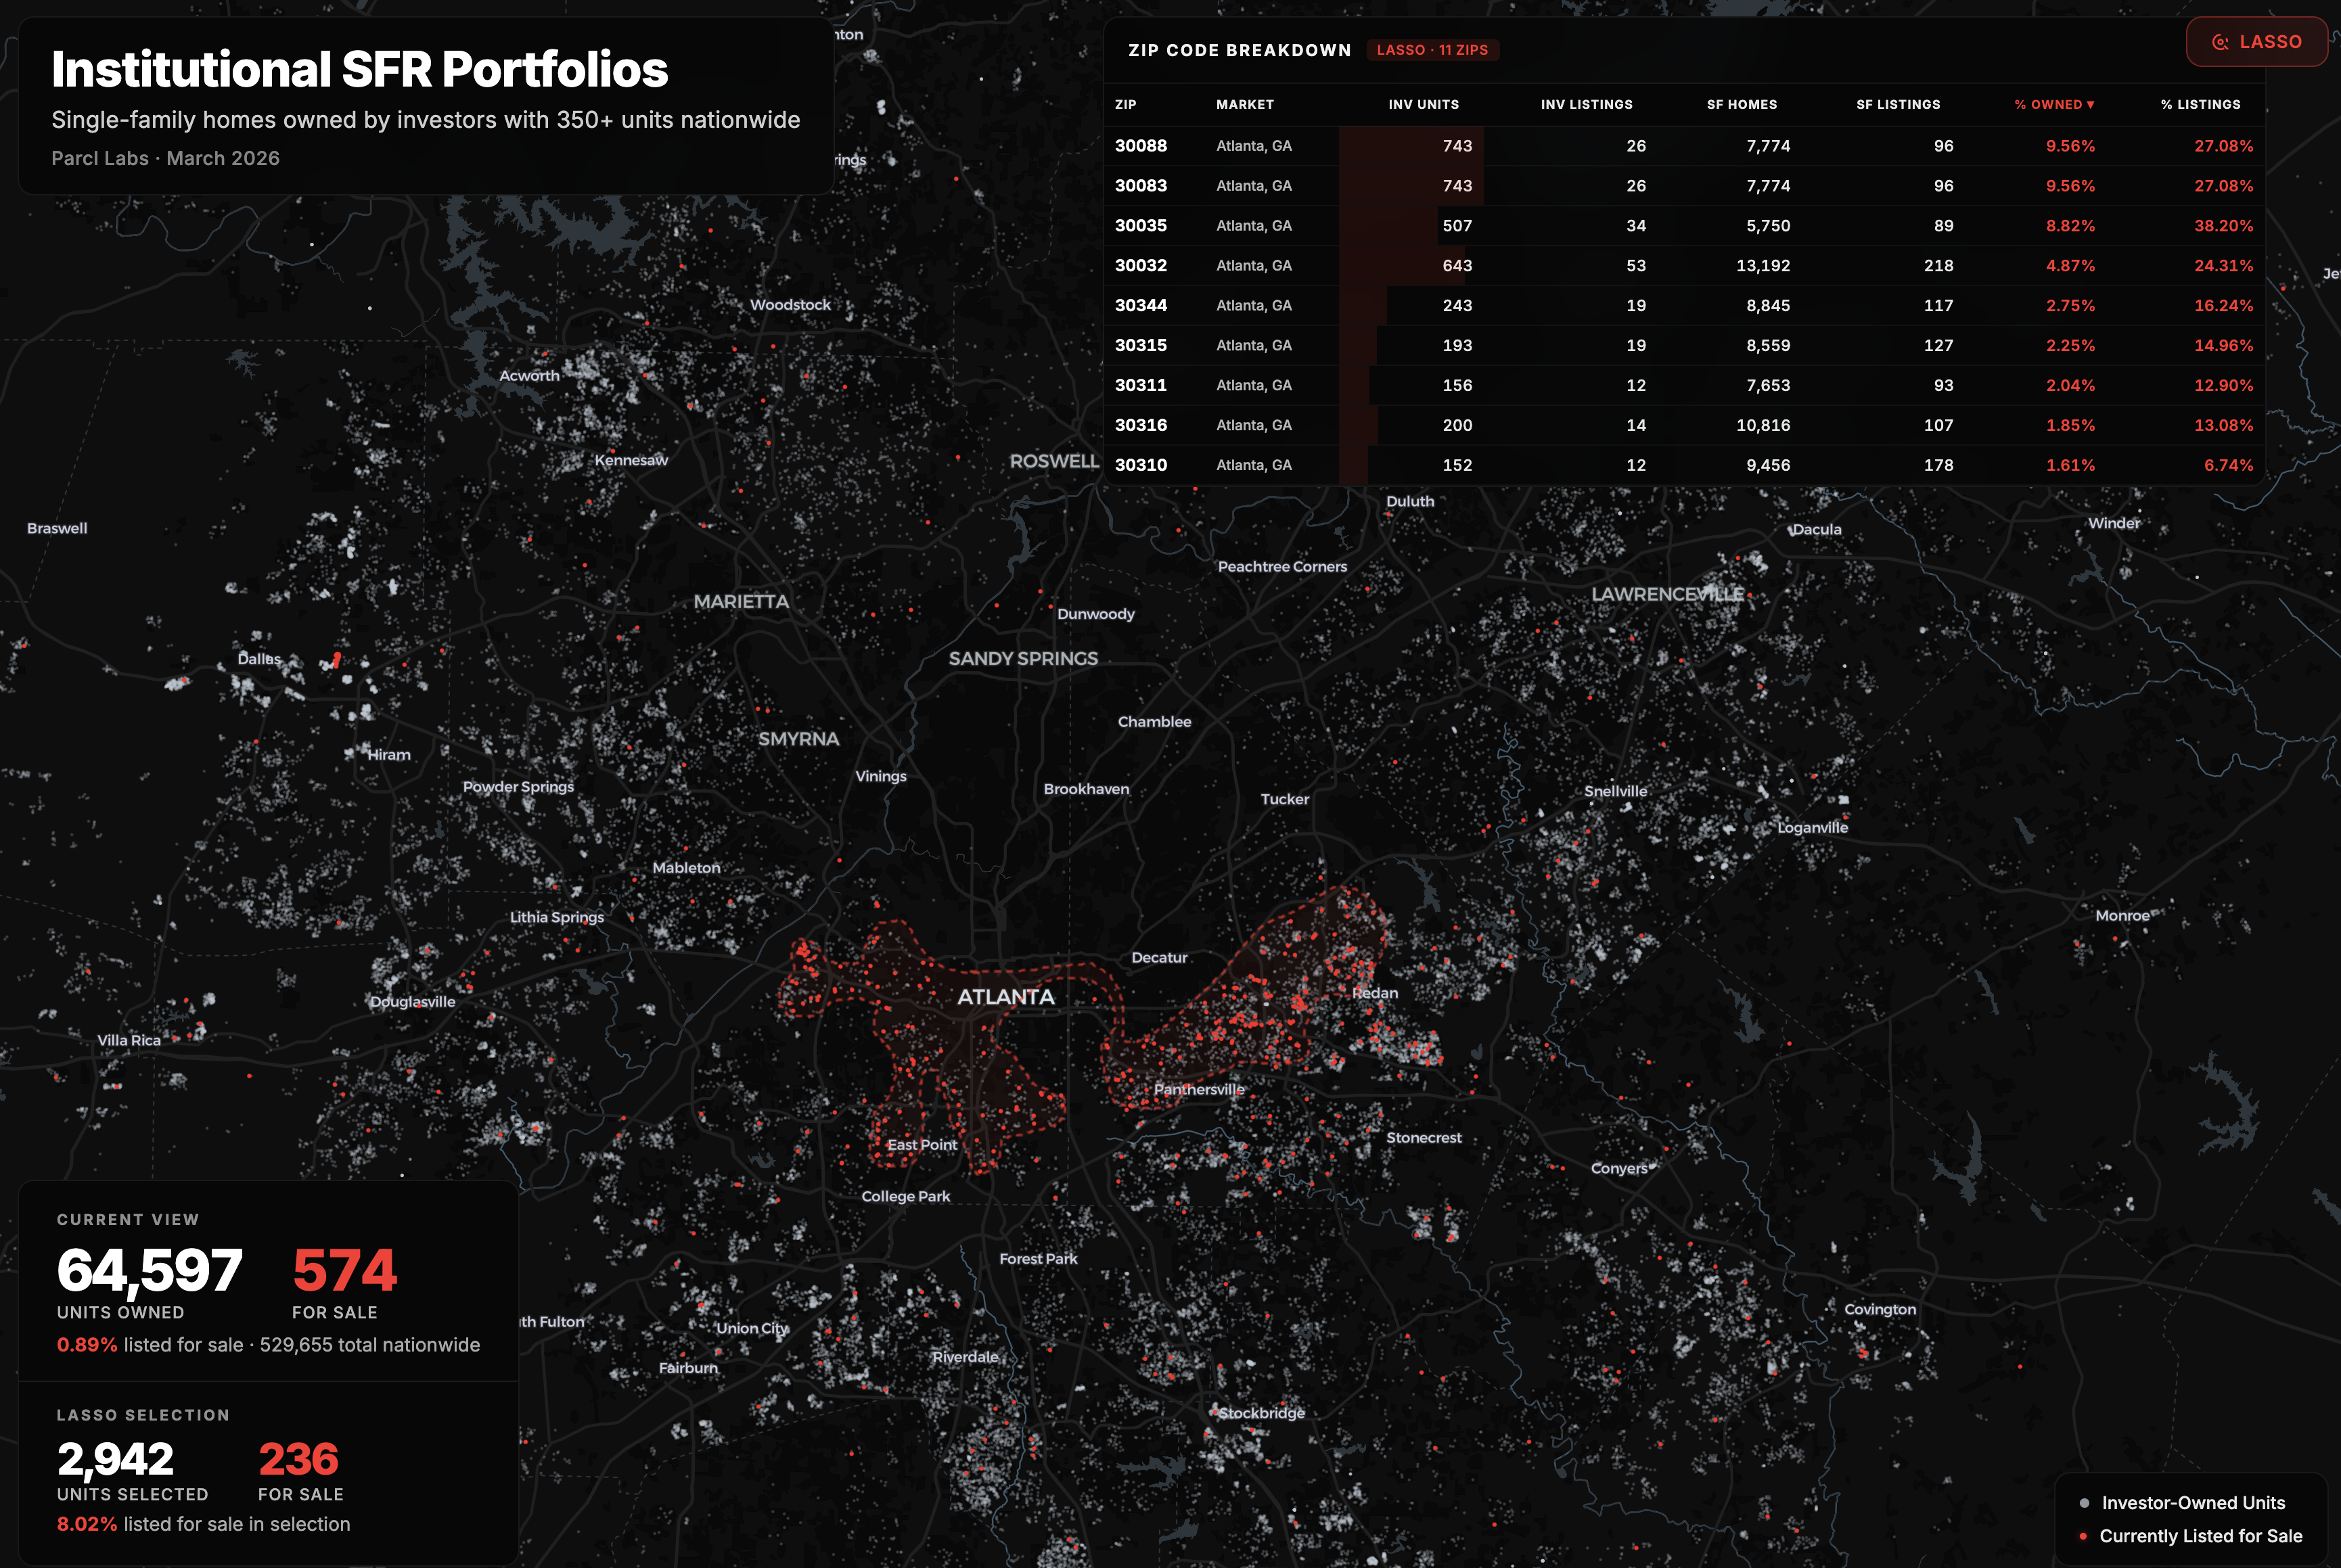
When we isolate that area (the outlined region on the map), 2,942 investor-owned properties fall inside the boundary. Of those, 236 are listed for sale, an 8.02% listing rate. In four zip codes within this selection, 350+ investors now account for 25% or more of the entire for-sale supply. One in four homes on the market in these neighborhoods is being sold by an institutional operator.
Ownership and for-sale activity at this level of concentration carries risk. Institutional operators do not sell the way individual homeowners do. They make portfolio-level decisions on different incentive structures and time horizons. When they become motivated sellers, their activity is coordinated. In zip codes where they own 1 in 10 homes and represent 1 in 4 listings, a concentrated sell-off can materially move local prices, as we documented with Vinebrook, where a single operator's exit pulled comps down across entire zip codes.
The bill aims to reduce this concentration. Whether that reduction benefits everyday homebuyers is a separate question, and one the data can begin to answer.
Large Investors Are Already Selling. Many Homes Aren't Reaching Homebuyers.
The bill's stated goal is to expand homeownership for everyday Americans. The underlying assumption is that restricting institutional acquisitions and motivating dispositions will free up homes for qualified buyers.
We tested that assumption against the data.
1,000+ Portfolios Are Selling. Mom-and-Pops Are Buying
Investor purchase volume alone is misleading. The best measure is net activity: acquisitions minus dispositions. The net effect reveals whether investors are expanding or contracting their presence in a market.
The 1,000+ unit portfolio cohort has been a net seller since early 2023. These are the operators most directly impacted by the 350-unit threshold. Between March 2024 and January 2026, 1,000+ portfolios shed approximately 4,010 net units. Mid-size portfolios (100-999 units) followed a similar path, down 2,246 net units over the same period.
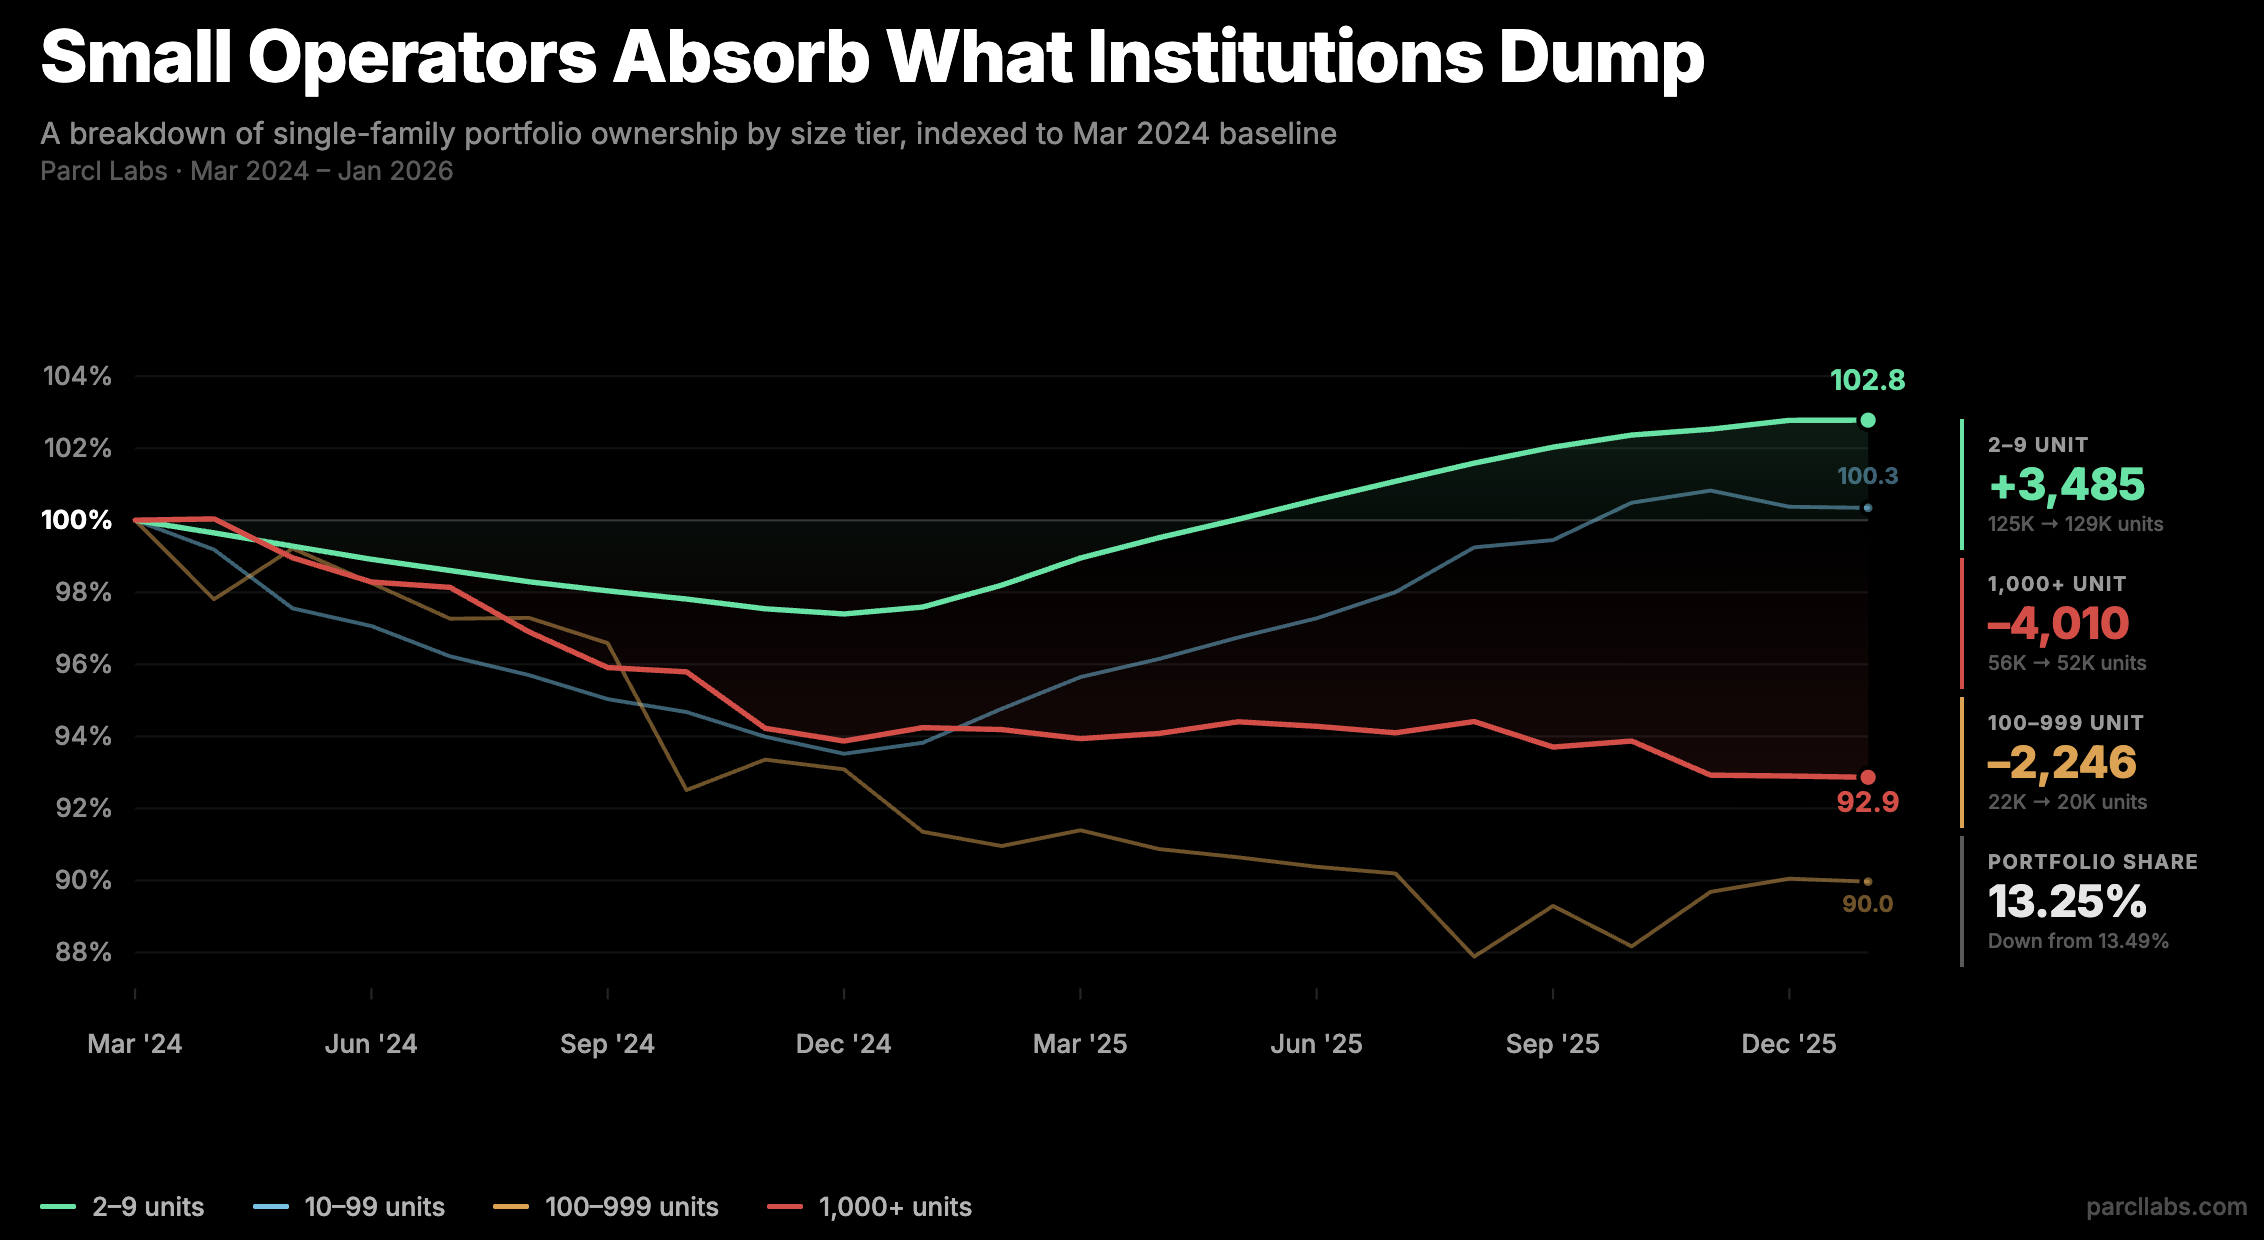
As the largest portfolios contracted, smaller ones grew. 2-9 unit portfolios added 3,485 units during the same period, reaching 102.8% of their March 2024 baseline. The small mom-and-pop operators driving that growth are untouched by the bill's 350-unit threshold.
Investor-to-Investor Sales Are On The Rise
Many large investors above the 350-unit threshold are already net sellers. The critical question is what happens when they dispose of homes: do those properties reach qualified homebuyers, or do they recirculate within the investor ecosystem?
To answer that, we looked at every U.S. home sale from 2005 through early 2026, broken down by buyer-seller type: investor-to-investor, investor-to-owner-occupant, owner-occupant-to-investor, and owner-occupant-to-owner-occupant.
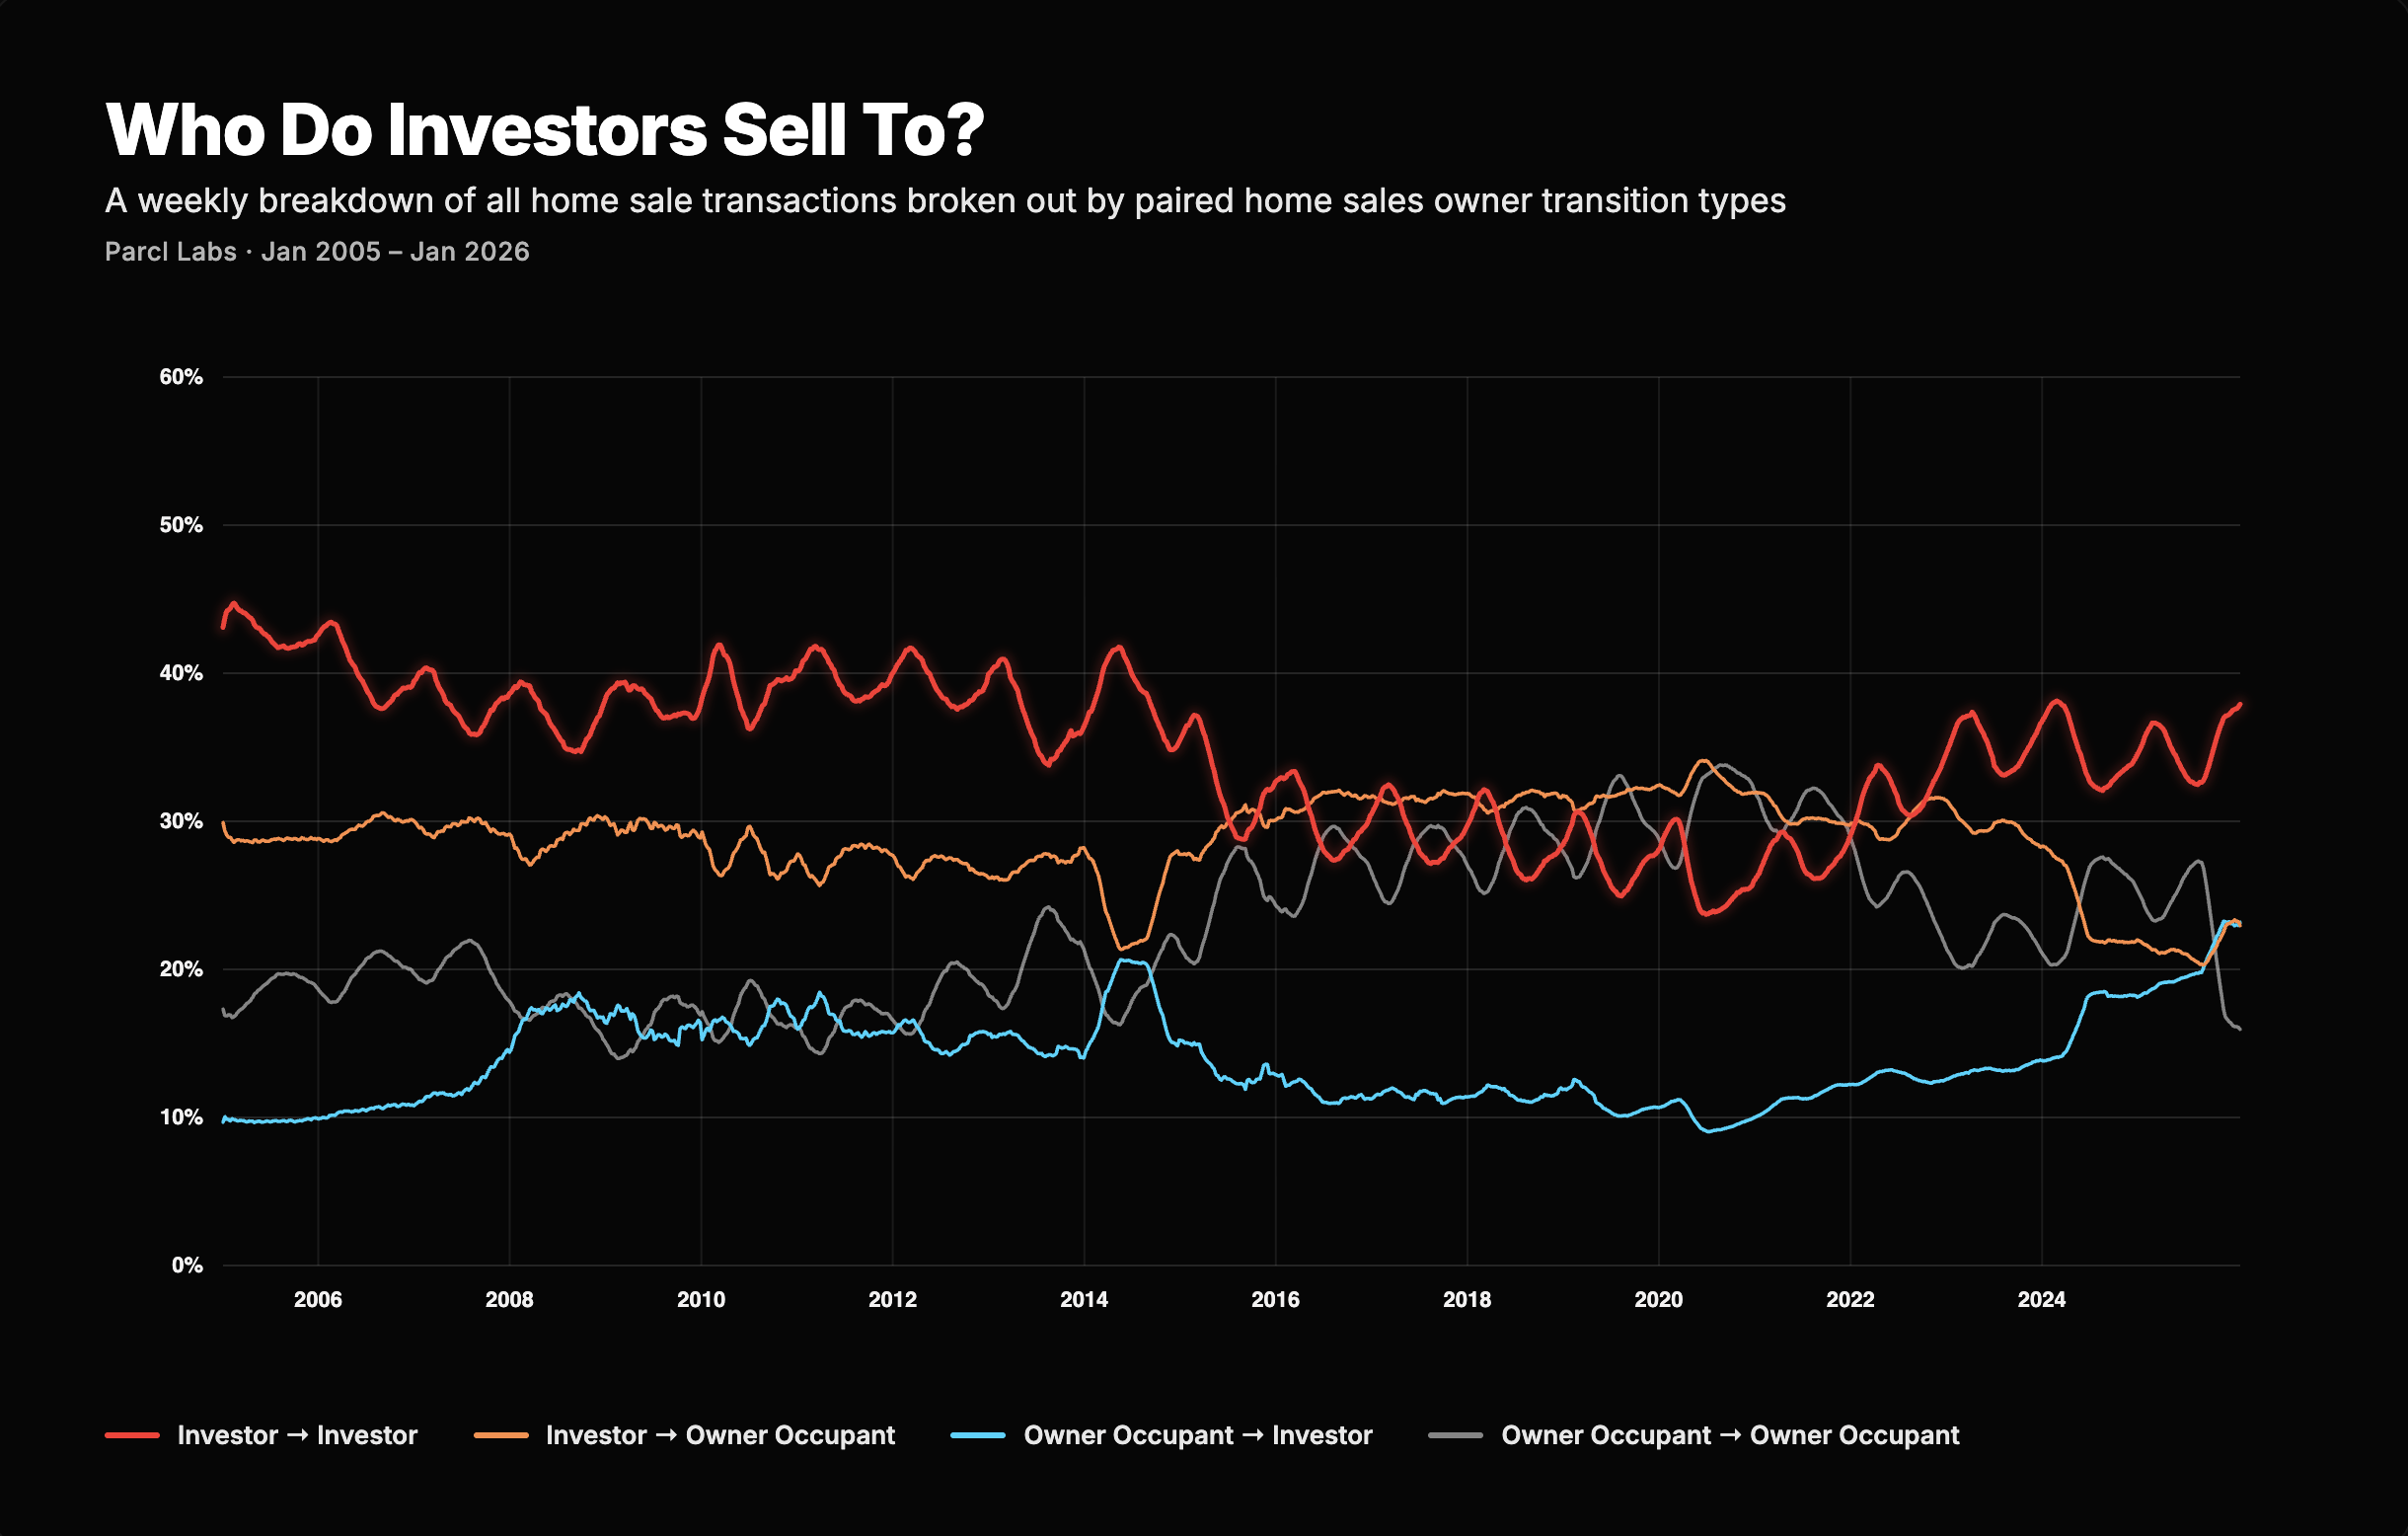
Two trend lines stand out. Investor-to-investor transactions have risen steadily, climbing from roughly 27% of all home sales in 2019 to 37-39% by late 2025. Investor-to-owner-occupant transactions moved the opposite direction, falling from about 32% in 2019 to 20-23% over the same period. Investors are increasingly trading homes with each other, and fewer investor-held homes are reaching owner-occupants than at any point in the past two decades.
The logic behind the bill, that removing the largest institutional buyers creates better opportunities for regular homebuyers, does not account for this dynamic. When a large institution lists a home, the most likely buyer today is not a first-time homebuyer. It is another investor.
Regulation could change that calculus over time, but the bill's 350-unit threshold captures only a fraction of the investor universe. Small and mid-size portfolio investors, the cohort that makes up the vast majority of investor-owned housing, are not addressed by this legislation.
How to Track What Happens Next
The 350+ threshold created a new category of investor overnight. The entities captured by this bill, their portfolios, their selling behavior, and the markets where they're concentrated will be tracked closely by operators, buyers, policymakers, and media for the foreseeable future. Parcl Labs built the infrastructure to do it.
: The 140 entities identified in this analysis are all searchable in Portfolio Hunter, down to every property they own, every listing they've posted, and the brokers handling each disposition. Track how 350+ portfolios respond to this legislation in real time.
: The ownership insights, transaction, listing, and concentration data behind every chart in this piece is available via API and our data download platform. Build your own analysis on the same foundation.
: Query the full Parcl Labs dataset in natural language. Ask it which 350+ investors are net selling in a specific metro, how concentration has shifted quarter over quarter, or what percentage of institutional dispositions are reaching owner-occupants. The answers update as the data does.
The policy environment will keep moving. So will investor behavior. The data to follow both is here.
Methodology
Parcl Labs generated all data, analysis, and research cited in this article.
Entity Identification and Classification: Investors meeting the 350-unit threshold were identified using Parcl Labs' true owner resolution technology, which maps individual LLCs and subsidiaries to parent entities and classifies each owner's business model based on observed property-level activity (rental listings, holding periods, acquisition patterns, new construction activity). Government entities, homebuilders, nonprofits, and other holders not operating as institutional SFR platforms were excluded.
MSA Concentration Analysis: For the top 100 metros by institutional unit count, we computed concentration as the share of single-family housing stock owned by 350+ portfolio investors. The numerator (institutional properties per MSA) was derived from property-level data grouped by MSA. The denominator (total single-family housing stock per MSA) was sourced from Parcl Labs' housing stock dataset as of January 2026.
Portfolio Ownership Tiers: Atlanta portfolio ownership by size tier (2-9, 10-99, 100-999, 1,000+ units) was tracked monthly from March 2024 through January 2026 using Parcl Labs portfolio metrics.
Housing Flows Analysis: National weekly breakdown of all U.S. home sale transactions by buyer-seller type (investor-to-investor, investor-to-owner-occupant, owner-occupant-to-investor, owner-occupant-to-owner-occupant) from January 2005 through early 2026, sourced from Parcl Labs transaction data.
Follow Us for More