
The ROAD Act Is Law: The Investors It Targets Continue to Sell
Jul 23, 2026 · 11 min read
The ROAD Act is now law. The investors it targets were already selling - and their for-sale inventory has doubled since March.
Executive Summary
The 21st Century ROAD to Housing Act became law on July 11, 2026. The law restricts future acquisitions by investors owning 350+ single-family homes.
Institutional for-sale listings have more than doubled since Congress introduced the 350-home acquisition ban in early March. The cohort had 4,668 active listings and $1.7B in aggregate asking value that week; on July 19 it had 9,586 and $3.1B, up 105% on count. Across the full February through July window, institutional listings grew 132% while the total market grew 49%, ~2.7x the market's pace.
Institutional sellers are actively working to clear their listings. Institutional Motivated Seller Index is 8.6 against 5.2 for the overall US market, and 56% of institutional listings carry a price cut. Cumulative markdowns on active institutional listings have grown from $56M to $129M.
Two institutional for-sale dynamics are playing out. In tertiary Midwest and Mid-South metros the selling is essentially one operator: VineBrook is 63–90% of institutional listings in Cincinnati, Dayton, Columbus, Jackson, St. Louis, and Memphis. Across traditional Sunbelt SFR markets, the broader cohort is trimming exposure: Atlanta leads with 1,234 institutional listings, followed by Tampa (569), Dallas (554), and Houston (393).
Atlanta is the market to watch. Institutional listings there have more than doubled from the March low, the segment's MSI has held above 9 (fire-sale) since early June.
Parcl is the only place to follow institutional for-sale activity in real time. Every chart in this note is a live view, refreshed daily, with the institutional cohort as a one-click lens to track what happens next.
The Investors the Law Captures Were Sellers Before It Existed
The 21st Century ROAD to Housing Act became law on July 11, 2026. It restricts future acquisitions by investors that own 350 or more single-family homes.
Parcl Labs' record on this institutional cohort predates the law. In Are Investors Heading for the Exits?, published February 26, we found that investor exits were already underway. The policy, we wrote, targets "a behavior that the market has been curtailing on its own for years."
When Congress introduced the 350-home definition in March, we mapped the investors it captures within hours. We published the results in The Housing Bill’s 350-Home Threshold: Who It Captures and What Comes Next.
That record is important because the prospect of an institutional investor "ban" fueled competing theories about what investors would do next - from a pre-deadline buying spree to a mass sell-off. Before Parcl, no one could test those theories against investor behavior in real time.
We resolve true owners and link them to daily for-sale activity. This capability allows us to track investor listings as they come to market and therefore surface future dispositions months before they close. Closed sales reflect decisions made months ago; listings capture decisions being made now.
Last month, we documented one major operator's ongoing portfolio sell-off in Fire Sale or Strategy. We now track the overall institutional cohort's (350+) for-sale activity daily on our live Motivated Seller map, the only place to follow this behavior live. CNBC's Property Play cited this data in its July 21 coverage, Wall Street is selling more rental homes, as buying ban takes effect.
The state map below shows the cohort’s current footprint in the for-sale market, measured as institutional listings’ share of each state’s active listings.
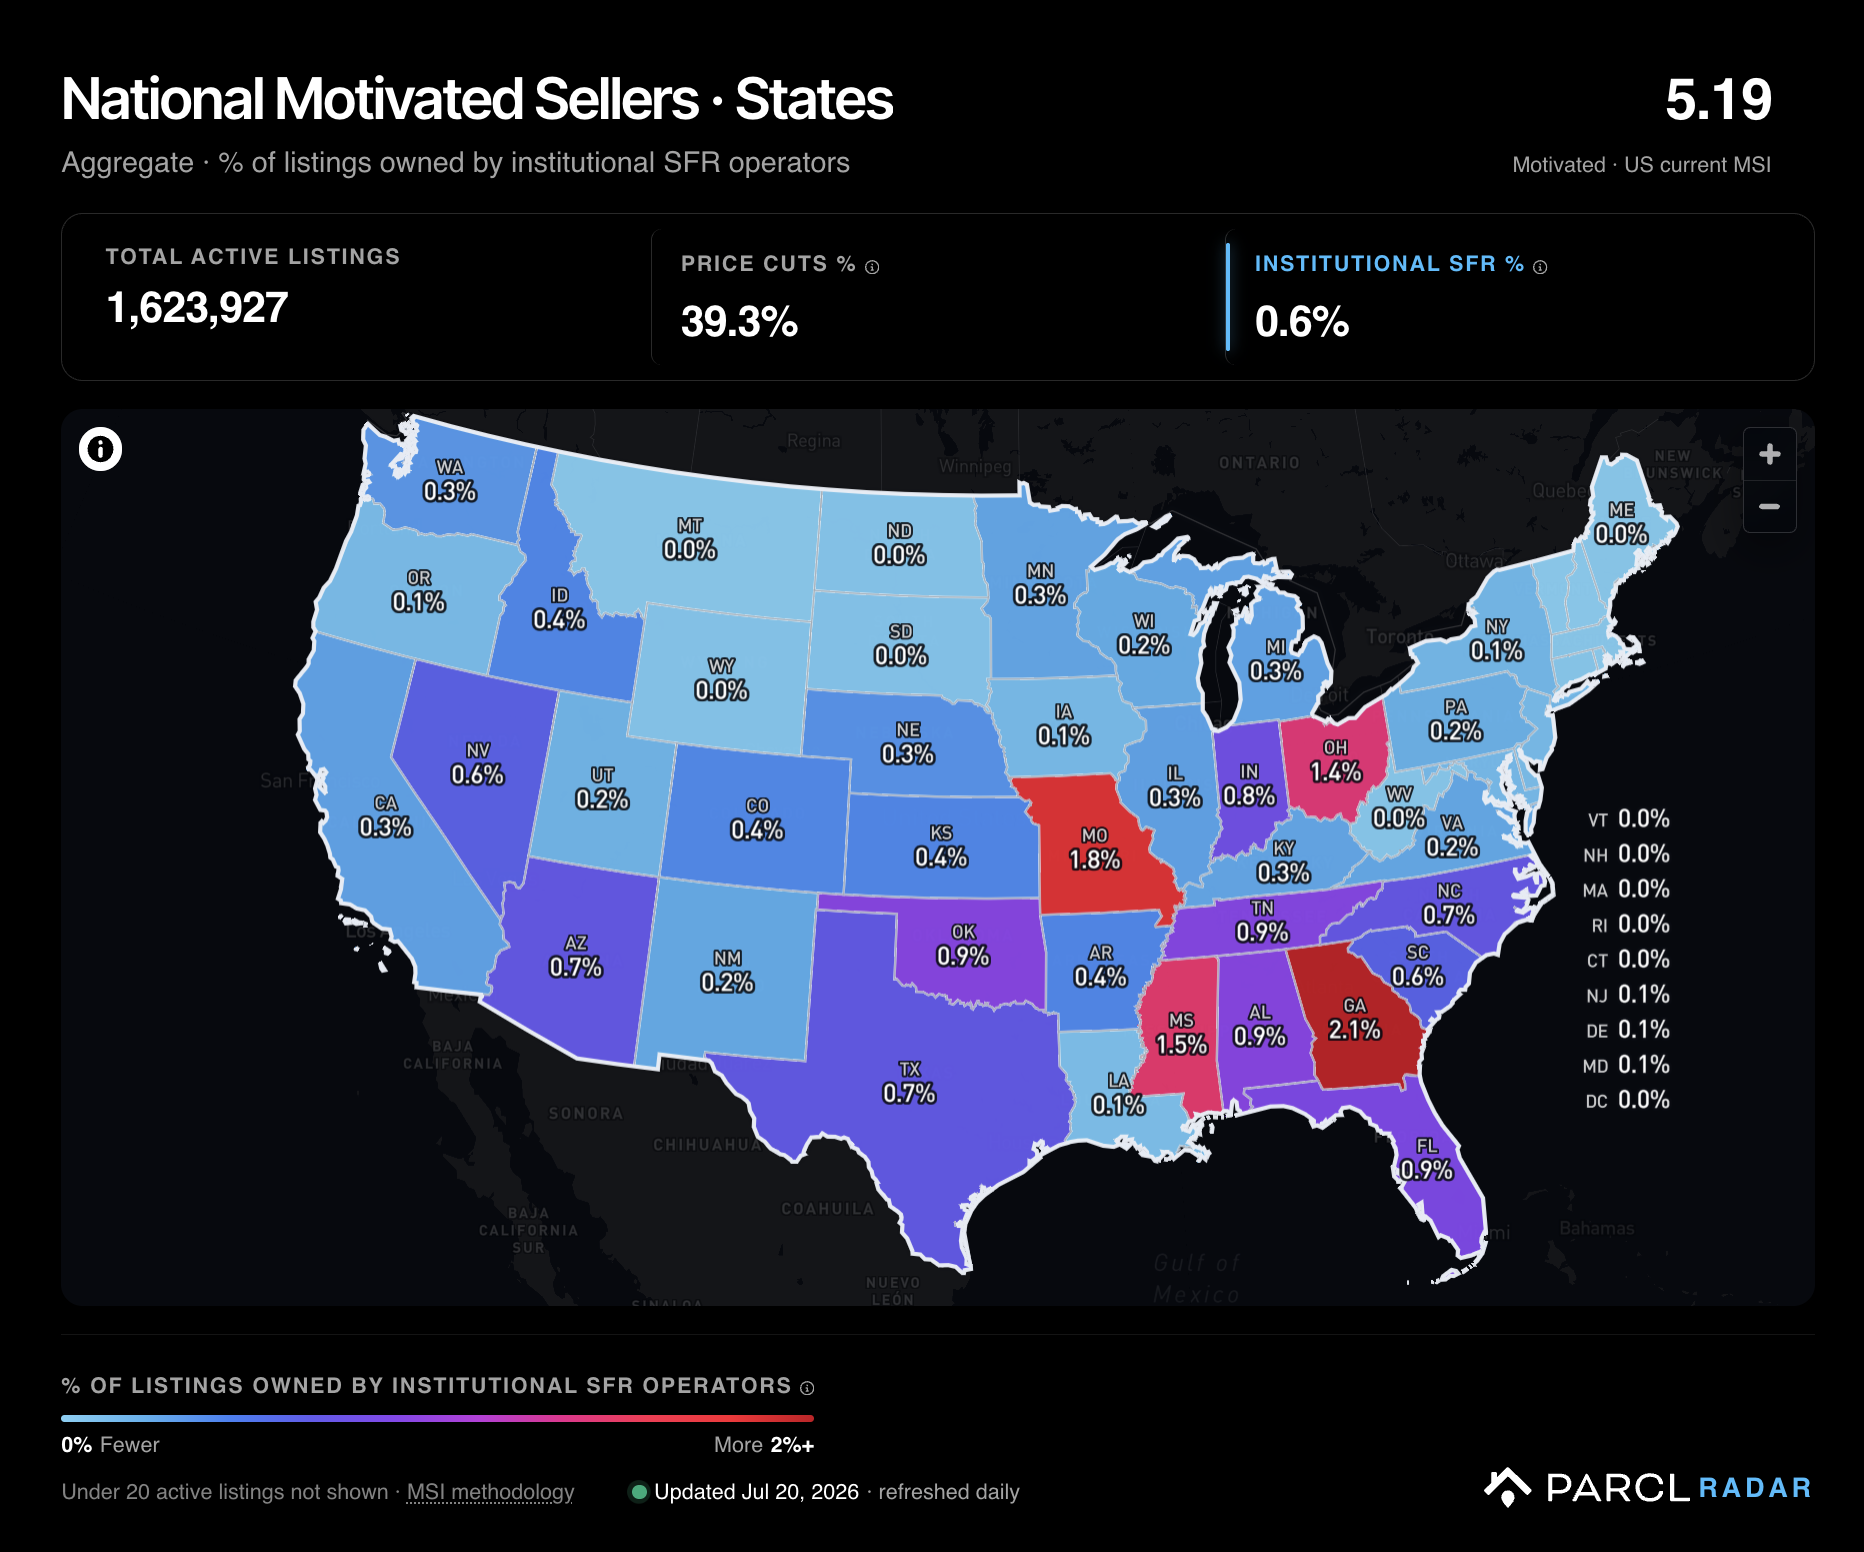
Georgia leads the country: institutional SFR operators account for 2.1% of the state’s active listings. Missouri follows at 1.8%, Mississippi at 1.5%, and Ohio at 1.4%.
Institutional For-Sale Inventory Has More Than Doubled Since Early March
Congress introduced the 350-home institutional definition in early March. The threshold caught much of the industry off guard: portfolio research had traditionally defined institutional investors as those owning 1,000 or more homes. Most firms could not immediately identify the investors captured by the new definition, let alone determine how they were positioning ahead of potential restrictions.
Our first cohort reading after the definition was introduced showed 4,668 active institutional for-sale listings. By July 19, the count had reached 9,586, up 105% from that baseline.
Seasonality explains part of the spring increase, but our data shows it does not fully explain the institutional for-sale dynamic. Total national listings grew 49% across the February through July window, from 1.09M to 1.62M. Institutional listings grew 132% - ~2.7x the overall market's pace.
Aggregate asking value followed the same pattern.
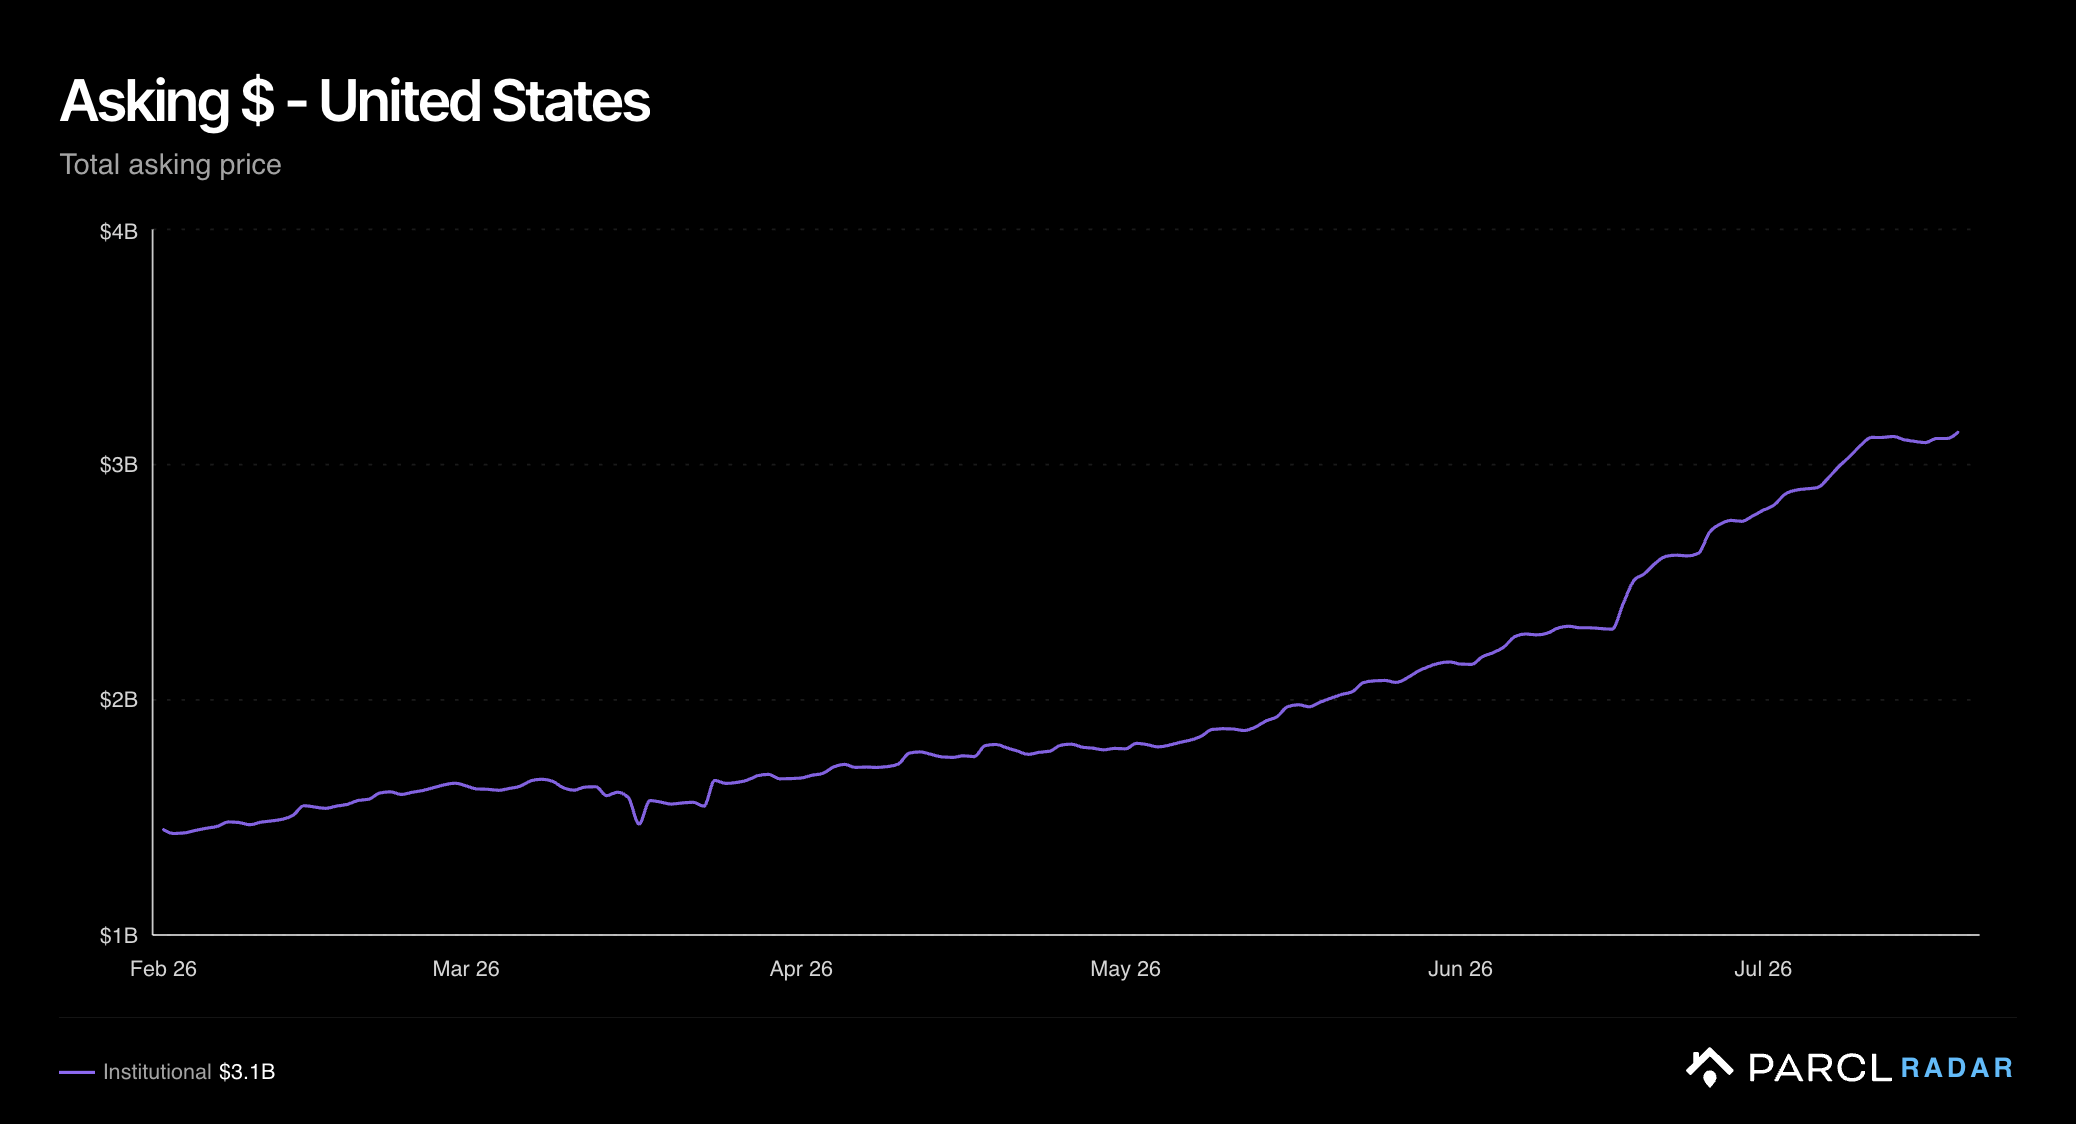
Institutional homes worth $1.66B were on the market the week Congress introduced the definition. By July 19, that asking value had reached $3.14B, up 89%, while cumulative markdowns on active institutional listings rose from $56M to $129M.
Institutional inventory also gained share of the total for-sale market.
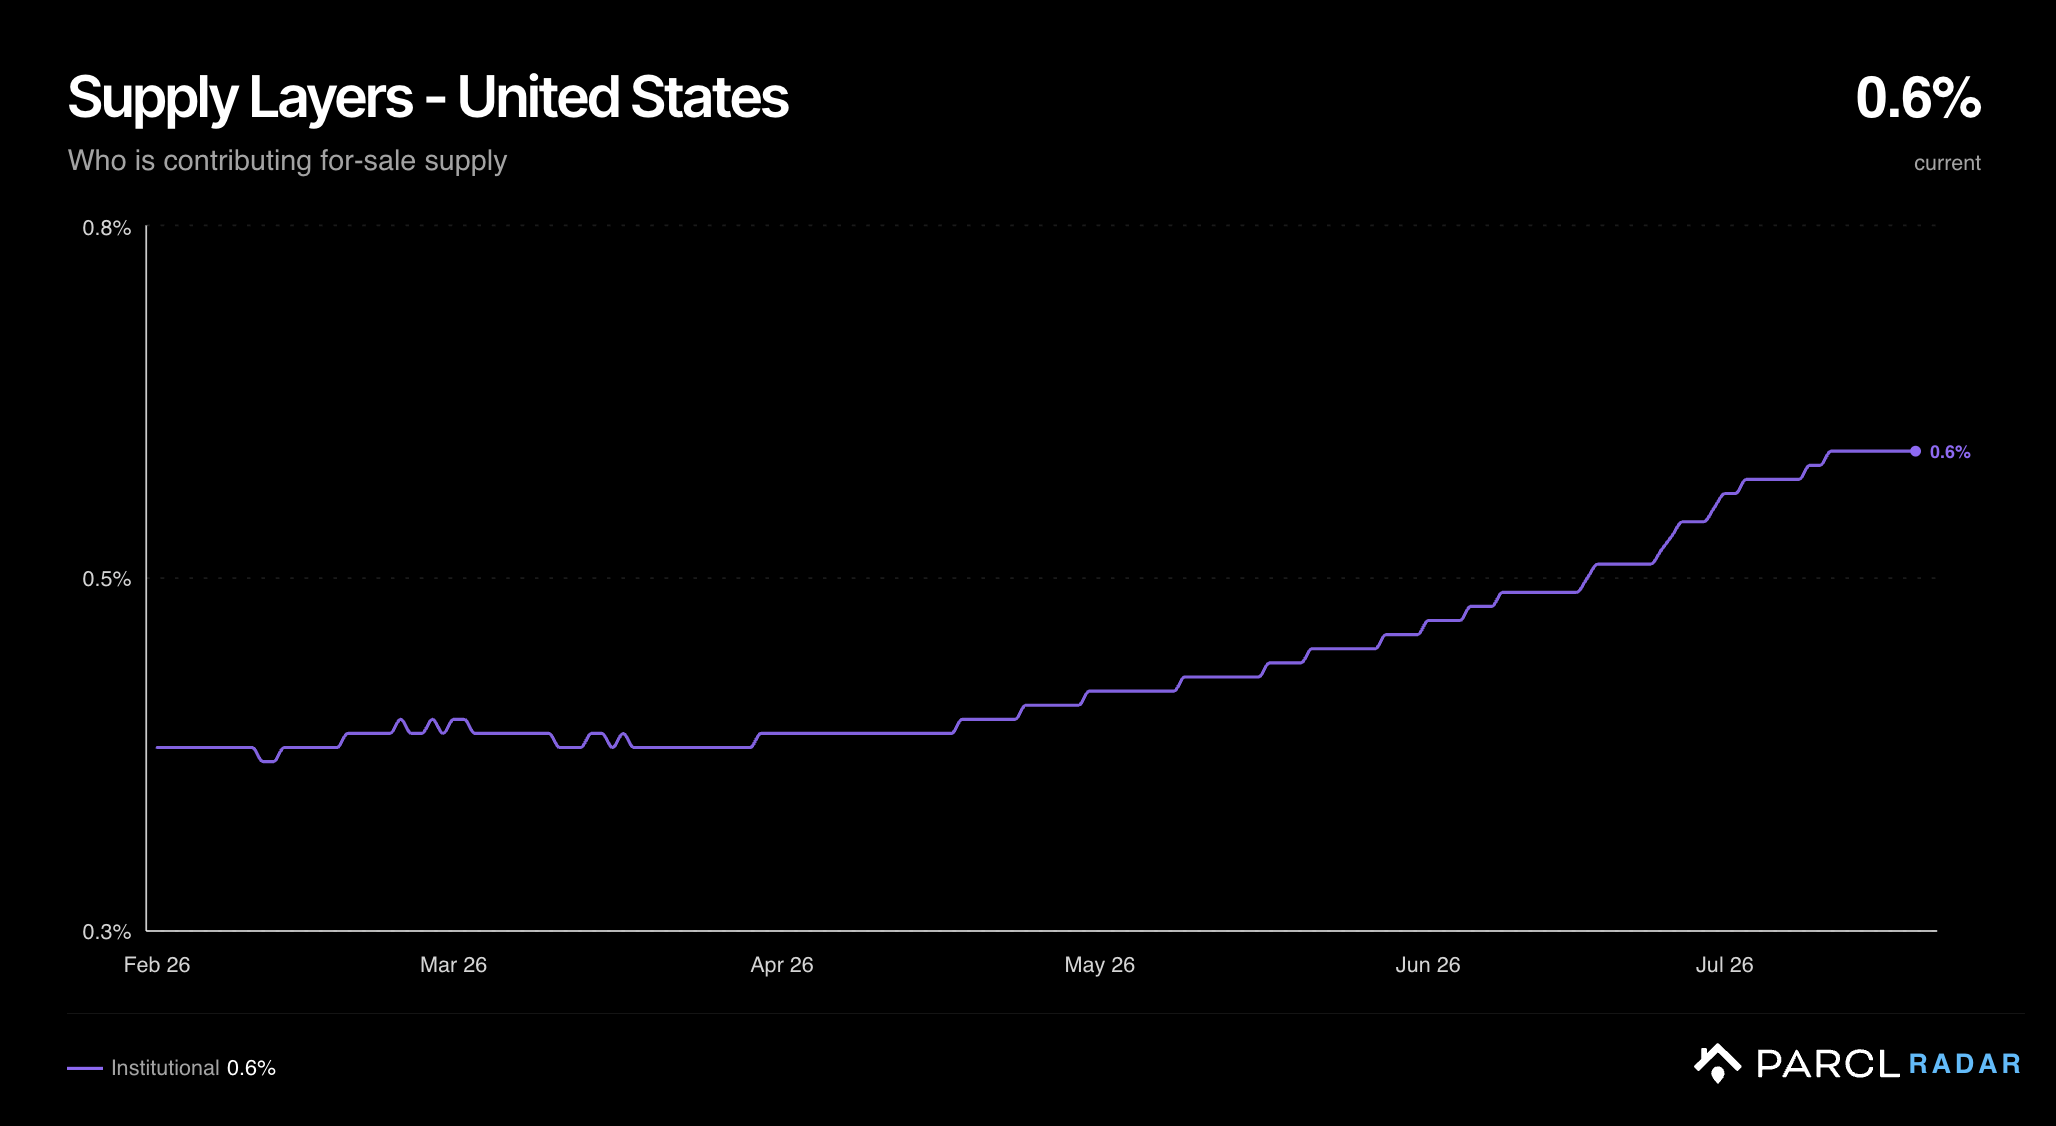
The cohort's share of all US listings rose from 0.38% on February 1 to 0.59% on July 19.
Institutional selling predates the definition, and the market comparison bounds how much of the growth ordinary spring supply can explain. The cohort's listing activity has clearly accelerated.
Institutional Sellers Broke Away From Every Other Cohort
Listing counts measure the size of the sell-down; our Motivated Seller Index (MSI) measures how hard sellers are working to clear it. The MSI is a 0–10 composite of time on market, price-cut frequency, cut depth, and cut speed. The snapshot below compares the institutional cohort against every other seller type nationally.
Cohort | MSI | Price cuts % |
|---|---|---|
All listings | 5.2 | 39.3% |
Owner-occupied | 5.5 | 40.5% |
Investor (all) | 5.4 | 40.2% |
Institutional (350+) | 8.6 | 55.8% |
Source: Parcl Labs national snapshot, July 20, 2026.
The other three cohorts cluster between 5.2 and 5.5. Institutional is 8.6, more than three points above every other cohort.
The daily MSI series shows the gap widening.
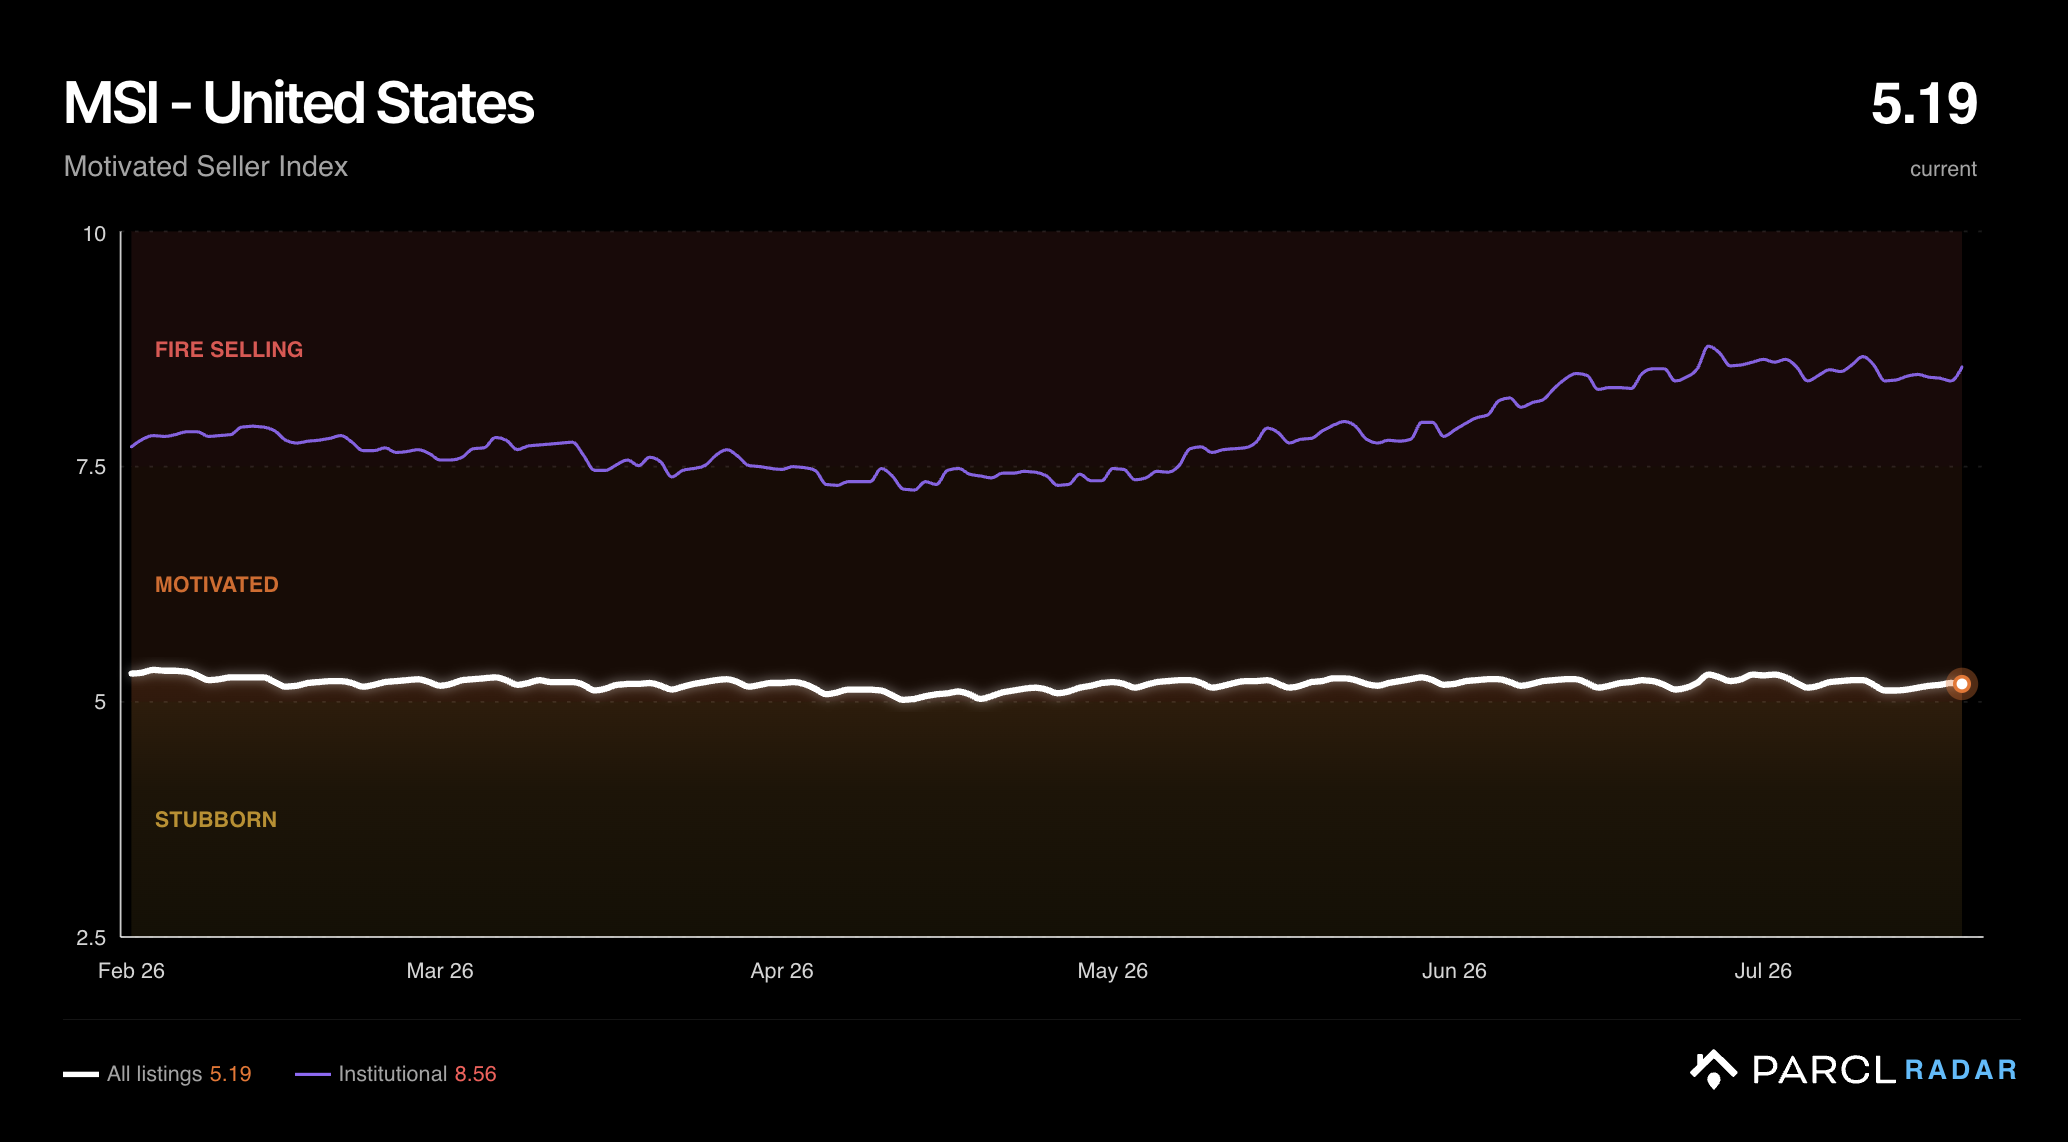
Market MSI was flat across the window, 5.3 in February to 5.2 now, while institutional MSI rose from 7.7 to 8.6. Elevated institutional price-cut behavior is driving this gap.
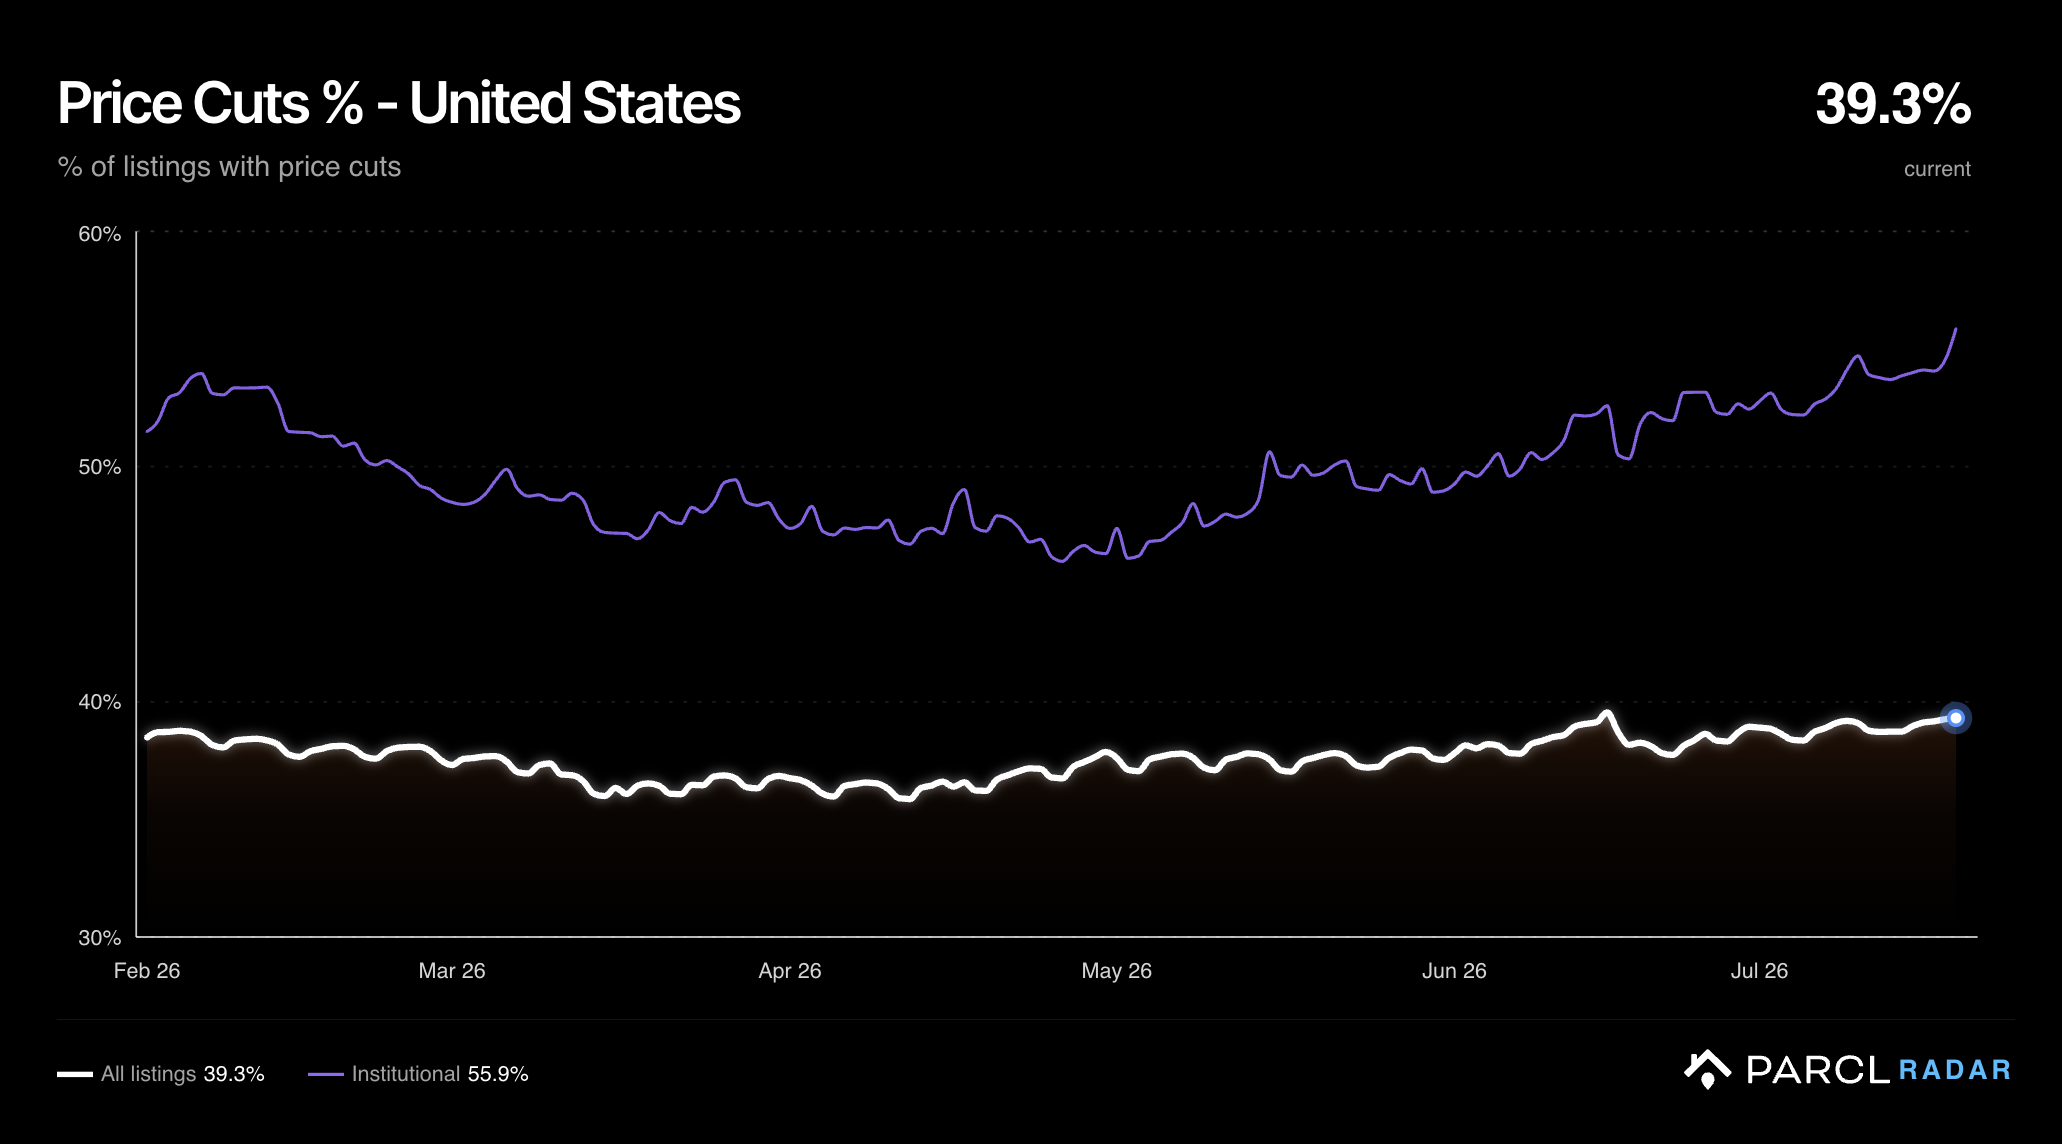
56% of institutional listings carried a price cut on July 19, against 39% for the market, and the rate climbed even as inventory expanded: 51.5% in early February, 55.9% on July 19. New listings arrive without price cuts, so you might expect a cohort adding inventory this quickly would see its cut rate fall; instead, institutional inventory grew 132% and the cut rate rose.
The pattern is not set-and-forget listing or aspirational pricing to test what the market will pay: investors are actively working to find buyers and move these homes off their books, with cuts arriving more often, moving faster, across a growing base of listings, at rates above the broader market and every other cohort.
Two Exits: One Operator in the Tertiary Midwest, the Broader Cohort Across the Sunbelt
Institutional share of active listings is rising in two market types, each with a different source of for-sale activity: tertiary Midwest and Mid-South metros, where selling comes almost entirely from a single institutional owner, and the Sunbelt, where it is spread across the cohort. The metro map below ranks markets by institutional share of active listings.
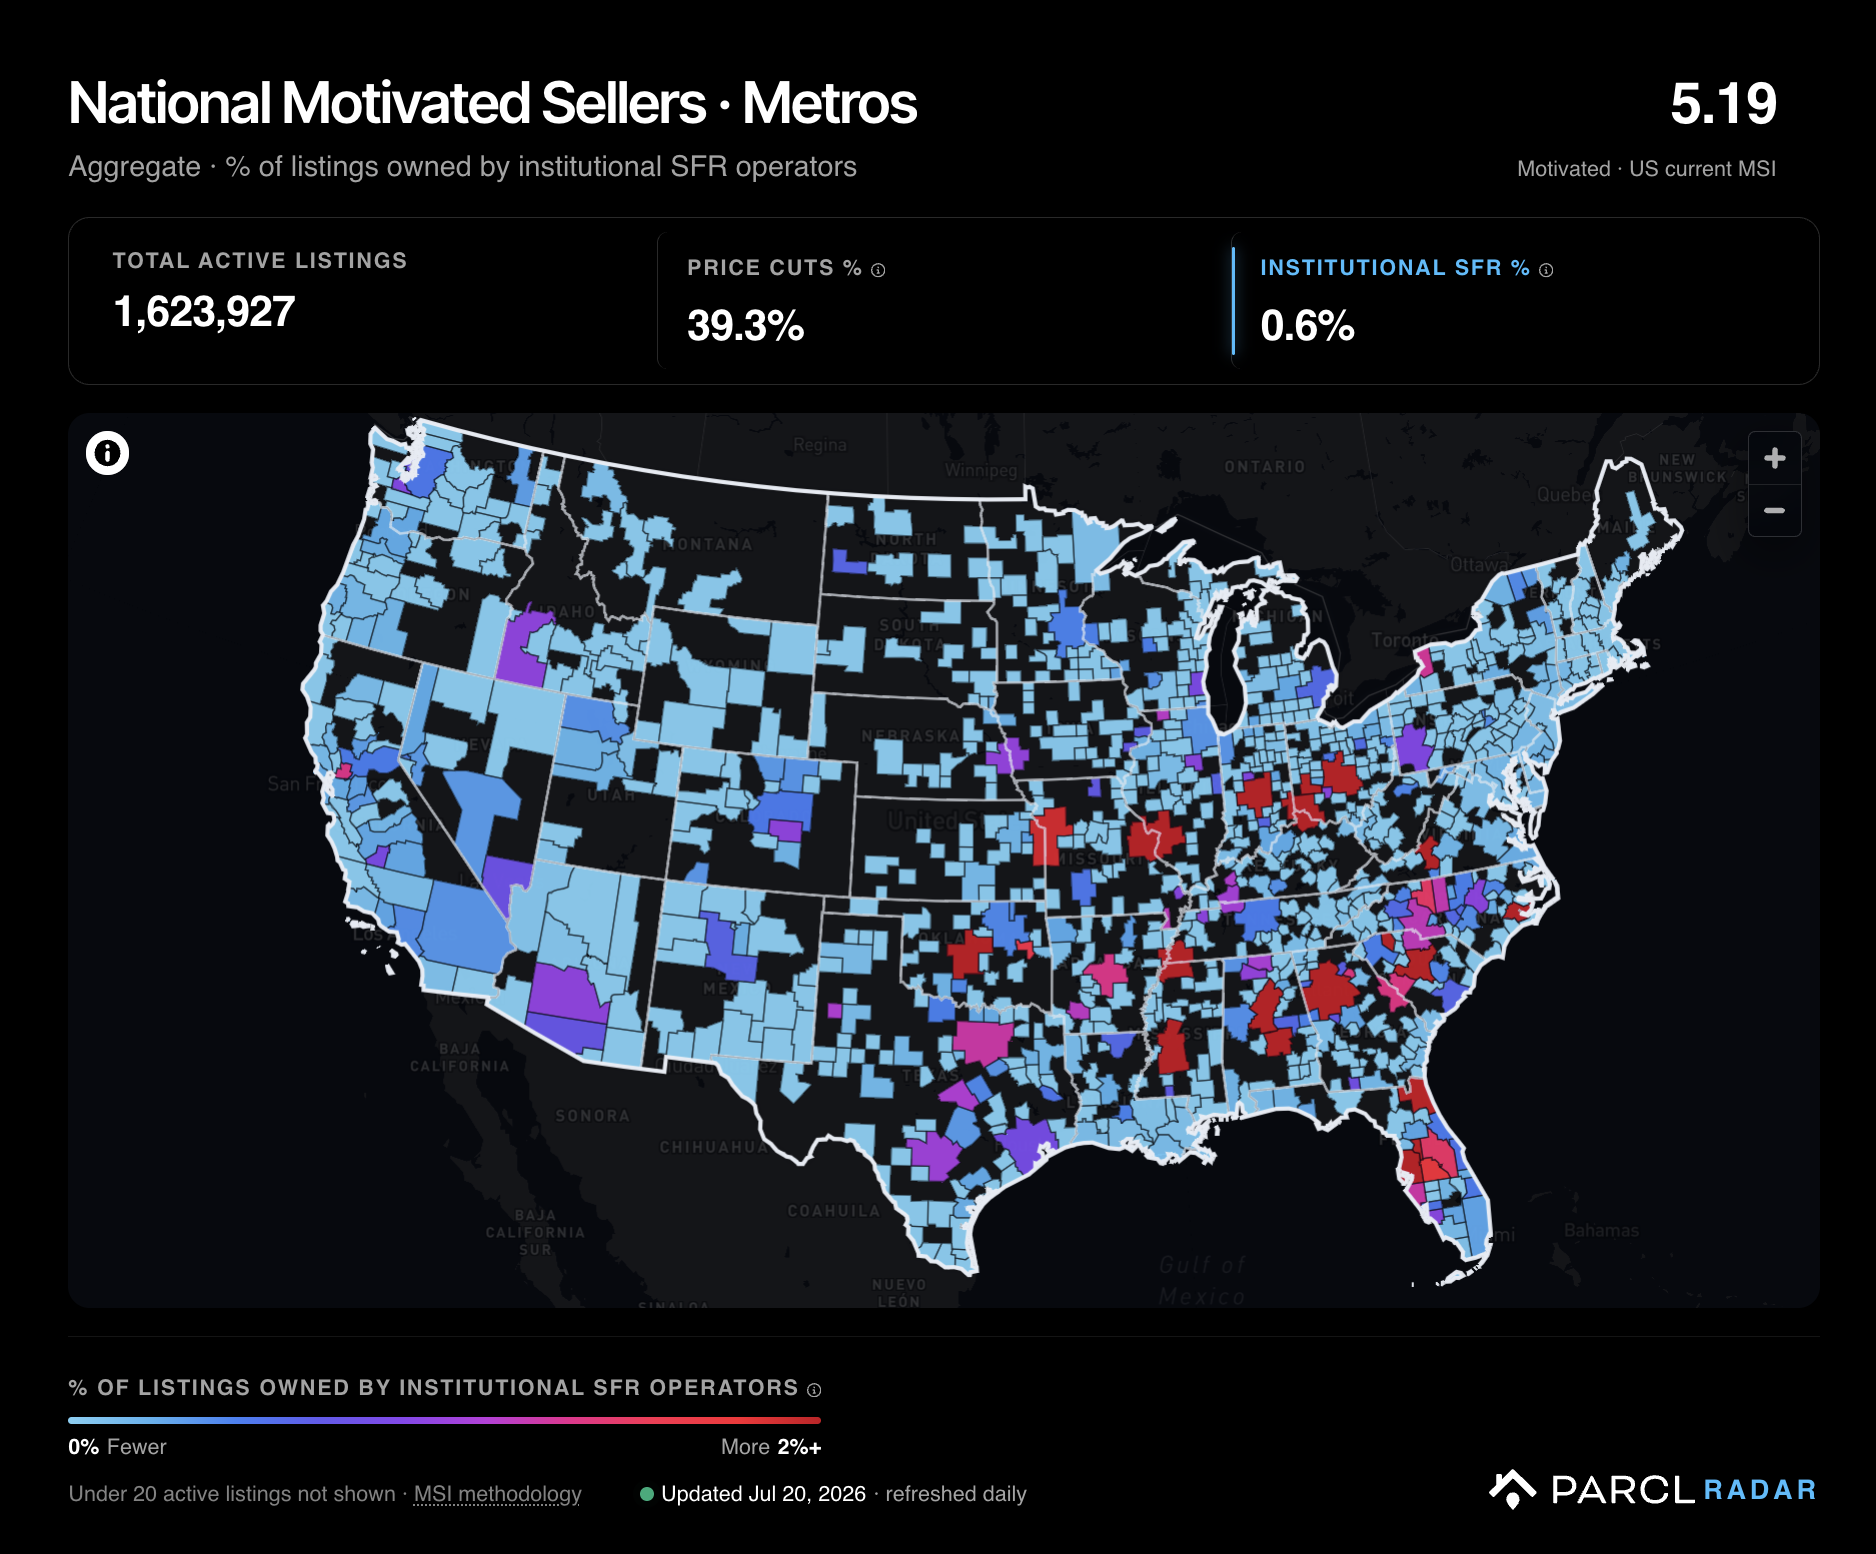
A Mid-South and Ohio Valley band - Jackson (6.5% of all listings), Memphis (4.9%), Dayton (3.6%), St. Louis (3.6%), Cincinnati (2.9%), Columbus (2.6%) - tops the share rankings, with Atlanta (3.5%) the one major metro among them.
Within that band, institutional seller motivation is elevated. Institutional MSI reads 10 in Cincinnati, Columbus, and Memphis, and 10 across Ohio statewide, against metro-wide readings between 5.2 and 6.1 in those markets.
One operator accounts for most of that band's selling. VineBrook had 1,886 homes listed for sale on July 20 - 10% of its total portfolio. Nationally, VineBrook accounts for ~1 in 5 institutional listings. In its core markets, it is nearly all of them.
Metro | VineBrook for-sale | Institutional listings | VineBrook share |
|---|---|---|---|
Cincinnati, OH | 192 | 213 | 90% |
Dayton, OH | 103 | 118 | 87% |
Pittsburgh, PA | 53 | 65 | 82% |
Columbus, OH | 168 | 210 | 80% |
Columbia, SC | 82 | 110 | 75% |
Jackson, MS | 116 | 159 | 73% |
St. Louis, MO | 247 | 378 | 65% |
Memphis, TN | 217 | 343 | 63% |
Indianapolis, IN | 122 | 206 | 59% |
Spartanburg, SC | 39 | 69 | 57% |
Atlanta, GA | 122 | 1,234 | 10% |
Source: VineBrook listings across select markets via Parcl AI Connect, July 20, 2026.
The Sunbelt, where institutional SFR portfolios have traditionally concentrated, shows the different storyline in terms of listing contribution. Atlanta leads the country with 1,234 institutional listings, followed by Tampa (569), Dallas (554), and Houston (393). Listing-level true owner attribution identifies sellers across the institutional cohort, including Tricon Residential, Rithm Capital, My Community Homes, Invitation Homes, Progress Residential, and AMH.
No single operator is driving the activity. The Sunbelt listings reflect broad portfolio churn across institutional owners, not an exit by one platform.
Atlanta: Epicenter of the Sunbelt Exit
Atlanta's lead in the Sunbelt exit follows a pattern Parcl Labs has tracked since 2023: institutional ownership is most concentrated in the Atlanta market, and our research has repeatedly shown investor pressure signals often surface there first.
Atlanta's institutional inventory held near 670 listings from February into March before reaching a low of 610 on March 17. It then climbed to 1,027 on June 21 and 1,234 on July 19 - more than double the March low and up 20% in four weeks. Georgia now has 1,321 institutional listings statewide, equal to a nation-leading 2.1% of active listings and 1.5 percentage points above the national rate.
The zip-level map shows where that supply is concentrated.
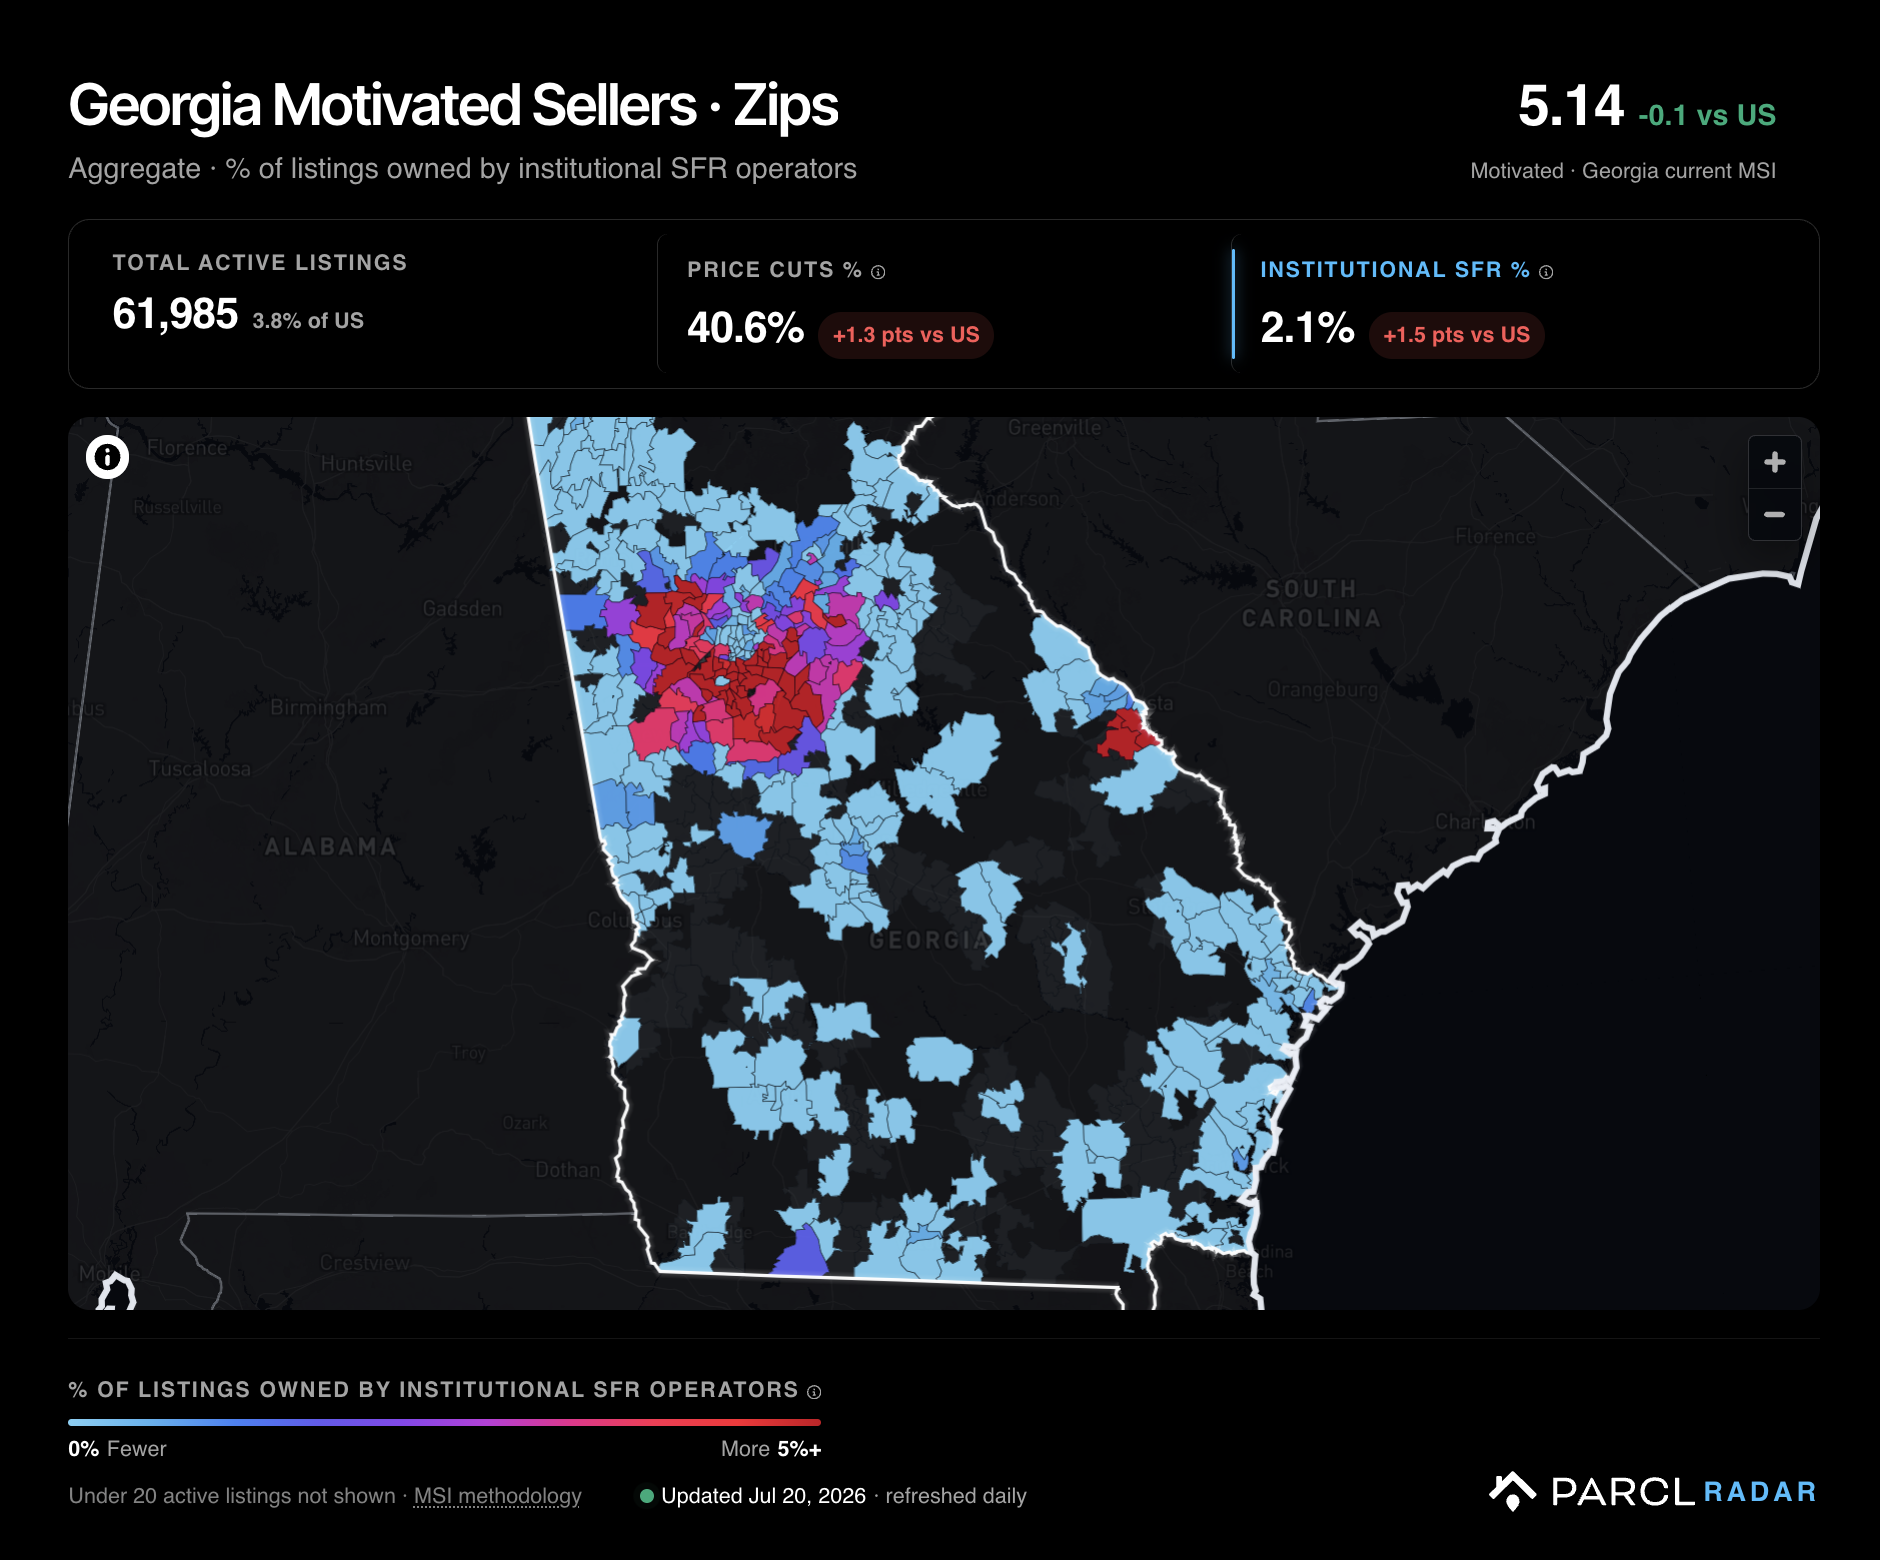
Institutional listings ring the Atlanta metro and thin out across the rest of the state, with a second cluster around Augusta.
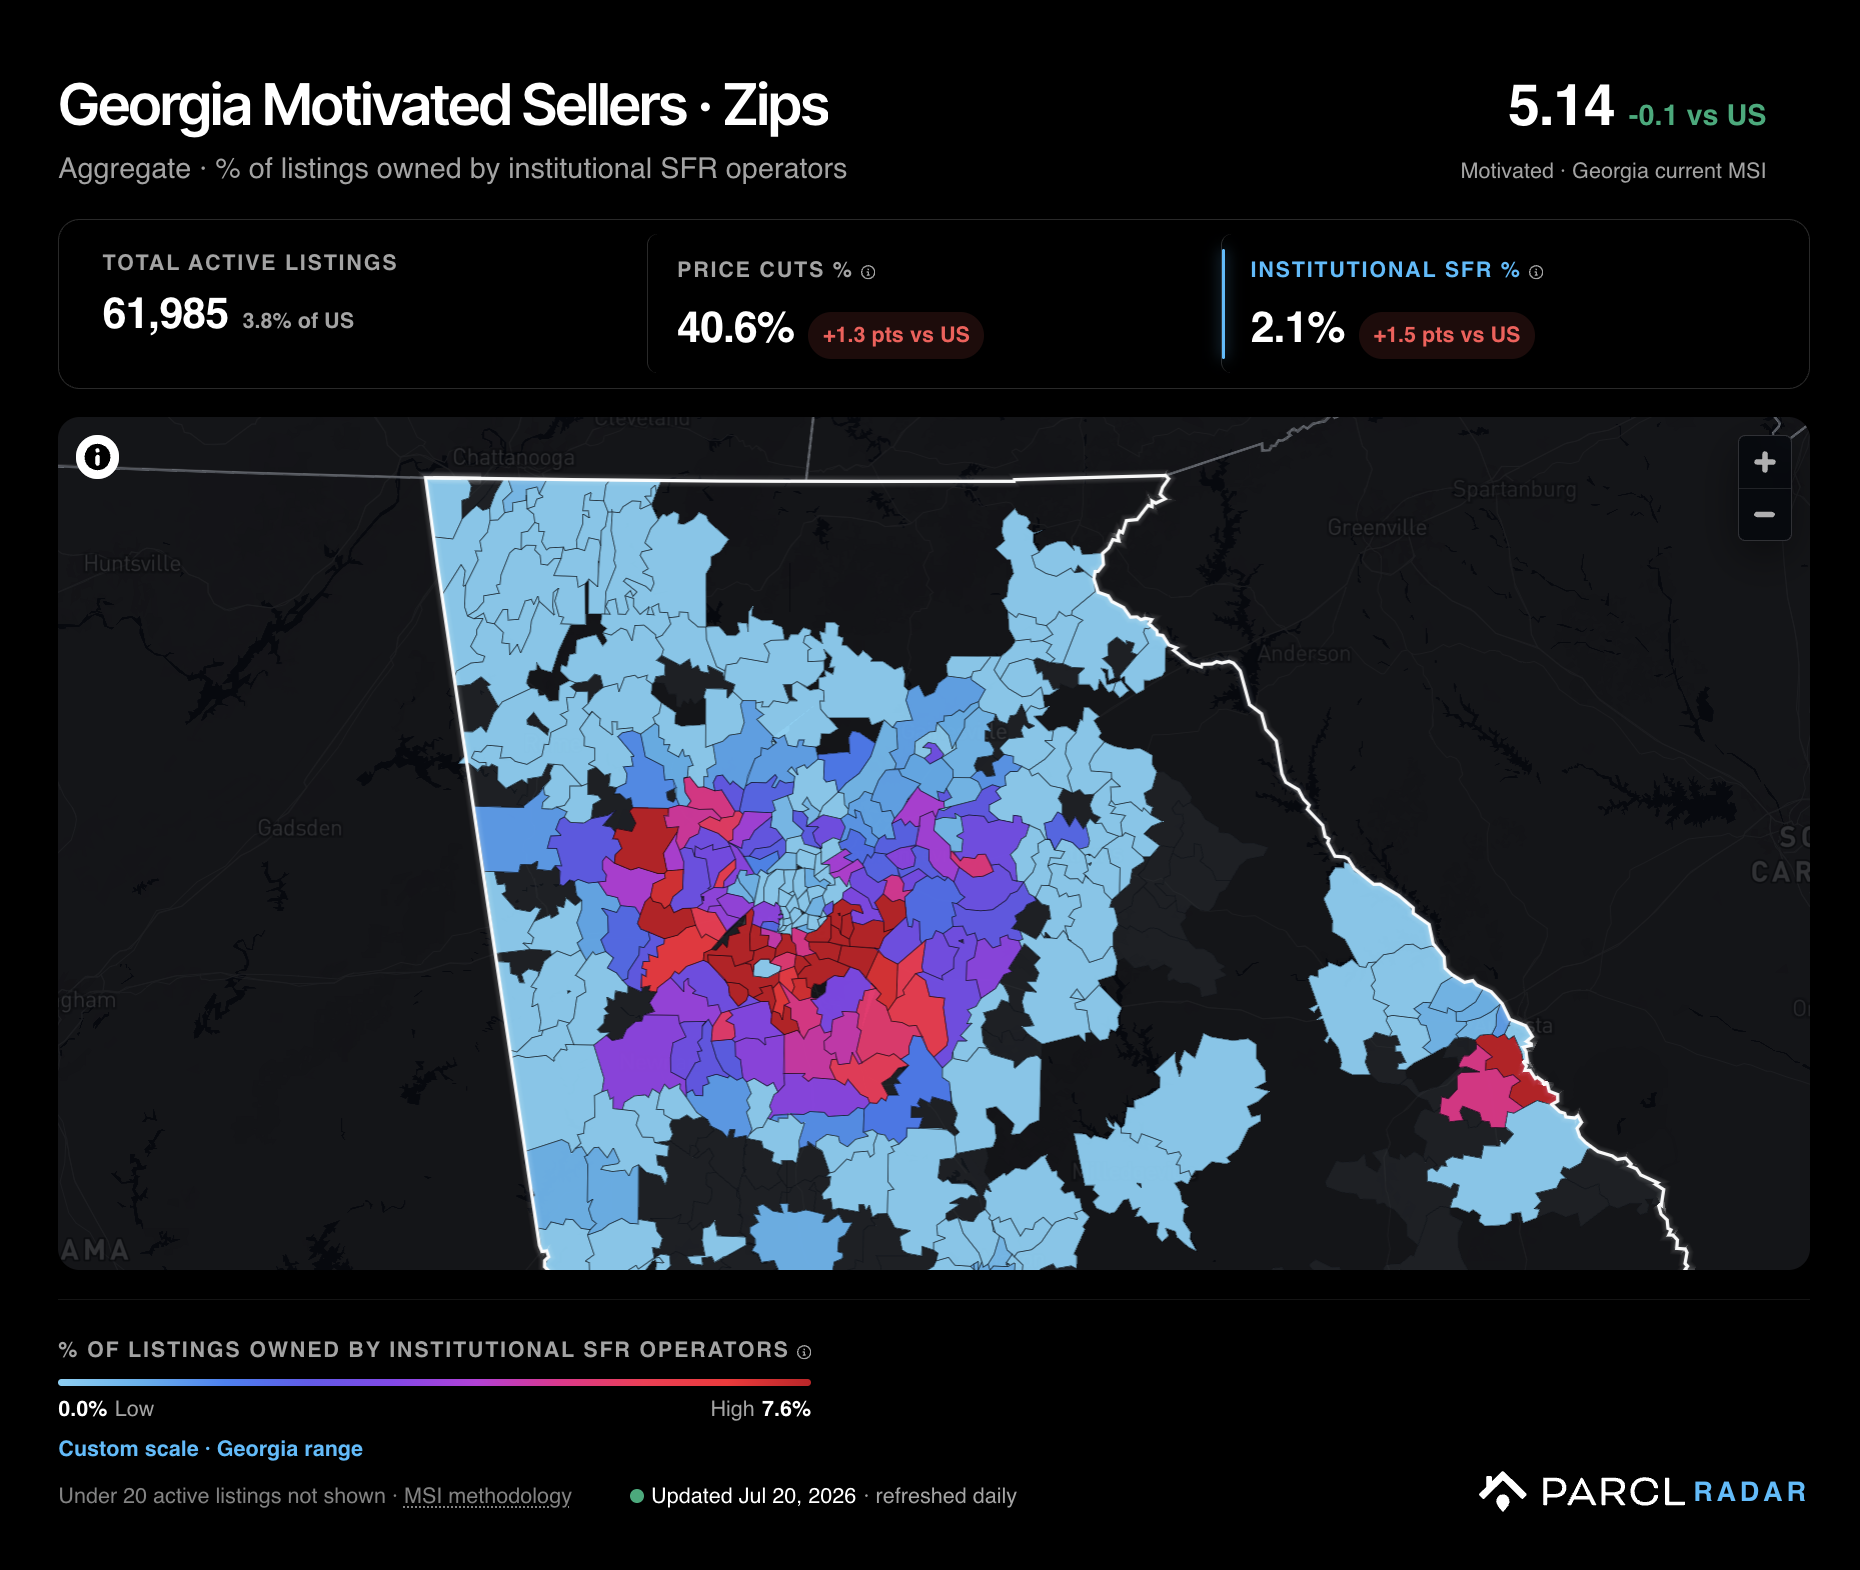
Within the metro, listings follow the same south and southeast ownership corridor we identified in March. In the reddest zips, institutional operators account for up to 15% of active listings.
Institutional sellers in Atlanta are cutting prices more aggressively and showing greater motivation than the cohort nationally.
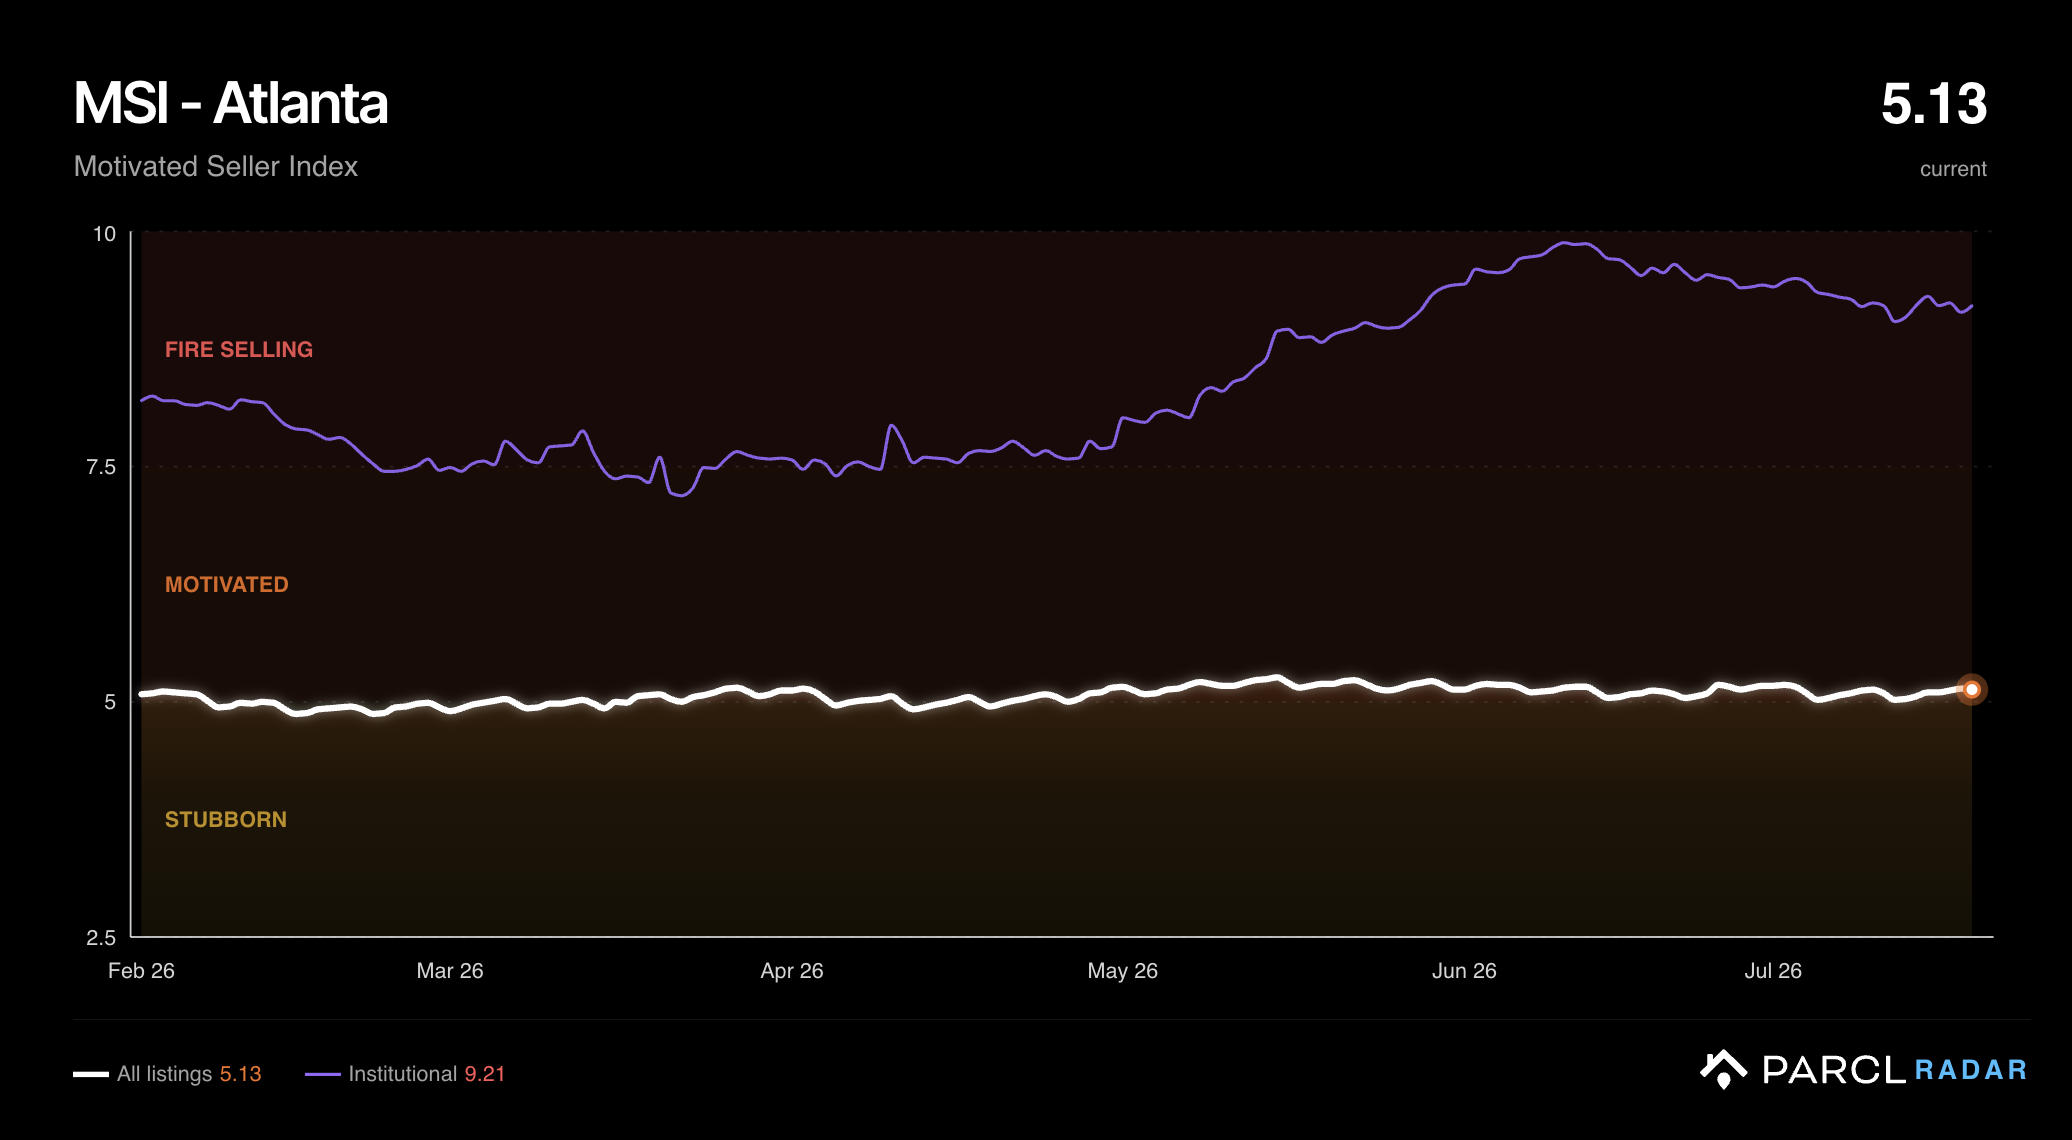
Atlanta's institutional MSI has remained above 9 since early June and read 9.2 on July 19, compared with 5.1 for the metro overall. Of the metro's institutional listings, 61% have cut price, versus 56% for the cohort nationally.
Acquisition data for the broader investor cohort shows the same tilt toward selling. In Georgia, investors buy 0.54 homes for every one they sell. Nationally, investors still buy more than they sell, at 1.33 homes for every sale.
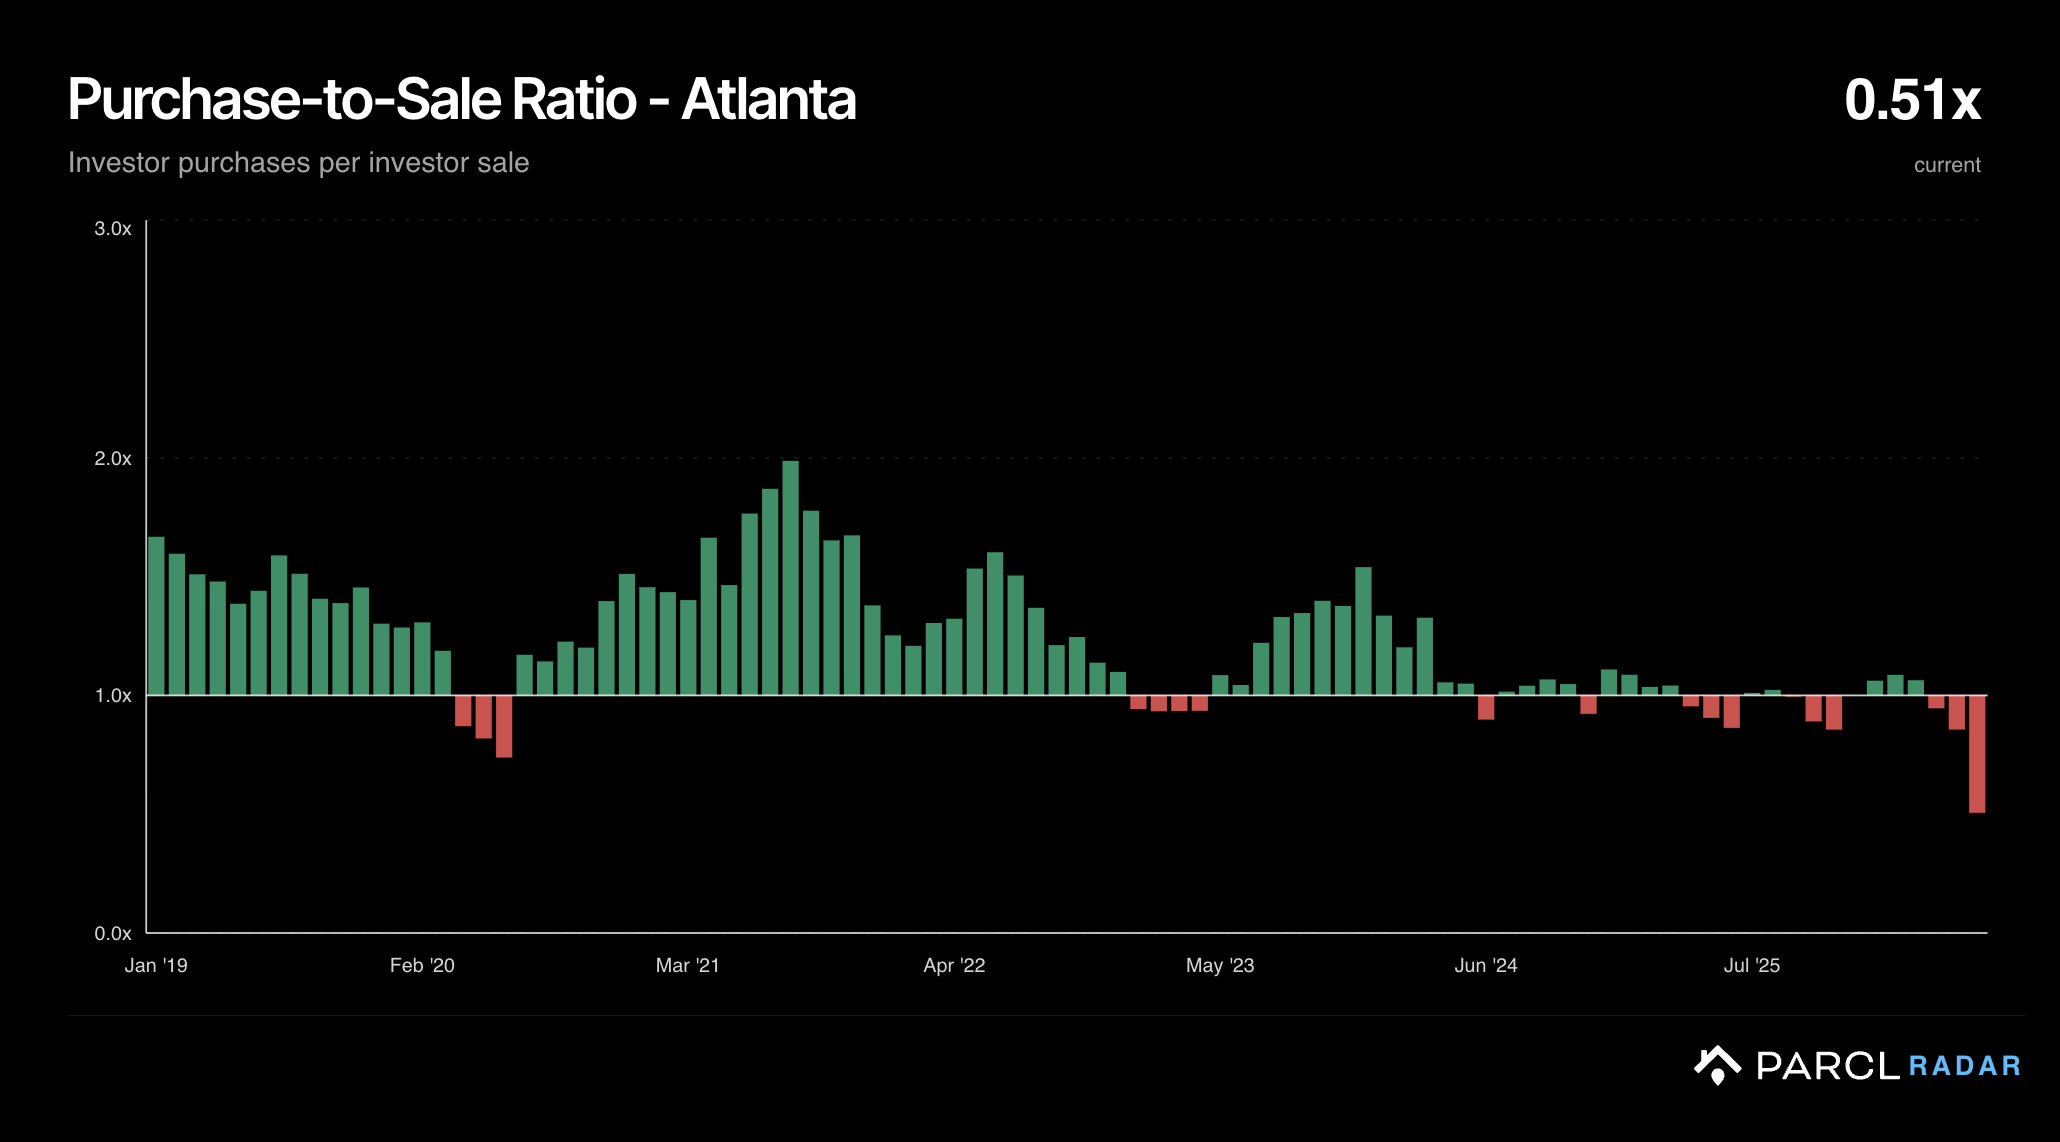
The imbalance is even sharper in Atlanta. At 0.51, investors sell nearly two homes for every one they acquire.
What to Watch in the Live Data
What we are watching for next:
Does institutional for-sale inventory keep growing now that the law is in force?
Do institutional sellers get more aggressive with pricing as listings age into the summer? Institutional MSI has held between 8.4 and 8.6 since June 21. Institutional listing counts continuing to rise as MSI steepens would be a red flag.
Does a second VineBrook emerge? VineBrook is the clear outlier, with 10% of its portfolio listed for sale. With the acquisition rules now set, we are tracking which operators are buying and selling. We have already identified a handful of portfolios where for-sale inventory is rising as a share of total holdings.
Do sold homes reach owner-occupants? The institutional provisions were written to move this supply to homebuyers. However, in March we found investor-to-investor sales rising. Whether the homes this institutional cohort clears reach homebuyers or recirculate within the investor ecosystem is something we are watching closely.
How to Track What Happens Next
Every chart above is a screenshot of a live view from our new research capability: Parcl HQ.
The live Motivated Seller Index map on tracks institutional for-sale supply daily - listing counts, aggregate asking value, and seller motivation for the institutional investor cohort, alongside every other US market segment. Every state, metro, county, and zip, analyzed daily, with full history.
identifies the true owner behind the listings - every property an investor owns, every listing posted, and the brokers handling each disposition.
provides the underlying ownership, listing, and MSI insights behind this analysis. answers questions against the full Parcl Labs dataset, including what is going on across the institutional cohort, in natural language.
The law is in force. The cohort it names was selling before it existed, and the data to follow both refreshes every day here.
Follow Us for More