
When Sellers Can’t Sell: Accidental Landlords Surge in Markets Where Institutional Investors Are Most Exposed
Jun 16, 2025 · 7 min read
Failed home sellers are increasingly becoming landlords as the housing market weakens. See how top investors are responding in key US SFR markets
When Sellers Can’t Sell: Accidental Landlords Surge in Markets Where Institutional Investors Are Most Exposed
Institutional investors are highly concentrated: Large institutional investors (portfolios of 1,000+ single-family homes) hold over a third (36.8%) of their assets in just six U.S. housing markets: Atlanta, Phoenix, Dallas, Houston, Tampa, and Charlotte.
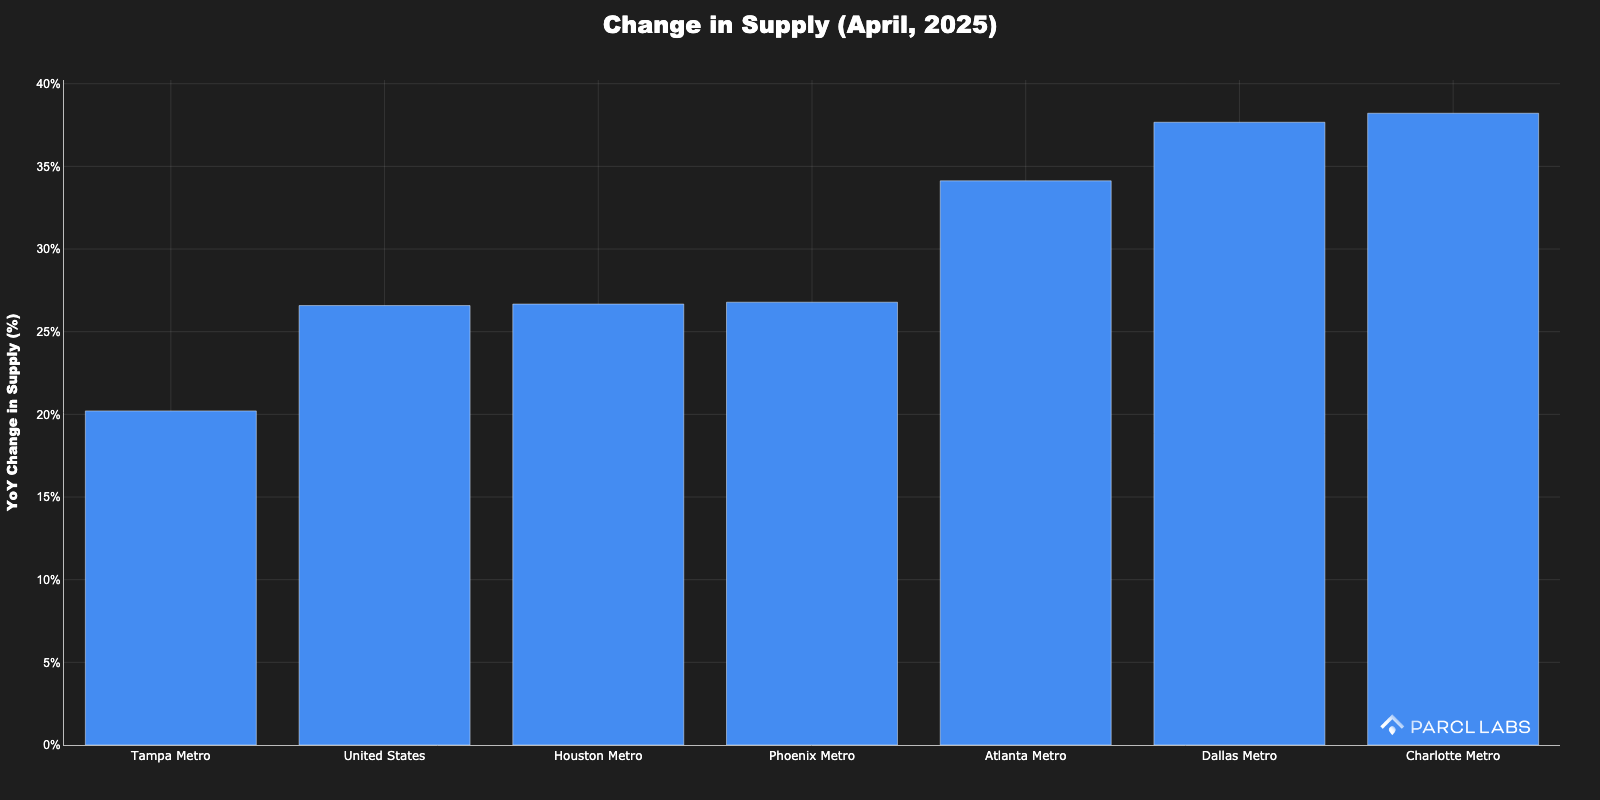
These institutional markets face weakening fundamentals. Surging inventory and declining buyer activity have intensified supply-demand imbalances, led by Charlotte (38.2% YoY inventory growth), Dallas (37.7%), and Atlanta (34.1%).
Worsening for-sale supply-demand conditions are creating new institutional competitors: accidental landlords. Parcl Labs’ data reveals increasing numbers of failed home-sellers shifting into rentals, up year-over-year in five of six institutional markets, led by Houston (+41.4%) and Dallas (+32.3%).
Institutions are responding by reducing exposure and capitalizing on home appreciation gains. Over the past year, large institutions became net sellers nationwide, with 76.7% of their net selling concentrated in these six core markets, led by Atlanta, Dallas, and Houston.
What’s next? One possibility: accidental landlords, worn down by rental market challenges, could shift from competitors to acquisition targets. Institutional investors, armed with cash from recent sales and anticipating home-price declines, are positioned to buy. Whatever unfolds, Parcl Labs remains the only source tracking these dynamics in real time.
Read on for Parcl Labs analysis of institutional investor strategies and the rise of accidental landlords.
Investor Concentration Creates Vulnerability
Institutional investors holding portfolios of 1,000 or more homes have concentrated their holdings in just six U.S. housing markets. Atlanta alone contains 13.3% of all large institutional portfolios, while Phoenix and Dallas each hold 5.4%. Houston captures 4.3%, with Tampa and Charlotte each representing 4.2%. Together, these six metros account for over one third (36.8%) of large institutional holdings nationwide.
This concentration strategy now faces mounting headwinds. As Parcl Labs has reported, these Sunbelt housing markets show increasing weakness, driven by surging for-sale supply and declining demand. For-sale inventory jumped across all six metros year-over-year, with Charlotte leading at 38.2% growth, followed by Dallas at 37.7% and Atlanta at 34.1%. Houston and Phoenix saw inventory climb 26.7% and 26.8% respectively, while Tampa recorded 20.2% growth.
Chart 1: Inventory YoY Growth (April 2025)
Rising inventory tells only half the story. Demand (sales) has also declined across these same markets, with Dallas leading the decline at 22.9% fewer buyers year-over-year. Tampa and Houston saw demand fall 8.8% and 13.7% respectively.
Chart 2: YoY Change in Supply and Demand (April 2025)
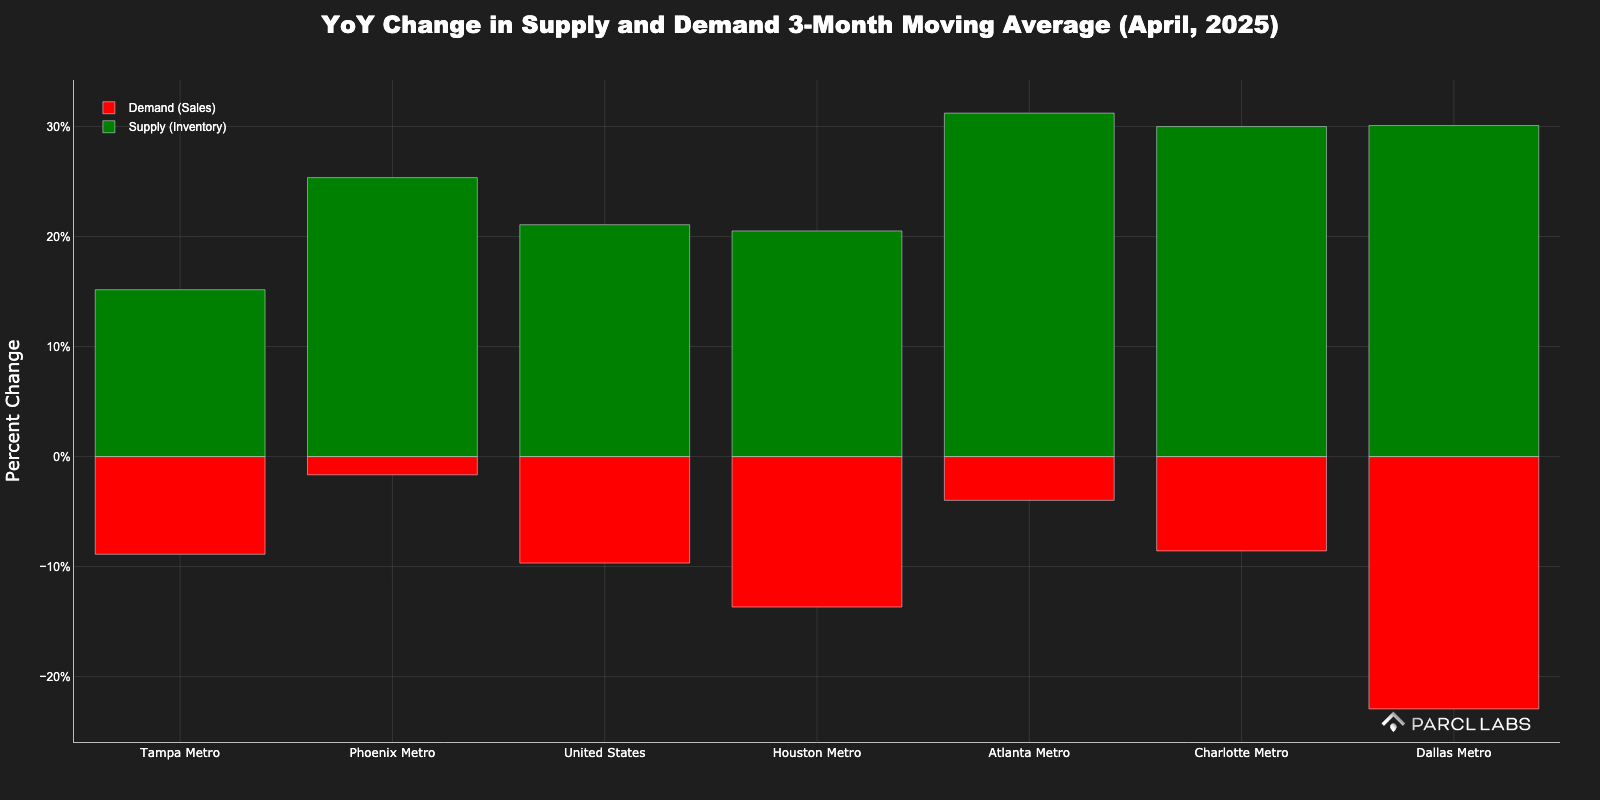
This supply-demand imbalance creates acute pressure in the very markets where institutional operators concentrated their bets, introducing new competition in both for-sale and rental markets.
The Accidental Landlord Phenomenon
The data clearly shows rising numbers of home sellers in markets where investors have the greatest exposure. When these home sellers cannot find buyers, they face three choices: delist and wait, cut price to find market clearing level, or convert to rental. The last option creates what Parcl Labs terms "accidental landlords": owners who enter the single-family rental market not by design but by necessity.
Parcl Labs tracks this phenomenon through proprietary analysis of listing conversions. The methodology identifies properties that shift from for-sale to for-rent status, then aggregates these property-level patterns at the market level. This approach illustrates how listing failures translate into rental supply expansion.
April 2025 data shows an acceleration in accidental landlord formation across institutional strongholds:
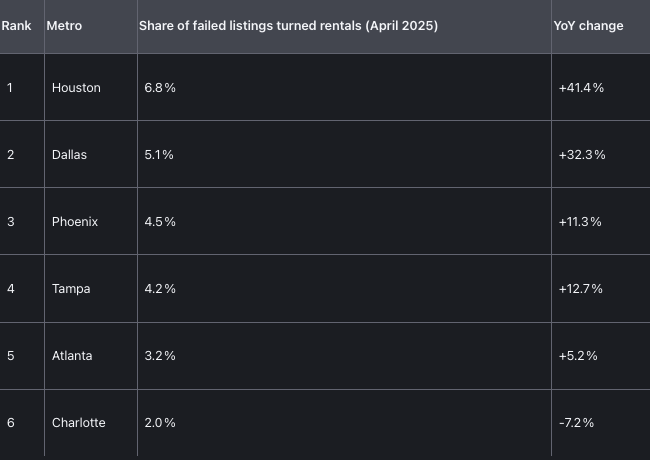
Historical data indicates accidental landlord formation follows seasonal trends, typically peaking during summer months. Current figures confirm this trend is accelerating. Five of six institutional markets show year-over-year increases heading into summer 2025.
Institutional Market Accidental Landlord Trends
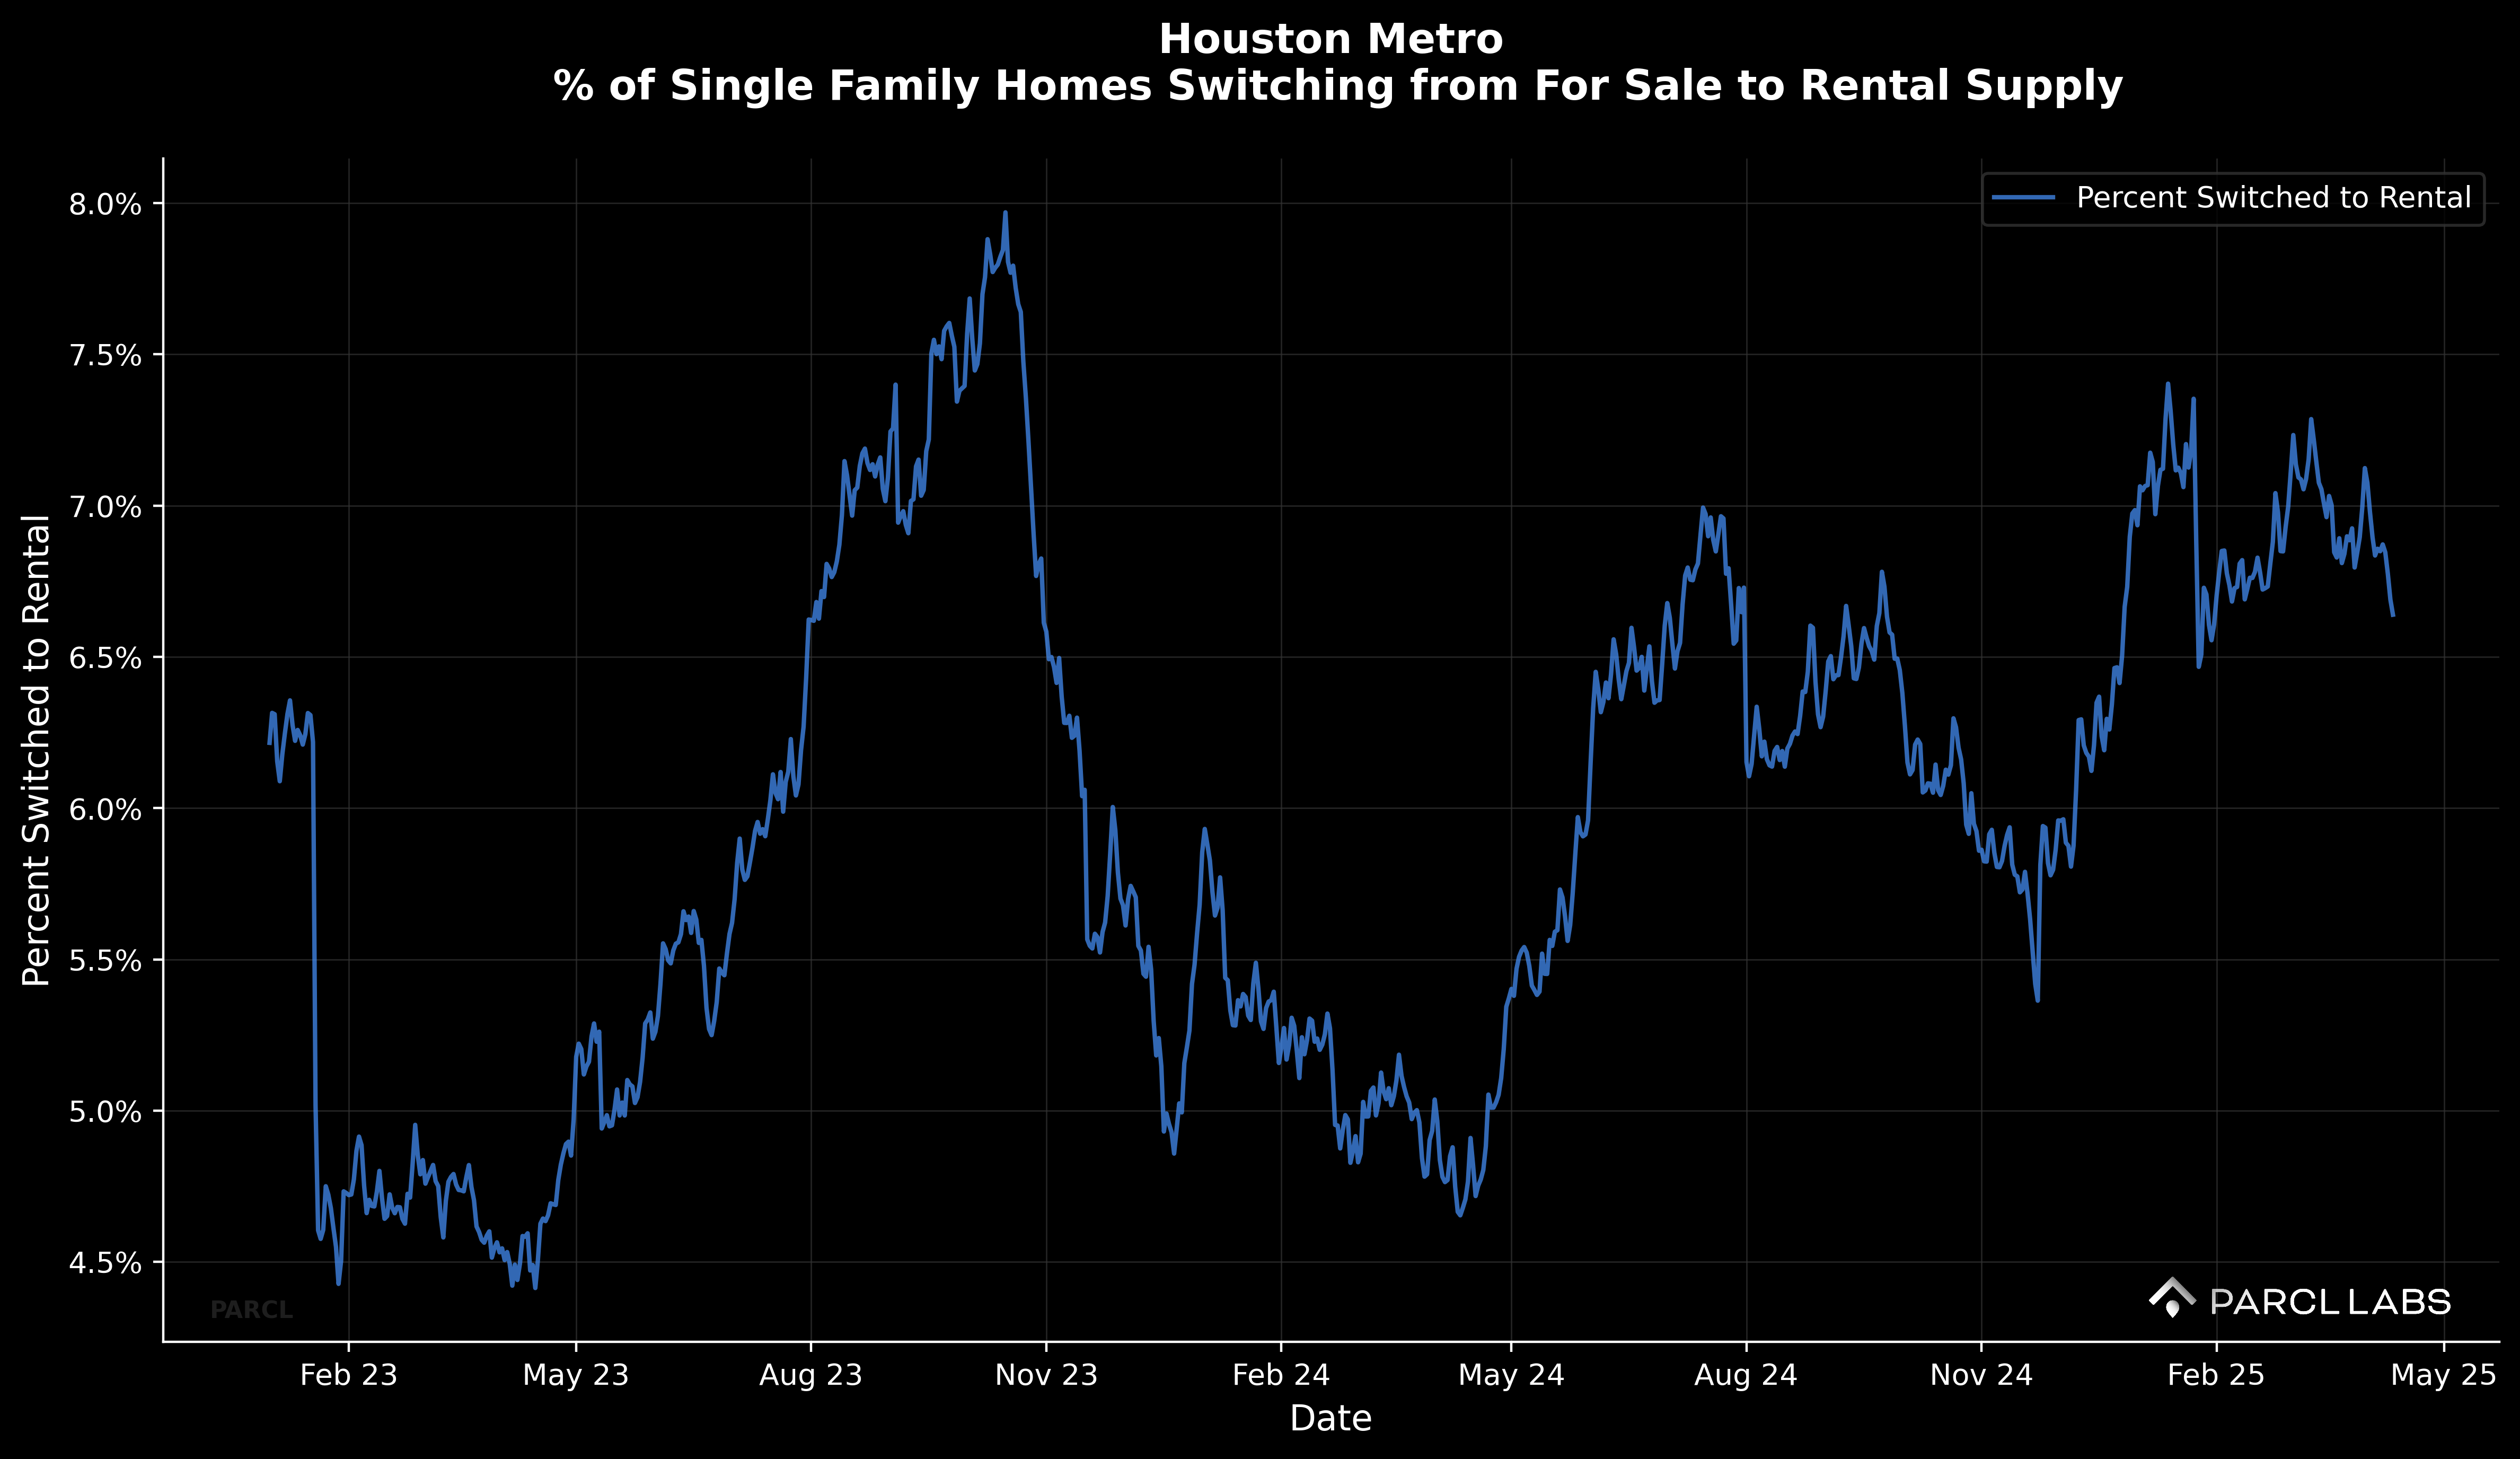
Houston leads with 6.8 % of unsuccessful sellers pivoting to the rental market, up 41.4 % year over year.
Chart 3: Houston Metro Accidental Landlord Rate (January 2023 - April 2025)
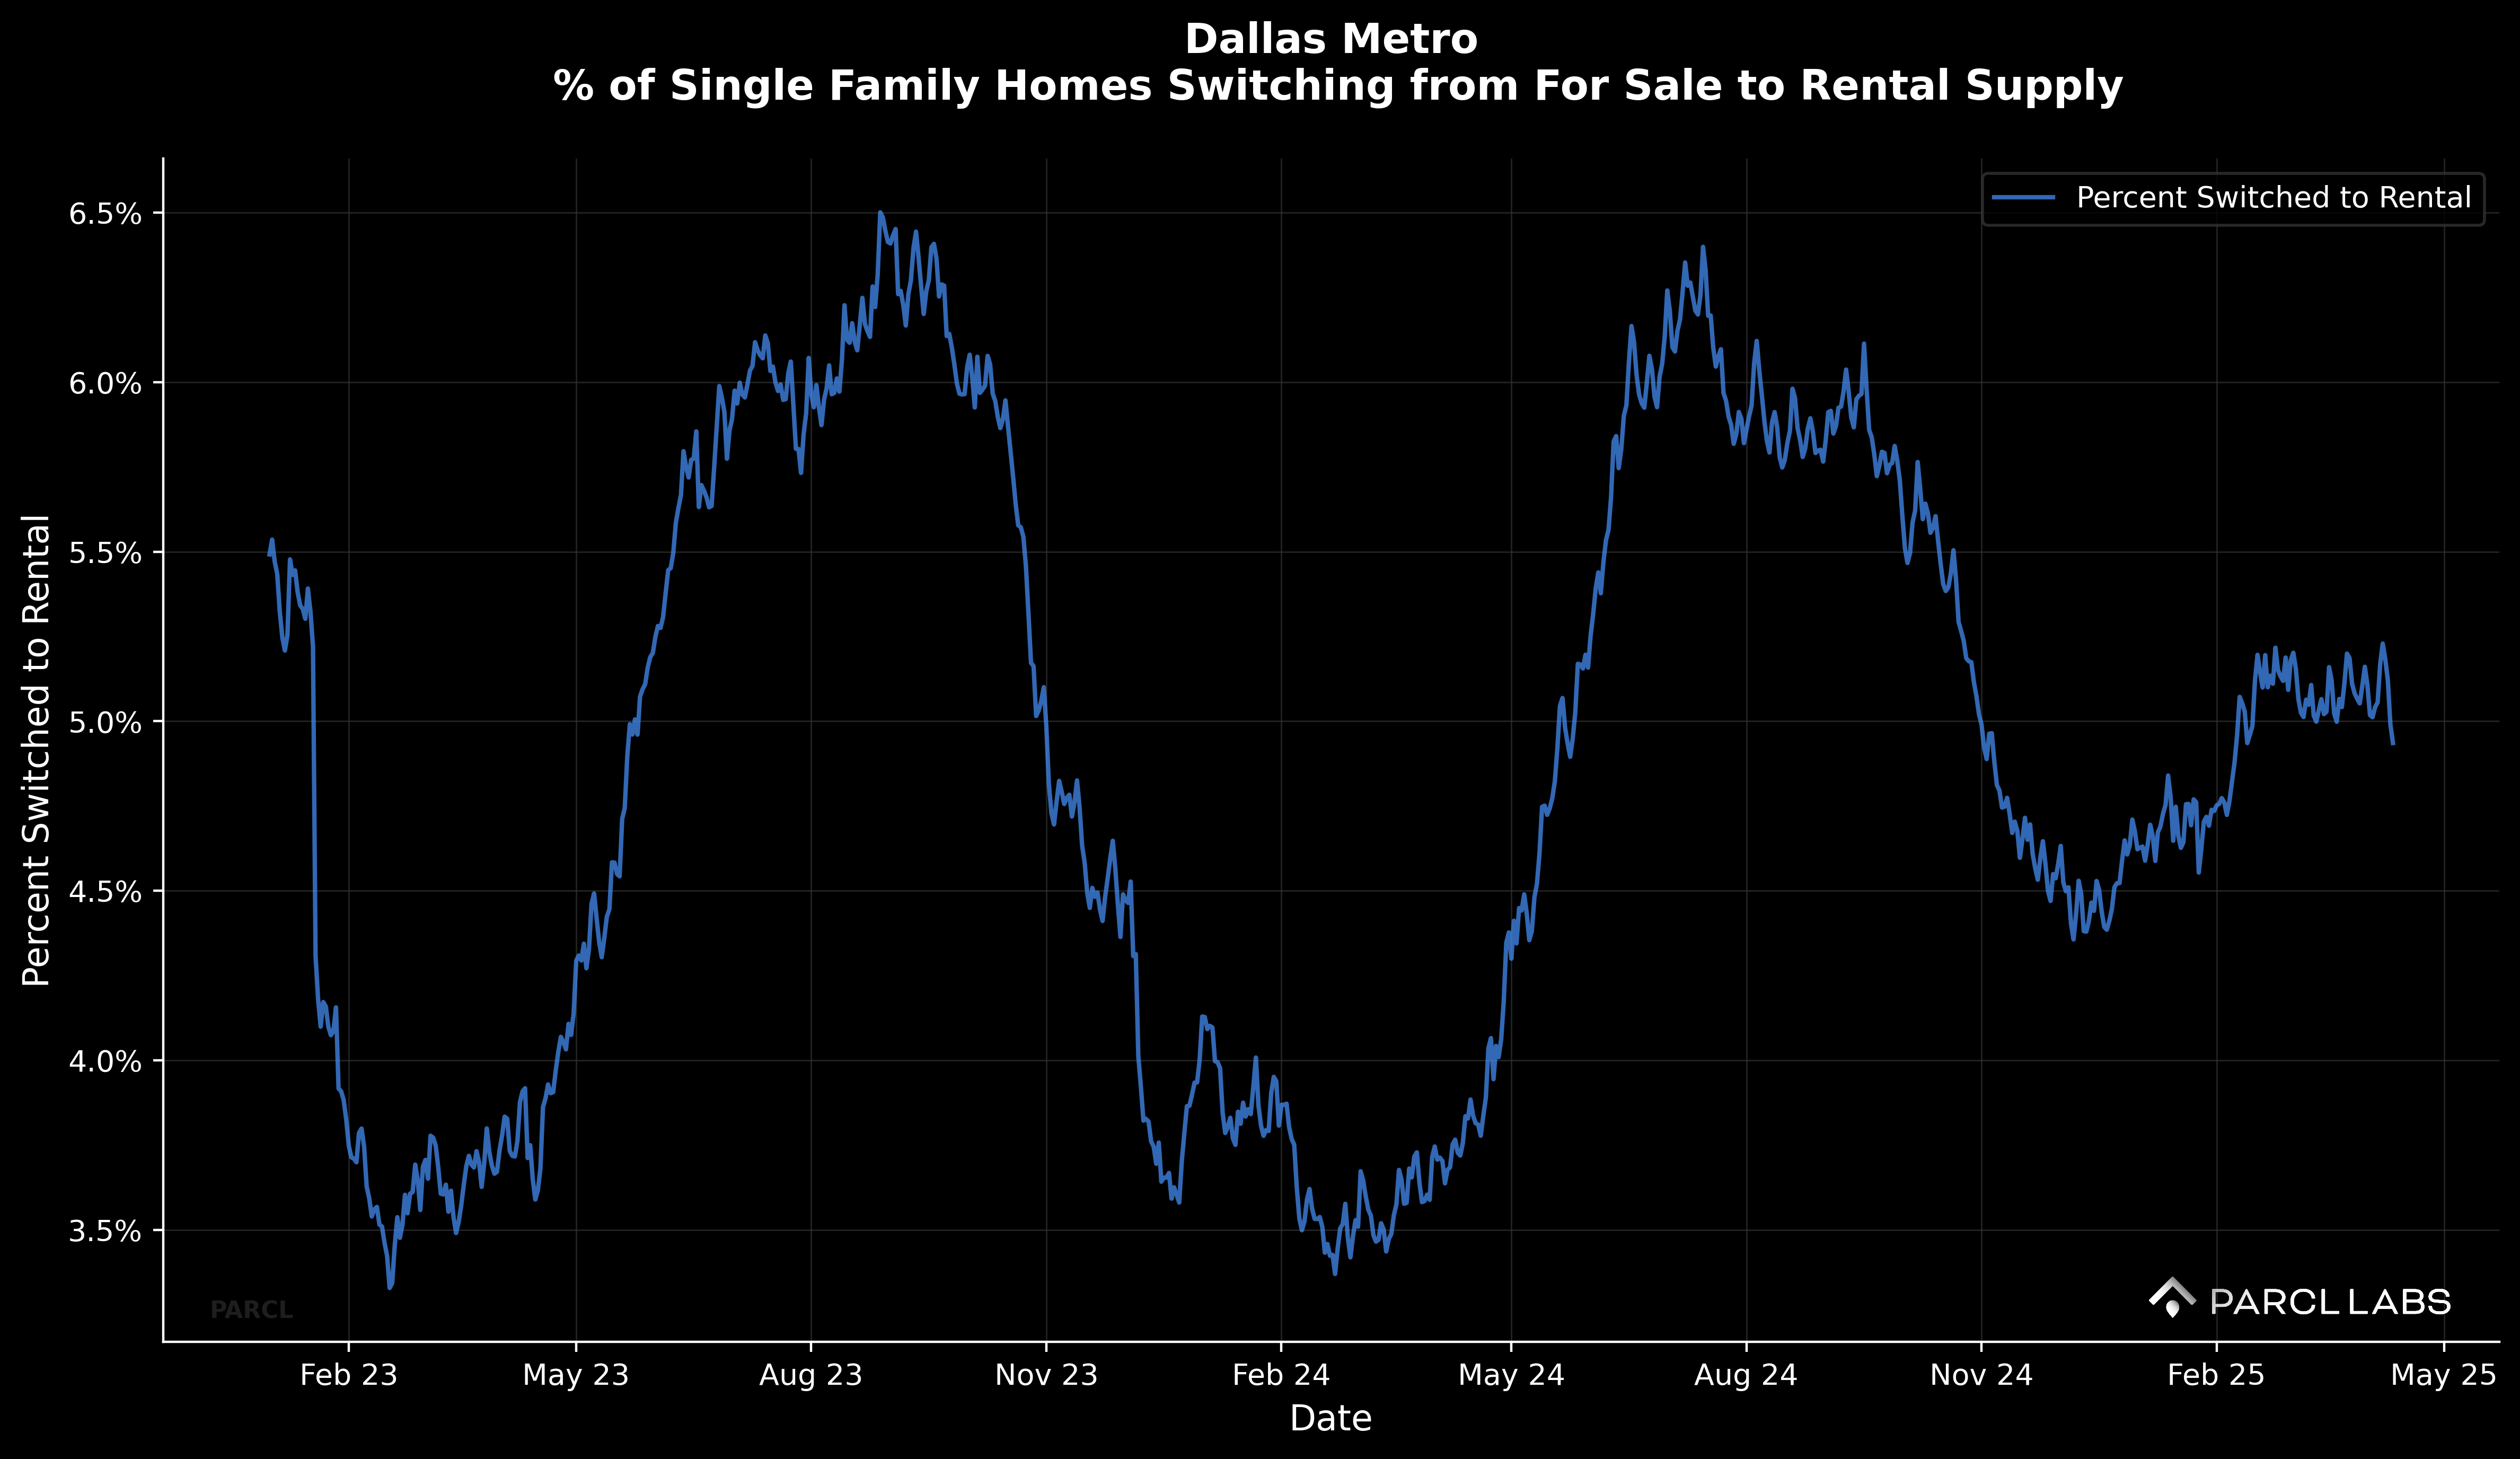
Dallas follows at 5.1 %, a 32.3 % YoY jump.
Chart 4: Dallas Metro Accidental Landlord Rate (January 2023 - April 2025)
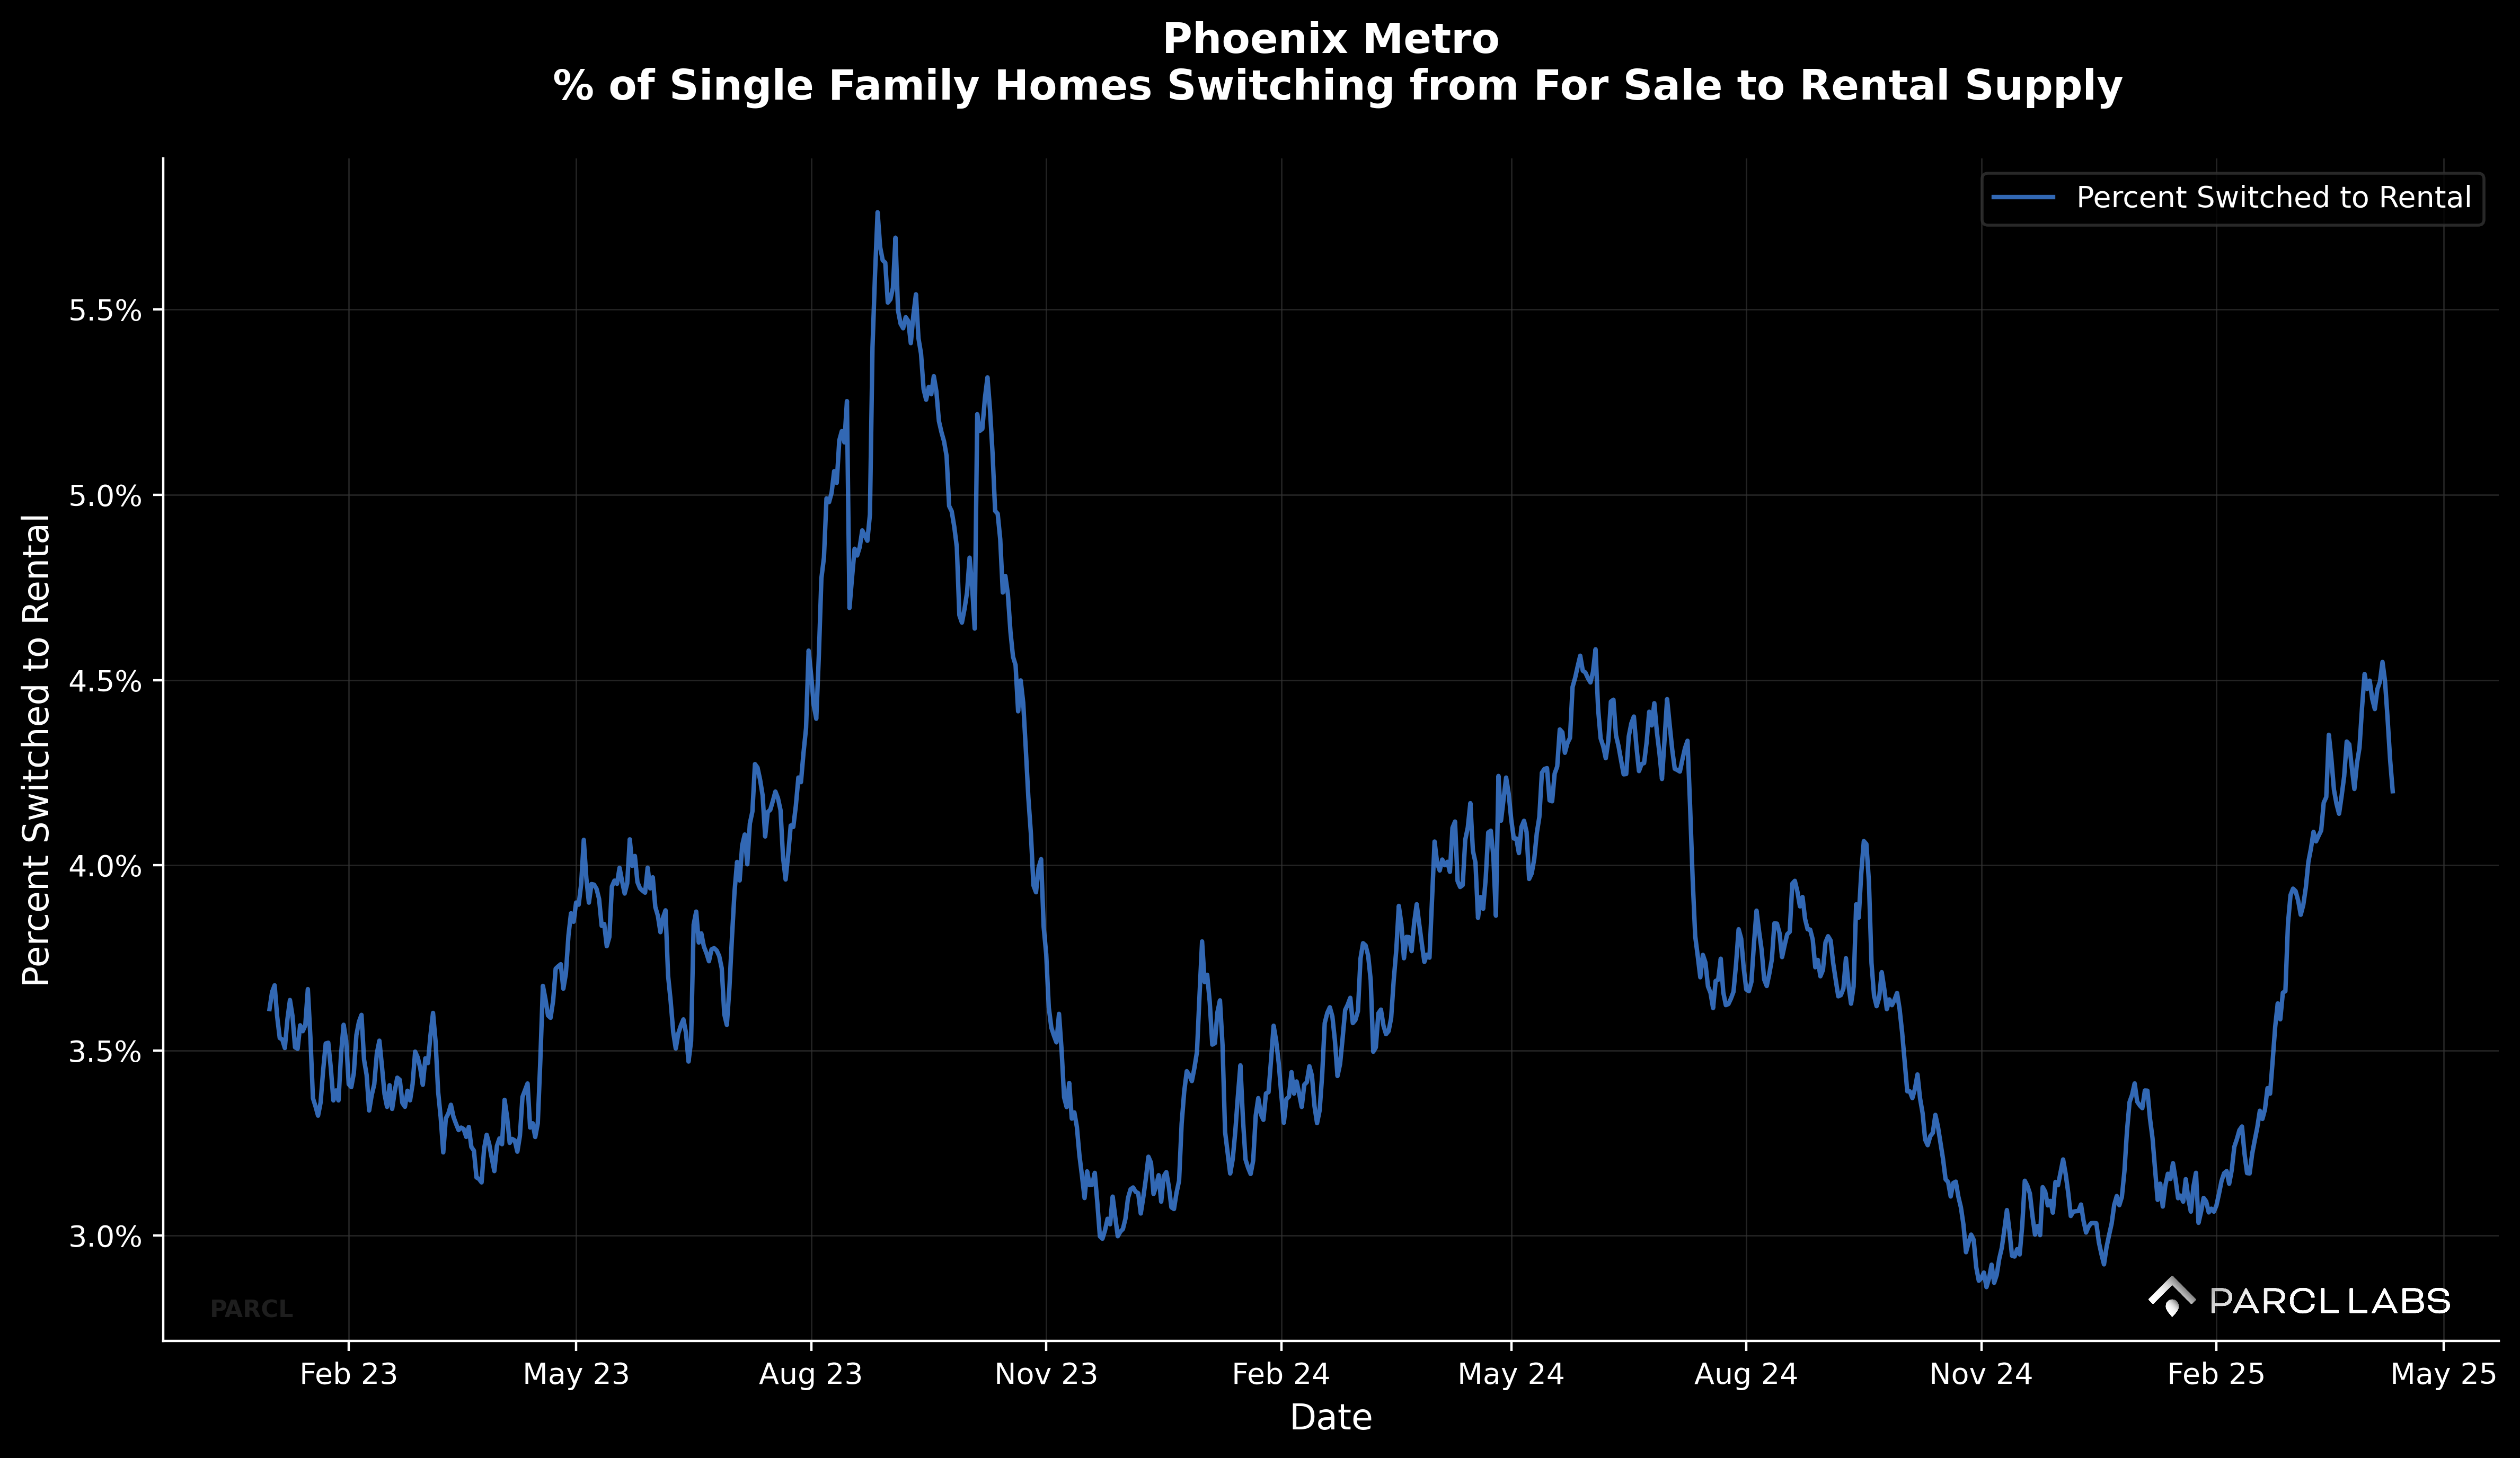
Phoenix and Tampa post double‑digit growth but lower absolute shares.
Chart 5: Tampa Metro Accidental Landlord Rate (January 2023 - April 2025)
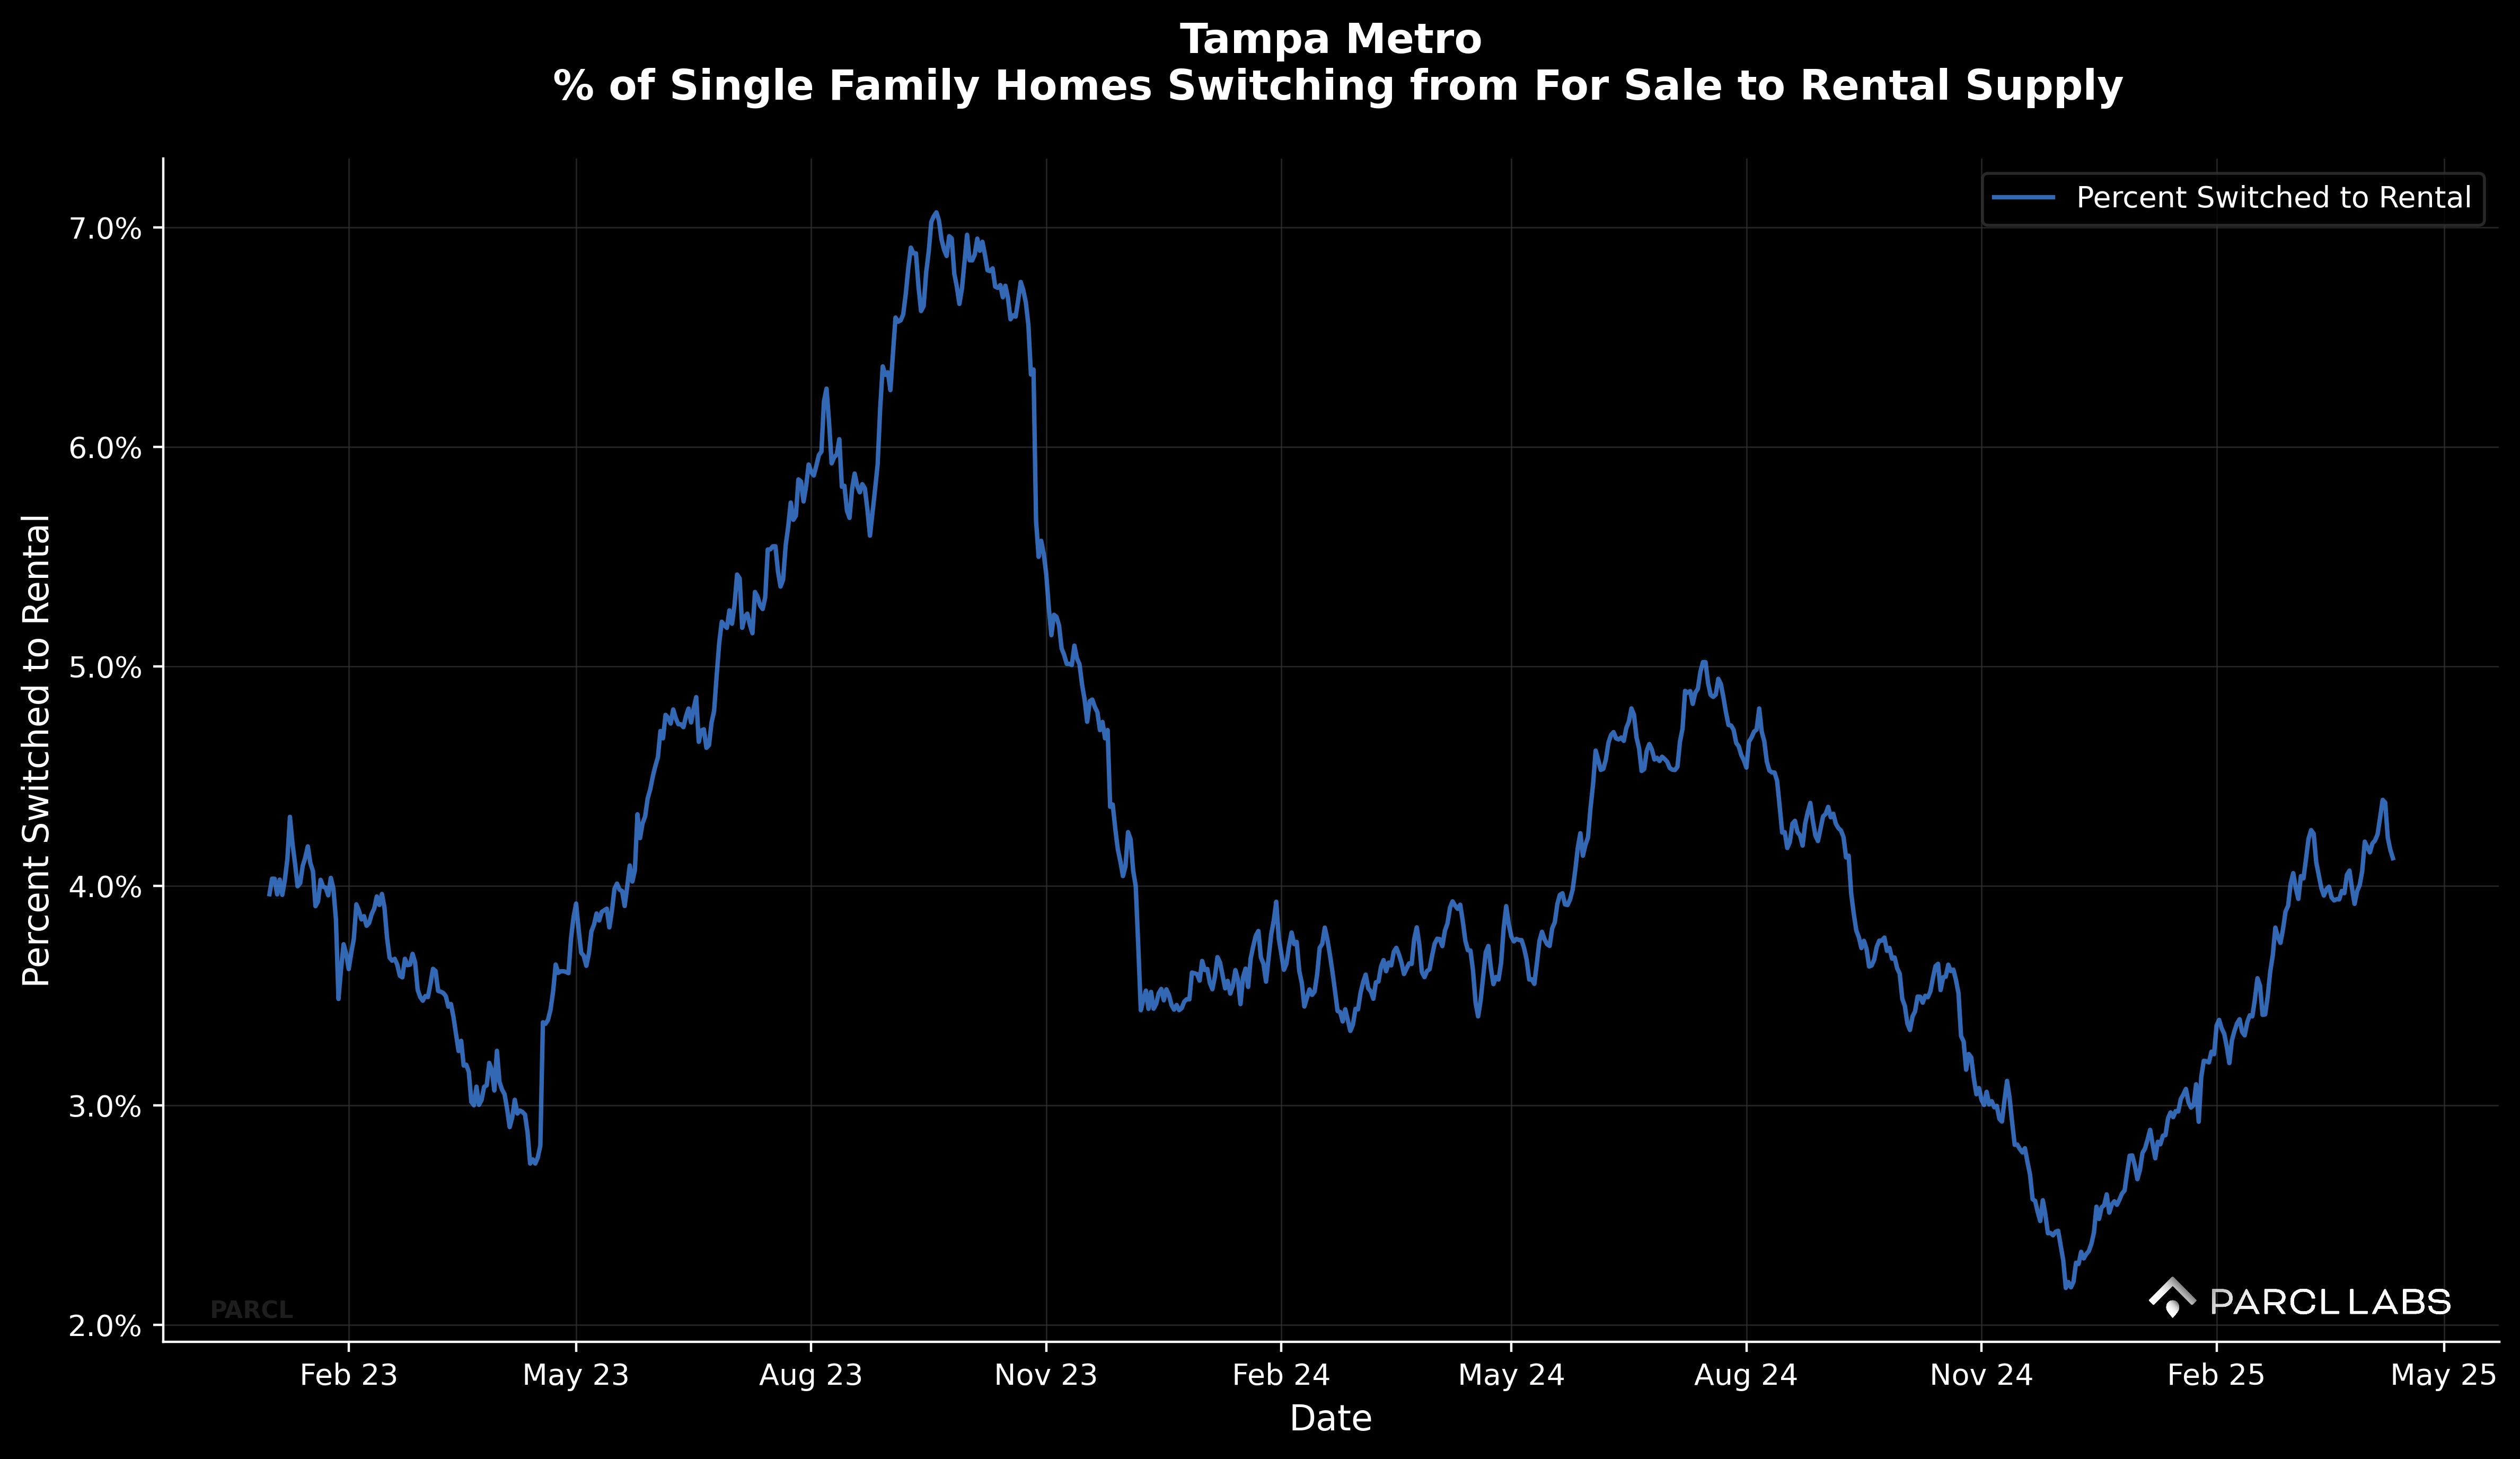
Chart 6: Phoenix Metro Accidental Landlord Rate (January 2023 - April 2025)
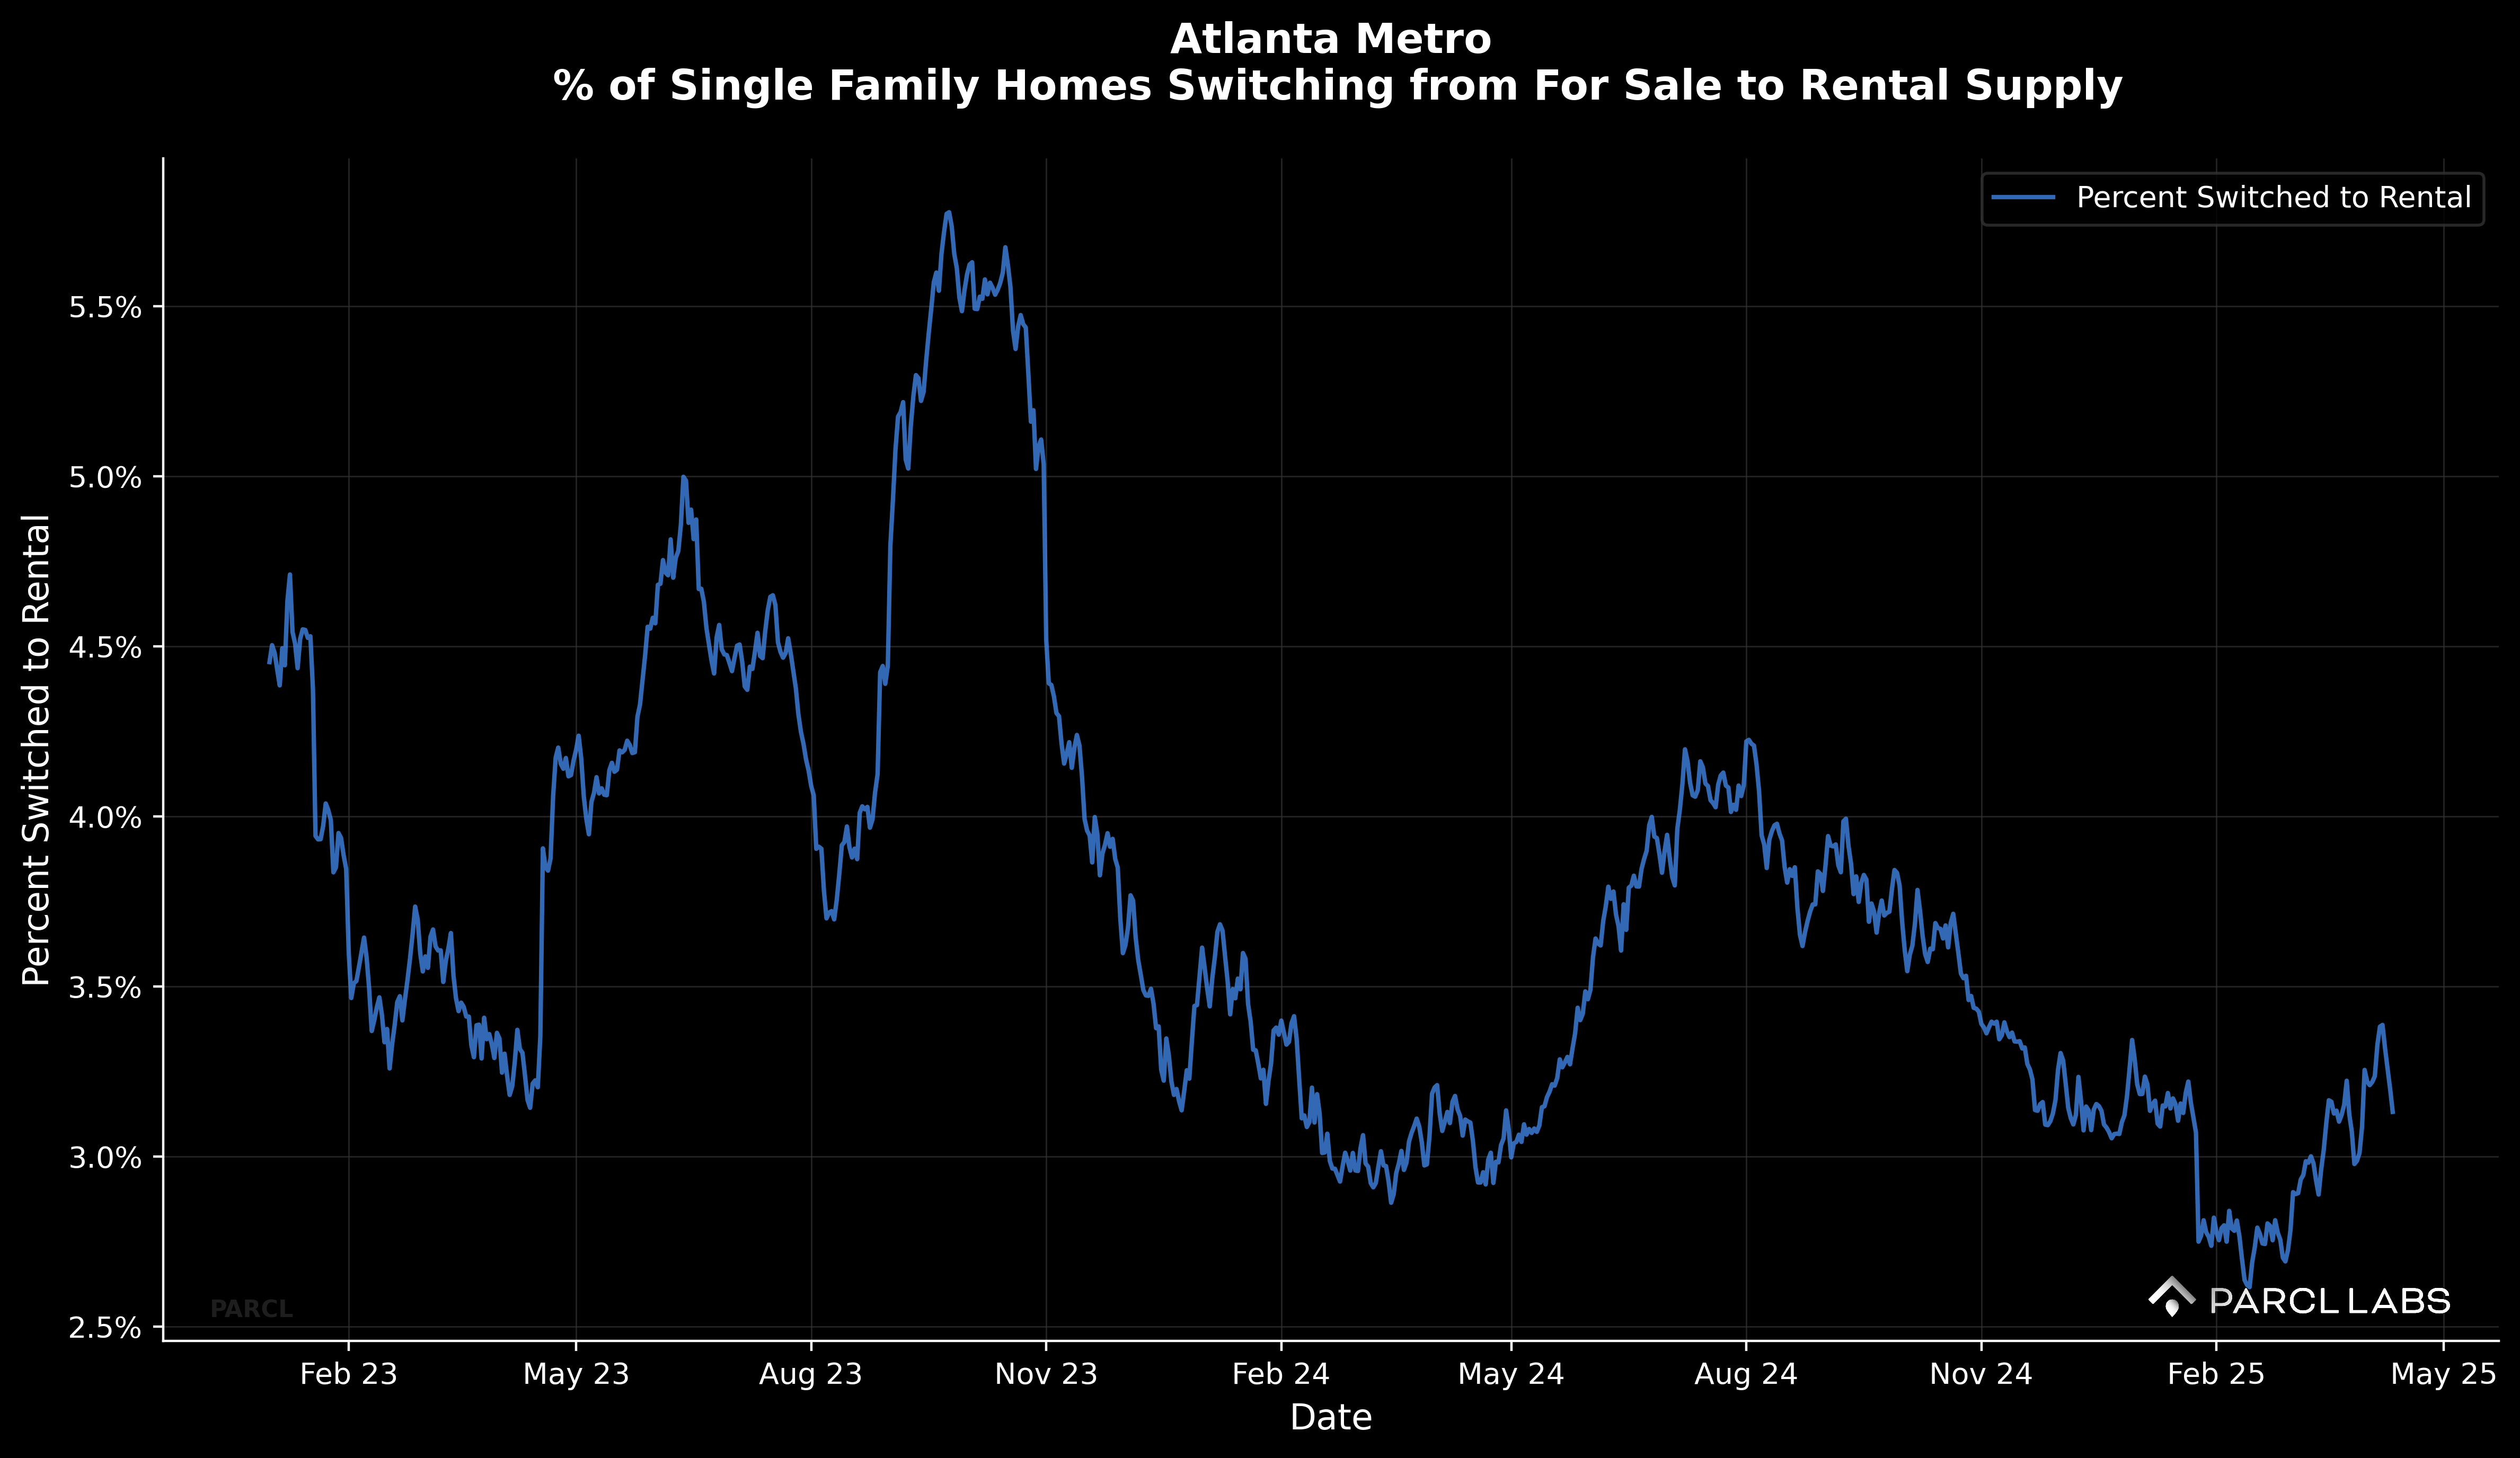
Atlanta shows modest YoY expansion.
Chart 7: Atlanta Metro Accidental Landlord Rate (January 2023 - April 2025)
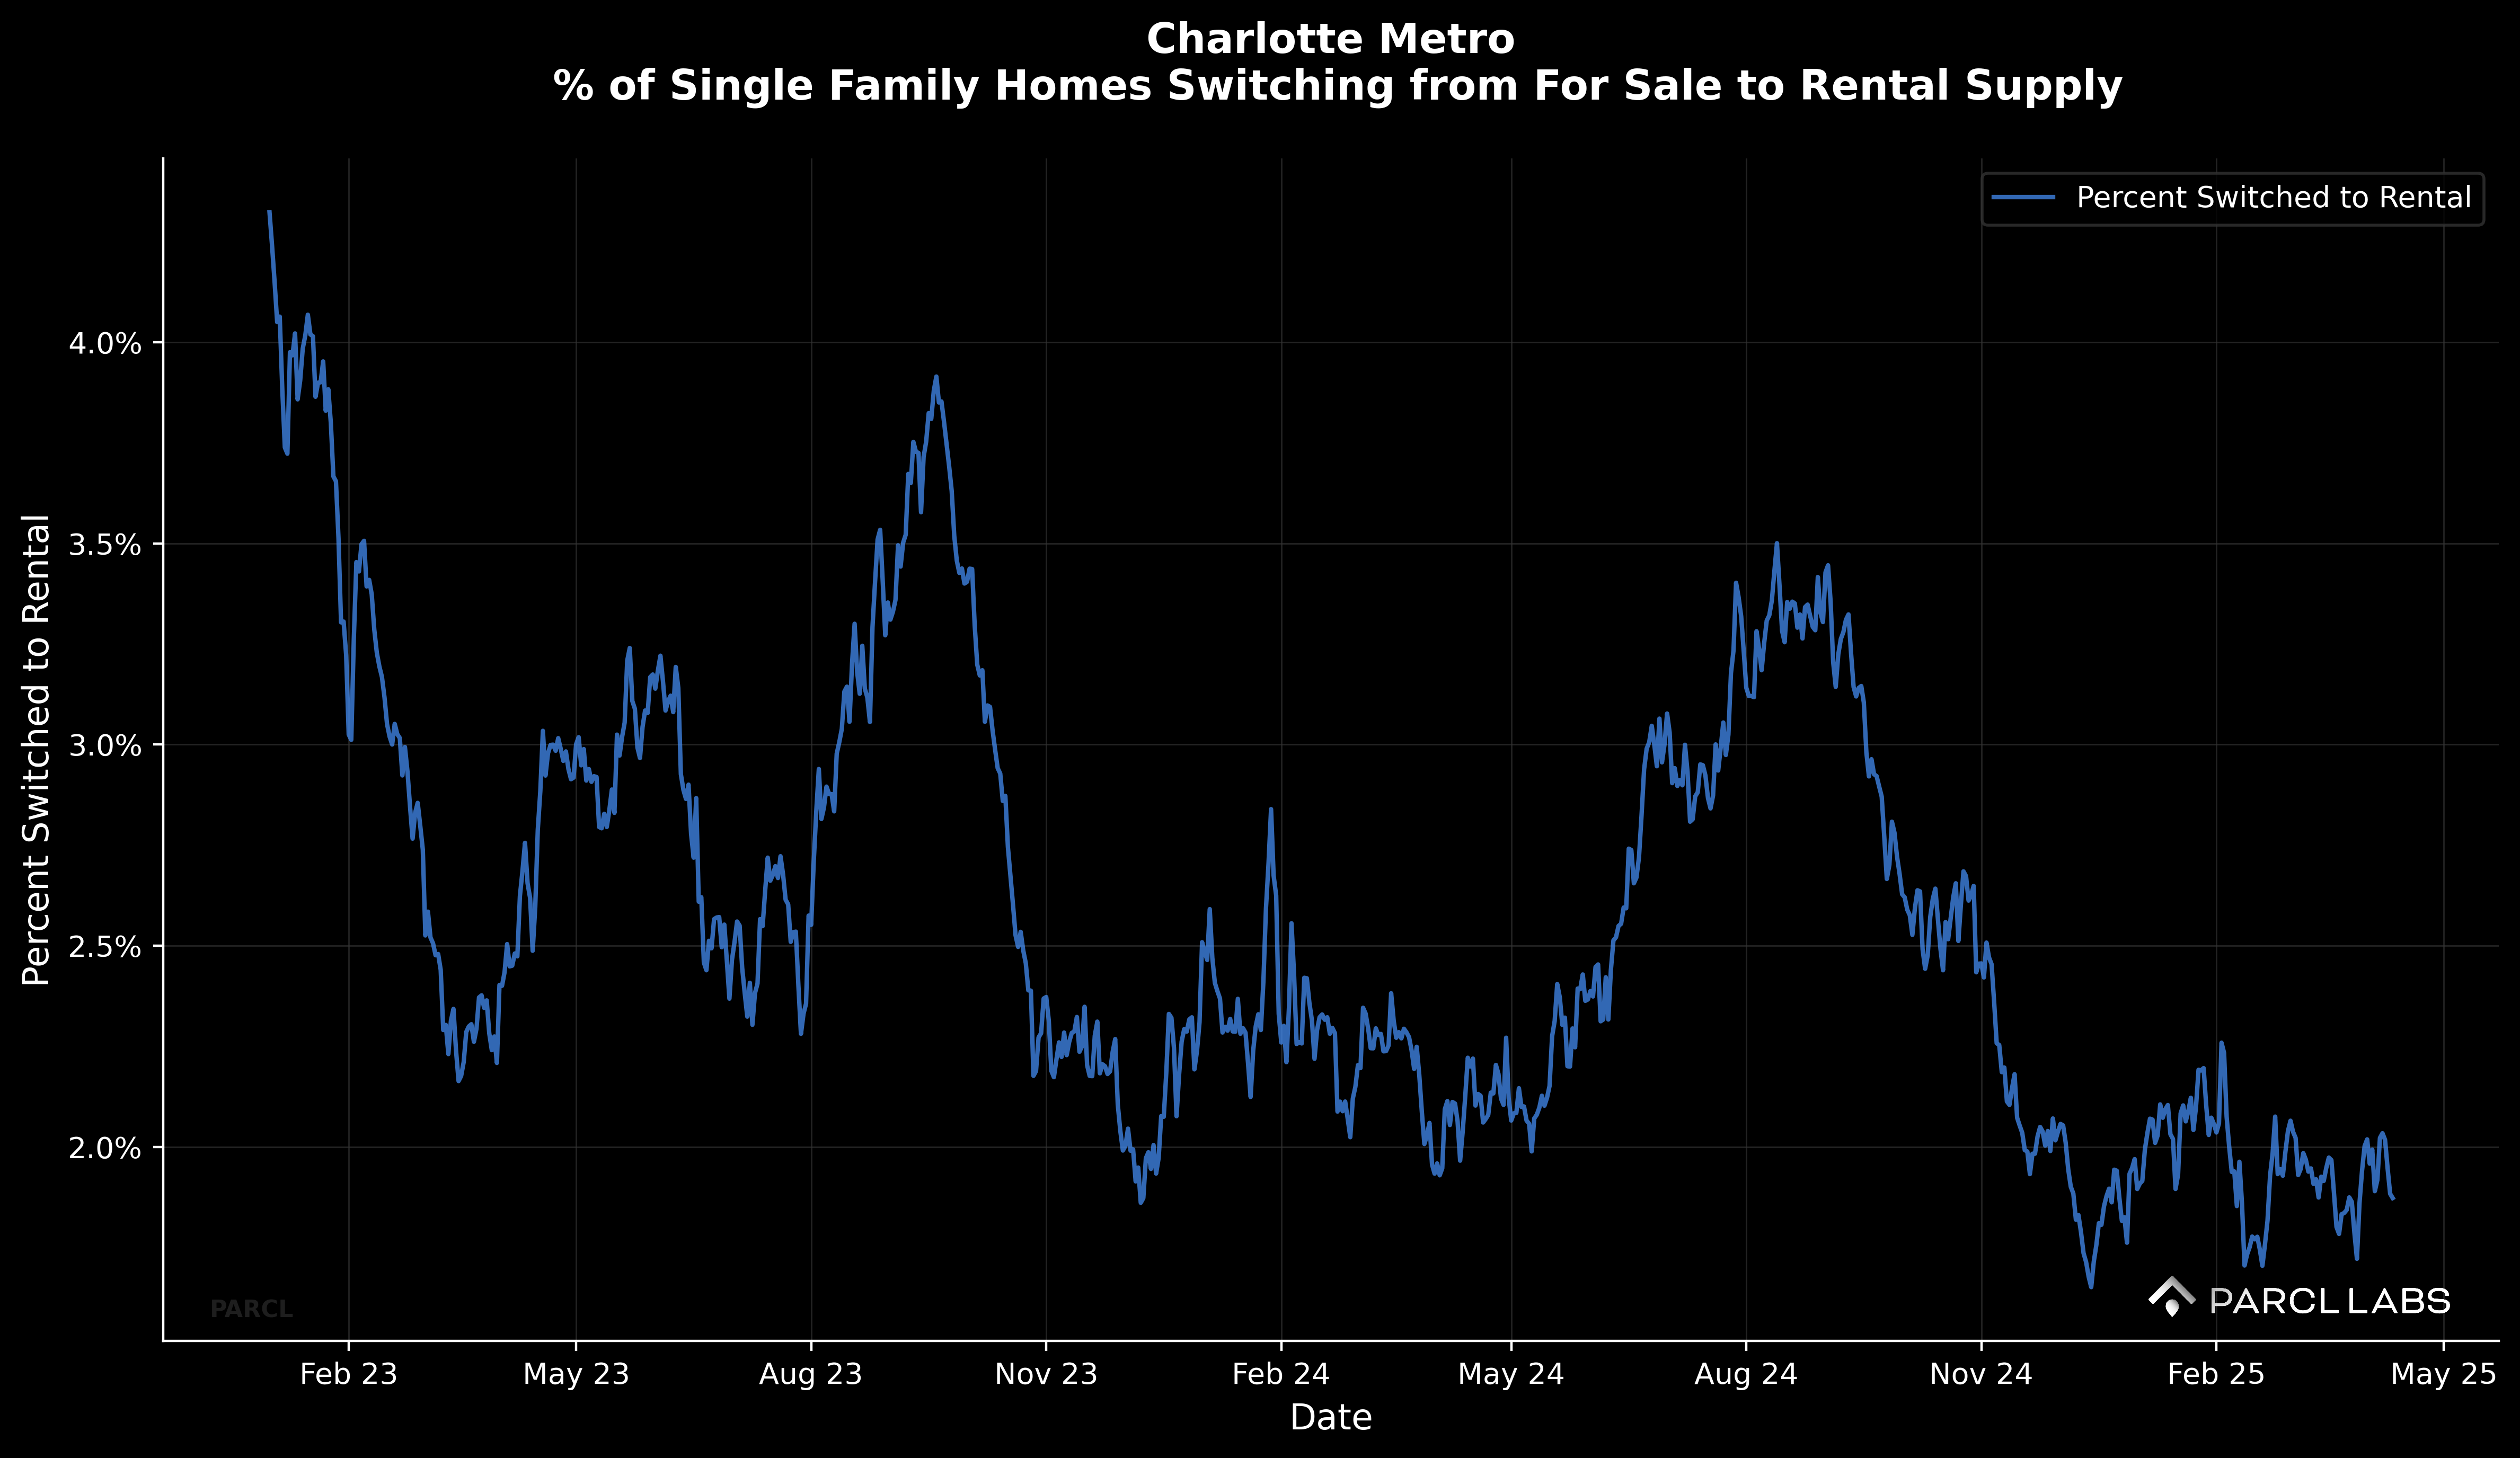
Charlotte presents the sole exception, with accidental landlord rates declining 7.2% year-over-year to 2.0%.
Chart 8: Charlotte Metro Accidental Landlord Rate (January 2023 - April 2025)
Institutions Switch to Defense
Accidental landlord rates matter because they represent more rental supply entering already-competitive markets. Unlike institutional operators who use sophisticated rent optimization strategies, accidental landlords typically price units simply to cover costs. This dynamic creates downward pressure on rents exactly where institutional investors have concentrated their portfolios.
The combination of increased rental competition and weakening home-price fundamentals suggests institutions may want to reduce some exposure in these markets. The window to realize outsized pandemic-era appreciation gains in these Sunbelt markets is closing. Parcl Labs forecasts home prices will remain flat or decline over the next year in five of the six featured institutional markets, primarily driven by inventory dynamics outlined above.
Parcl Labs analysis confirms institutions are already retreating. Nationally, large institutional investors turned net sellers between March 2024 and April 2025:
Market | Acquisitions | Dispositions | Net |
|---|---|---|---|
United States | 33,536 | 38,968 | -5,432 |
(March 2024 - April 2025)
Net selling activity heavily concentrates in the six core markets:
Market | Acquisitions | Dispositions | Net |
|---|---|---|---|
Atlanta | 1,602 | 2,828 | -1,226 |
Dallas | 2,459 | 3,268 | -809 |
Houston | 1,582 | 2,367 | -785 |
Tampa | 757 | 1,444 | -687 |
Phoenix | 1,158 | 1,691 | -533 |
Charlotte | 1,172 | 1,299 | -127 |
Six Markets Combined | 8,730 | 12,897 | -4,167 |
(March 2024 - April 2025)
These six markets represent 36.8% of large institutional holdings nationwide but account for 76.7% of net selling. The pullback is unmistakable.
The critical question: is this defensive positioning temporary? One possibility: institutions may be building cash reserves to buy when markets bottom. In that scenario, accidental landlords could transition from competitors to acquisition targets. After struggling with property management, these reluctant landlords may become motivated sellers. Institutions would gain both leverage from distressed pricing and rental performance data to inform underwriting.
Whatever’s next, Parcl Labs remains the only real-time source of accidental landlord data. For real estate players navigating shifting markets, understanding the interplay between failed home sales, rental conversions, and institutional positioning is alpha for identifying emerging risks and strategic opportunities.
Methodology
Parcl Labs generated all data, analysis, and research cited in this article. You can replicate this analysis for any market in the U.S. using the Parcl Labs API.
Accidental Landlord Methodology
Our analysis uses a rolling window approach to identify properties that transition from for-sale to for-rent listings. For each analysis date, we examine property events within a 110-day window:
50 days prior: Listing lookback period
60 days forward: Rental lookahead period
Properties qualify as "switched" when they meet specific criteria. They must show legitimate for-sale activity (new listings, price changes, or relistings) during the lookback window, followed by rental activity (rental listings, rent adjustments, or rental relistings) during the lookahead period. The same entity must own the property throughout this period.
To ensure data quality, we apply two key exclusions. First, we remove properties with sales transactions anywhere within the 110-day window, as these represent successful sales rather than strategic pivots. Second, we exclude properties with multiple ownership changes, as these likely indicate distressed sales or institutional activity rather than deliberate rental conversions.
This window-based approach captures the dynamic nature of property marketing decisions while maintaining analytical rigor. By focusing on same-owner transitions, we isolate intentional shifts from sale-to-rental strategies that reflect true market adaptation.
Continue Reading
Subscribe to access the full article and unlock exclusive insights.
Follow Us for More